
Learn Why The Bull Case For Elastic Stock Could Change Following Investor Pressure
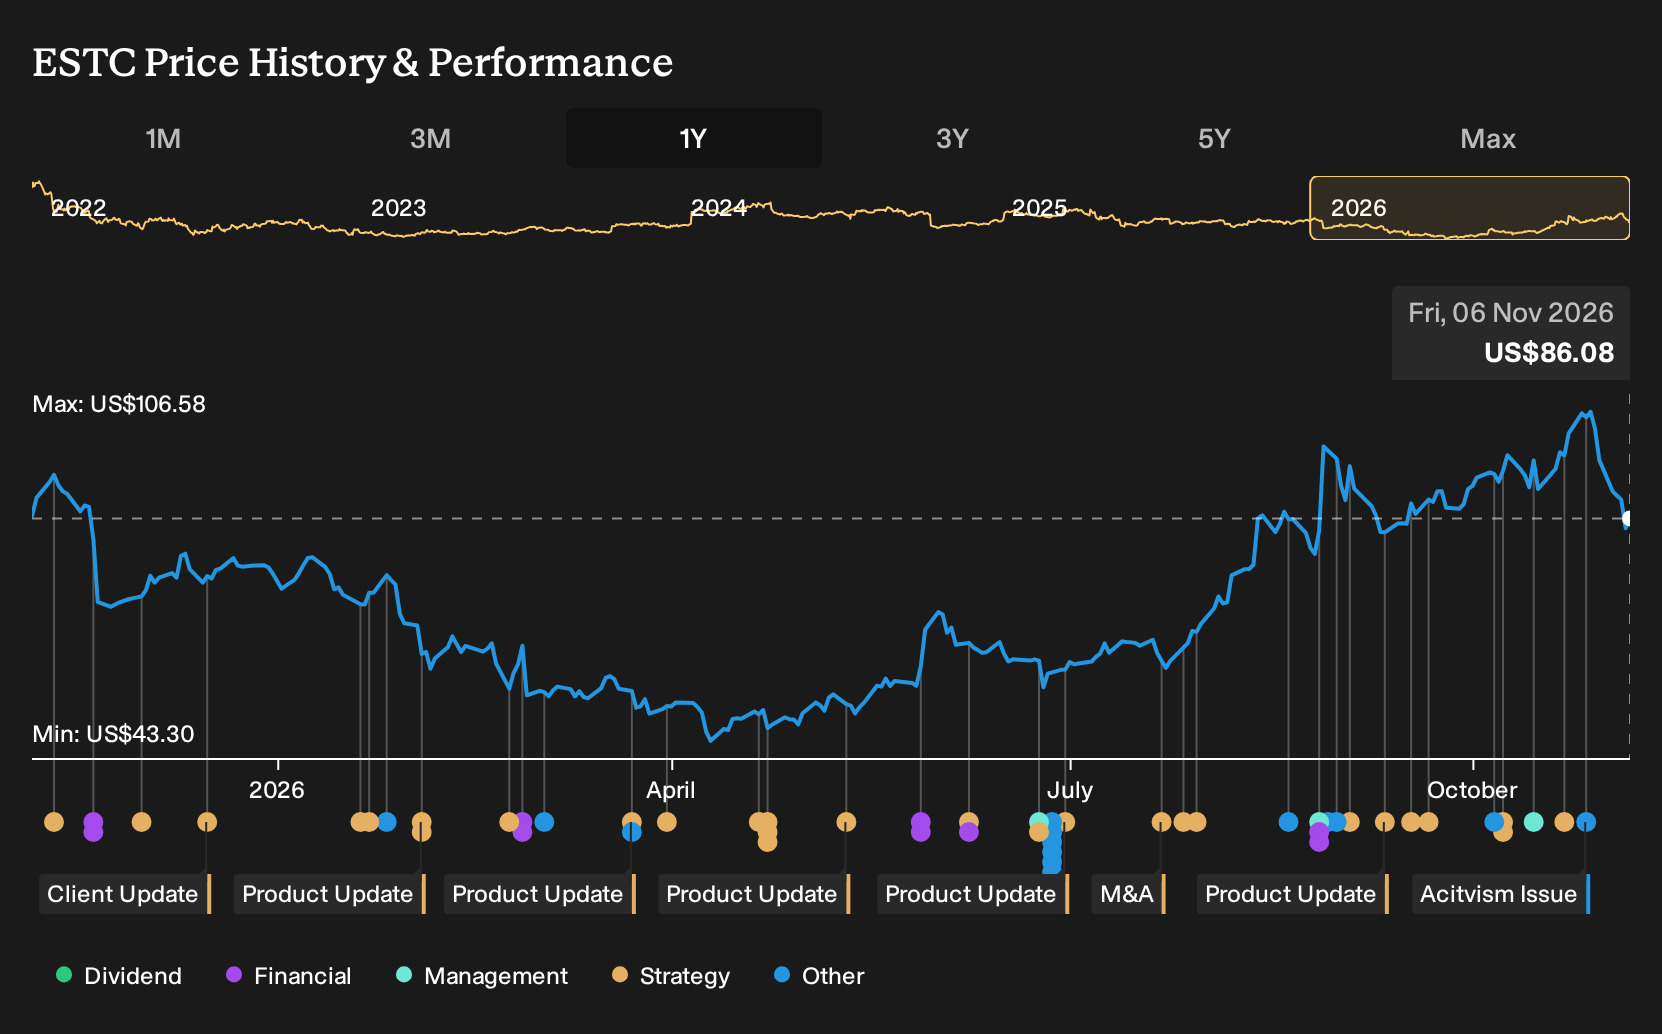
- Pictet Asset Management SA recently confirmed it is actively engaging with Elastic N.V., seeking improvements in business practices that it believes could support long term shareholder value.
- This kind of focused institutional input can influence how Elastic prioritizes its AI, observability and security investments, particularly in relation to cost discipline and capital allocation.
- We now examine how this renewed engagement from Pictet could affect Elastic's investment narrative and the overall balance of risk and potential reward for shareholders.
Scan how activist pressure on Elastic compares with other software players facing similar scrutiny by reviewing the curated list of 29 resilient stocks with low risk scores, which is aligned with tighter governance and disciplined capital use.
Elastic Investment Narrative Recap
For an investor to stay with Elastic, the core belief is that its search, AI, observability and security platform keeps winning meaningful data workloads from enterprises. The key short term catalyst is the upcoming Q2 fiscal 2027 results on 19 November 2026, which will give a cleaner read on usage trends, Elastic Cloud traction and any impact from competition.
The biggest near term risk remains execution against intensifying offerings from large cloud providers, while earnings are forecast to decline over the next three years. Pictet's engagement may encourage discipline on spending and capital use, but based on current information it does not materially change that operational risk reward balance yet.
The most relevant near term announcement is Elastic's plan to report Q2 fiscal 2027 numbers and host a conference call on 19 November 2026. For someone tracking the stock, that event is where management can explain how AI driven workloads, Elastic Cloud adoption and security use cases are reflected in revenue and profitability today.
That call also arrives shortly after Pictet signaled its active engagement on business practices, so investors can listen for any sharper commentary around cost control, capital allocation and pricing. With earnings expected by analysts to decline over the next few years, while revenue is forecast to grow around the mid teens, clarity on unit economics and cash generation on that call could matter more than headline growth.
What Pictet’s Engagement Means Against Elastic’s Current Forecasts
Elastic's narrative projects revenues of US$2.7b and earnings of US$48.3m by 2029. This sits alongside analyst assumptions of 14.6% yearly revenue growth and an earnings decline of US$327.3m from US$375.6m today.
Uncover why Elastic's fair value indicates a 29% potential upside to its current price before that discount is priced away.
Exploring Other Perspectives
Some of the most optimistic analysts frame Pictet’s engagement as a potential accelerator for Elastic, because their pre news models already assumed about 17.9% annual revenue growth and US$173.0 million of earnings by 2029. You can compare that upbeat view with the more cautious consensus and decide which assumptions feel closer to your own.
Explore 4 other Elastic fair value estimates, including one that suggests there could be as much as 83% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker, look into the data and build a conviction that is truly your own.
- A great starting point for your Elastic research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Elastic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elastic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Elastic?
Once you have a view on Elastic, it can help to compare it with other companies that have different risk, income and balance sheet profiles so your portfolio is not relying on a single story.
- If you want potential upside combined with quality fundamentals, compare Elastic with a curated pool of 19 high quality undiscovered gems that may not yet be widely followed.
- For investors who care about capital strength and financial resilience, consider Elastic alongside companies from a list of solid balance sheet and fundamentals (24 results) to see how its profile compares.
- Income focused readers who prefer regular cash returns can contrast Elastic with a set of 8 dividend fortresses that aim to provide higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com