
Did EssilorLuxottica's Fall Catch You Out? What Investors Missed
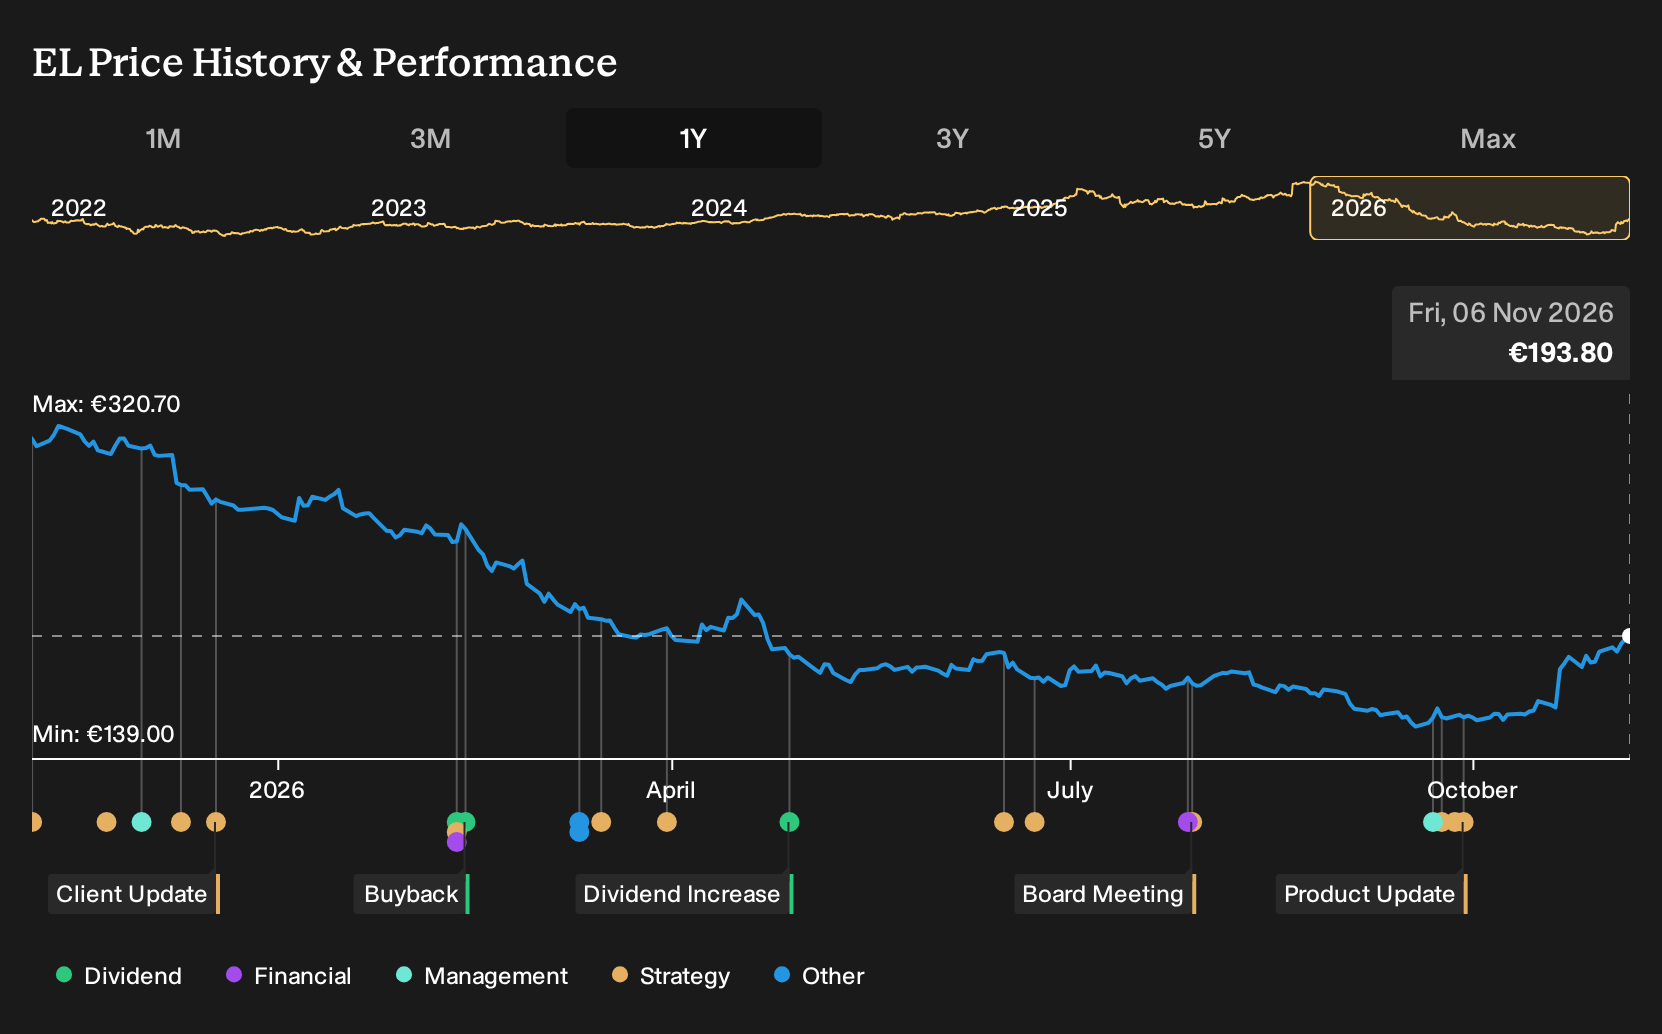
EssilorLuxottica Société anonyme kept making headlines as the Del Vecchio heirs battled for control of Delfin and, by extension, influence over the eyewear giant itself. For EssilorLuxottica Société anonyme shareholders, the loss over the past year was 35.7%, including dividends. If you had bought at the start of that period thinking family intrigue would create value, the outcome looks harsh. The key question now is whether that governance reset changes how you rate the business from here.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made EssilorLuxottica Société anonyme harder to judge, start where the gap is still open and scan 225 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On EssilorLuxottica
The shares cost €313 at the start of the period, and EssilorLuxottica Société anonyme sat between two very different but reasonable stories.
On the upbeat side, one narrative put Fair Value at €400, 28% above the start price. It leaned on revenue growth assumptions of 13.7% and a future P/E of 57.0x, tied to smart glasses partnerships and the Supreme acquisition.
The cooler take set Fair Value at €278, 11% below the start price. That view still pencilled in 6.4% revenue growth and an 11.4% profit margin, but flagged execution, regulation and margin pressure as key risks.
What The EssilorLuxottica Evidence Actually Showed
The clearest datapoint came from EssilorLuxottica reporting H1 2026 figures, with revenue at €14,818m and net income at €1,566m against €14,024m and €1,387m in H1 2025. Net margin moved from 9.9% to 10.6%. That trajectory backed the optimistic case on profitability, while the family governance wrangle kept the cautious scenario on control and execution alive. Overall, the evidence cut both ways.
The useful takeaway is simple. When a story leans on premium growth, check whether net income and margin ratios, not just sales, are moving in the same direction as the narrative you are paying for.
What EssilorLuxottica's Drop Has Left In Today's Price
EssilorLuxottica Société anonyme now trades at €194 after the share price fell about 35.7% over the past year. The selected Narrative sees Fair Value above that level, based on a bigger role for eye care services, smart eyewear and myopia solutions.
On this view, a buyer today is effectively assuming EssilorLuxottica can turn its current traction in AI glasses and oculomics hubs into scalable, profitable platforms across major regions.
"Bullish analysts expect EssilorLuxottica Société anonyme to build on growth in smart glasses, myopia management and vertically integrated ecosystems so that eye care, wearables and medtech become a larger share of the business mix. The main thing that has to go right is that EssilorLuxottica Société anonyme turns its early traction in AI glasses, oculomics centers and global myopia solutions into scalable, profitable platforms across major regions despite rising competition and governance noise."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond EssilorLuxottica's Frames
EssilorLuxottica keeps attention on eyesight and everyday vision needs. Just beside that focus, surgeons face another precision challenge deep inside the body.
They need tools that convert tiny hand movements into deliberate action during surgery. Robotic platforms aim to support that, turning intent into steady, minimally invasive procedures.
The business behind these systems offers more than surgical hardware alone. It surrounds operations with software, training programs and continuous support so clinicians can refine technique.
With that embedded role in hospital routines and learning, another issue emerges. What happens when a technology platform becomes part of how medicine itself is practiced?
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 18% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com