
COPT Defense Properties (CDP) Could Be 17% Below Fair Value After Earnings Beat
Earnings beat and higher guidance put COPT Defense Properties in focus
COPT Defense Properties (CDP) has jumped onto investor watchlists after reporting higher third quarter and year to date sales, revenue, and net income, along with raised full year earnings guidance and fresh fourth quarter EPS estimates.
The latest earnings beat and higher guidance arrive after a mixed year on the screen for COPT Defense Properties, with the share price up 19.57% year to date but down 11.50% over 90 days. Long-term momentum remains stronger with a 58.65% three-year total shareholder return.
Spot fresh momentum stories like COPT Defense Properties by scanning our hand picked list of 39 high quality undervalued stocks that combine solid fundamentals with potential mispricing.Bulls see COPT Defense Properties as a stronger earner now trading below some estimated fair value, while bears point to the recent pullback as a warning. Which side do the current valuation markers support?
Most Popular Narrative: 17% Undervalued
The most followed valuation story on COPT Defense Properties pegs fair value at $39.75, above the recent $32.87 close. This frames the current price as a discount that depends on defense linked leasing and cash flow holding up against financing costs.
The main thing that has to go right is that COPT Defense continues to convert its high retention, near full leasing at key campuses and mostly pre leased development pipeline into cash flow growth that offsets higher financing costs.
The balance sheet position that includes an investment grade Baa2 unsecured rating, leverage that management aims to keep around 6x debt to EBITDA and a self funding model for roughly US$250m to US$300m of annual development provides capacity to keep growing the portfolio without common equity issuance.
See why 0 investors see COPT Defense Properties as 17% undervalued.
Result: Fair Value of $39.75 (UNDERVALUED)
Still, the story around COPT Defense Properties can change quickly if higher refinancing costs squeeze cash flow or if expected re leasing in weaker offices disappoints.
Find out about the key risks to this COPT Defense Properties narrative.
Another view on COPT Defense Properties valuation
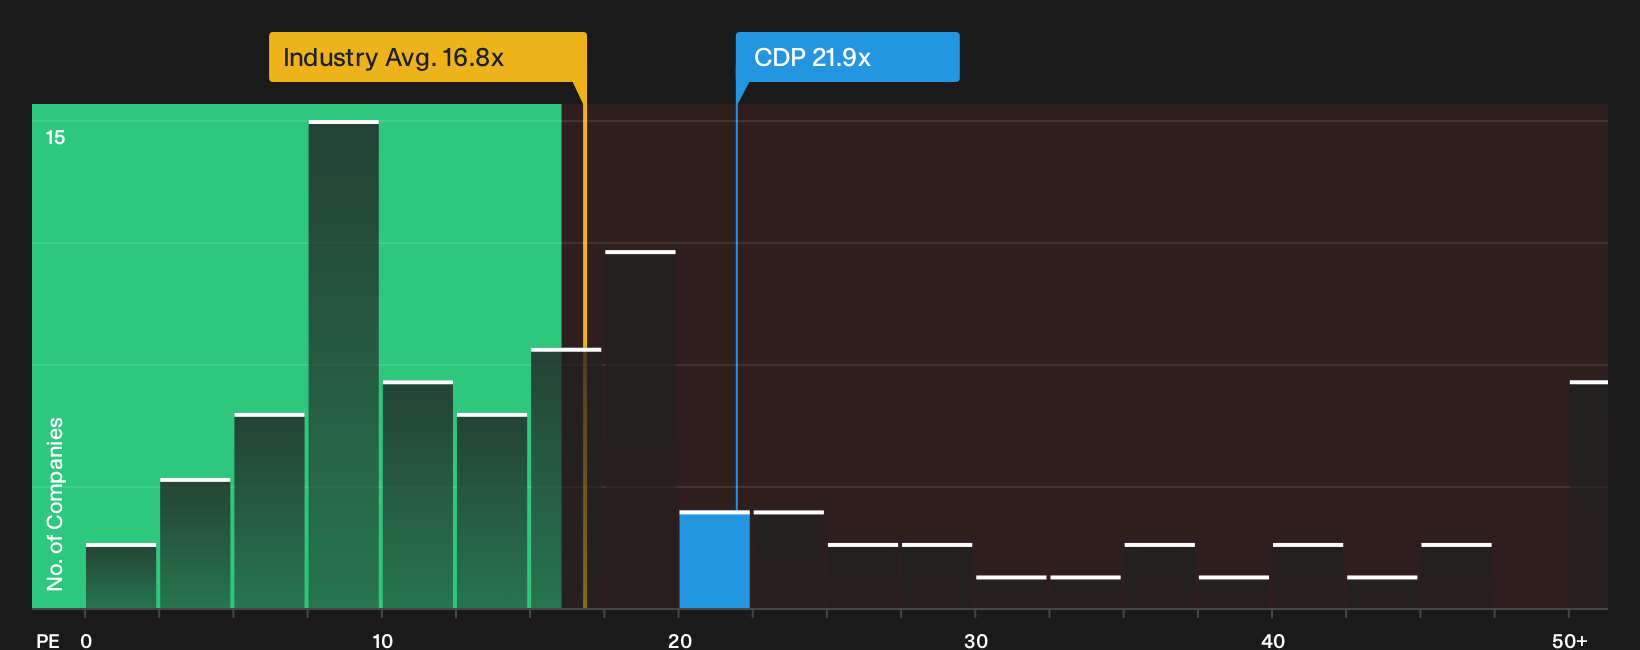
A different lens tells a less generous story. COPT Defense Properties trades on a P/E of 21.9x, above the Global Office REITs average of 16.8x, even though the fair ratio sits higher at 30.6x. That mix of premium to peers yet discount to fair ratio leaves a simple question: Is this a rerating risk or a valuation gap?
For a deeper look at how these earnings multiples stack up against what the numbers imply, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on COPT Defense Properties so far. If you want to move faster than the crowd and sharpen your own take, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond COPT Defense Properties?
If COPT Defense Properties has sharpened your thinking, do not stop here. Broaden your watchlist with focused ideas that match your risk, income, and quality preferences.
- Target higher income potential and stress test your yield goals against a curated set of 8 dividend fortresses built around robust payout profiles.
- Upgrade portfolio resilience by scanning a list of solid balance sheet and fundamentals (24 results) that can help you avoid fragile finances when conditions get tougher.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems before attention and pricing fully catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com