
Clean Harbors (CLH) Posts Strong Q3 Results, Is The Stock Still Undervalued?
Clean Harbors shares jumped 2.30% on the day of the announcement to US$284.10, even though the 30 day share price return is down 9.96% and the 90 day move is down 7.81%. This suggests short term momentum has cooled, while the 1 year total shareholder return of 36.63% and 5 year total shareholder return of 167.74% point to a longer track record that investors are still weighing against the latest results and leadership changes.
Spot similar earnings-driven setups to Clean Harbors by scanning our curated 19 high quality undiscovered gems, which pair improving fundamentals with under-the-radar status.Clean Harbors now appears to be a powerful operation on the back of these fresh results. However, the recent share price pullback raises a simple question: Are you paying up, or paying fair, for that strength?
Most Popular Narrative: 18.8% Undervalued
Clean Harbors closed at $284.10, while the most followed narrative pegs fair value at $350. That gap is exactly what many investors are trying to size up after the latest earnings and guidance.
The story is not simply that Clean Harbors cleans up hazardous waste.
The deeper investment thesis is: Modern society keeps producing hazardous waste, and somebody has to safely collect it, transport it, treat it and dispose of it. Clean Harbors owns one of the most difficult-to-replicate infrastructure networks required to do that.
See why 2 investors see Clean Harbors as 19% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Clean Harbors thesis can be shaken if tighter environmental rules slow new facility permits, or if acquisition integration fails to deliver expected benefits.
Find out about the key risks to this Clean Harbors narrative.
Another View: What The P/E Ratio Says About Clean Harbors
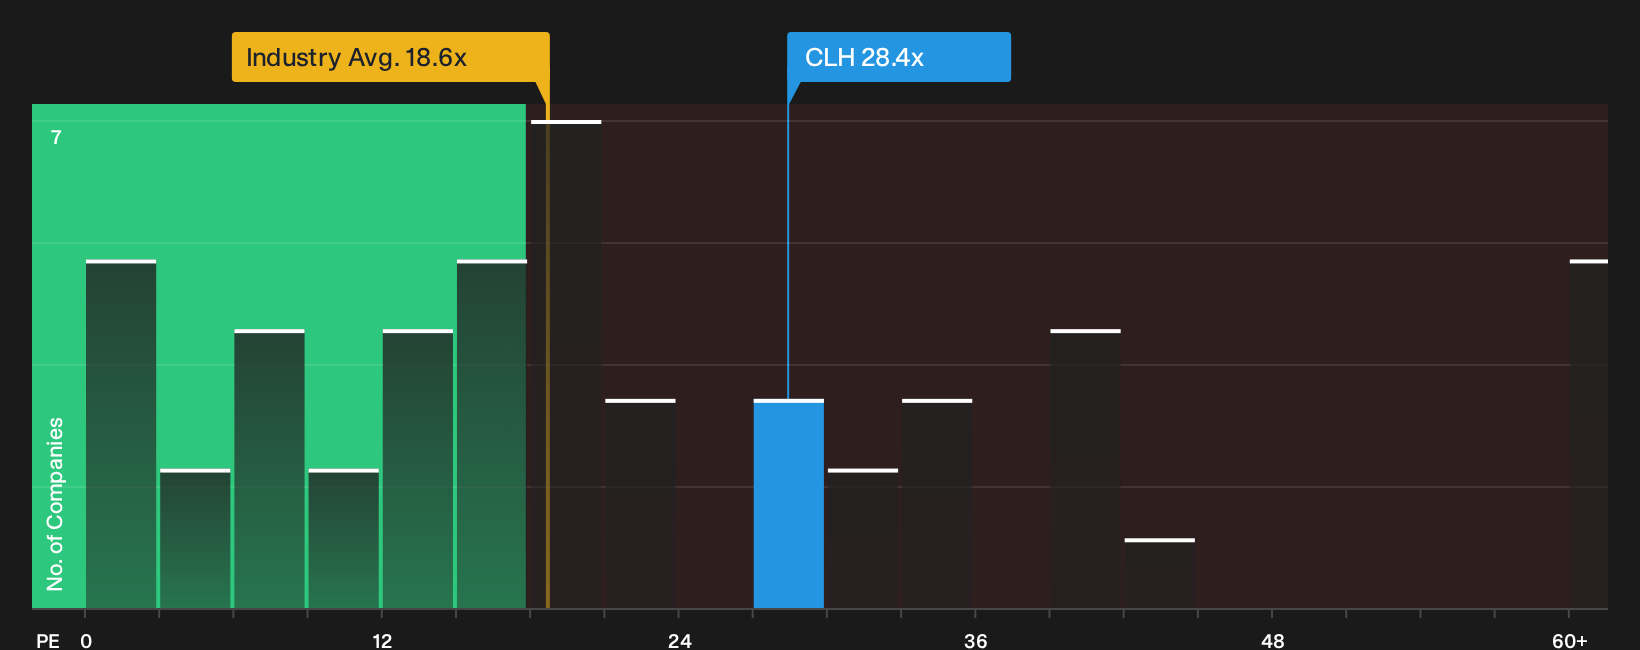
The SWS DCF model points to Clean Harbors trading at a 39.9% discount to estimated future cash flow value, yet the P/E ratio tells a different story. At 28.4x earnings, the stock sits above the US Commercial Services average of 18.6x and above the 21.4x fair ratio. Is that discount a cushion, or a signal that expectations already run hot?
For investors weighing that gap between cash flow value and earnings multiples, it helps to see how the valuation breaks down over time, not just at one price point. That is exactly what the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed reactions to Clean Harbors so far. If you want to move quickly and make up your own mind, weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Clean Harbors?
If Clean Harbors caught your attention, do not stop here. The same tools that surface this kind of setup can help you build a stronger watchlist fast.
- Hunt for quality at a discount by scanning our curated pool of 39 high quality undervalued stocks that combine solid fundamentals with attractive pricing signals.
- Lock in income potential by reviewing a focused group of 8 dividend fortresses that aim to pair higher yields with resilient business profiles.
- Protect your downside by filtering for 29 resilient stocks with low risk scores where balance sheet strength and risk scores do the heavy lifting before you commit capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com