
Learn Why The Bull Case For First Horizon (FHN) Could Change Following $4.5 Billion Mortgage Sale
- First Horizon Corporation has agreed to sell a US$4.5b mortgage portfolio as a one time restructuring and plans to redirect capital toward securities, lower wholesale funding, and gradual client lending expansion.
- The mortgage exit shifts First Horizon toward broader relationship based and higher yielding lending, which directly targets earnings and return on tangible common equity efficiency rather than mortgage volume.
- We will now explore how First Horizon's mortgage portfolio sale reshapes its investment narrative around capital deployment and earnings mix.
Scan how First Horizon’s mortgage exit and board refresh compare with other banks reshaping their balance sheets by moving through our hand picked list of solid balance sheet and fundamentals (24 results).
First Horizon Investment Narrative Recap
To own First Horizon, you need to believe the mortgage exit, capital redeployment, and balance sheet tweaks can support earnings without eroding its funding base. The short term swing factor is whether relationship driven commercial and wealth revenue can keep offsetting pressure from higher deposit costs and softer fixed income activity.
The biggest risk still sits in deposit competition. If funding prices keep grinding closer to wholesale levels, net interest margin could stay tight. The recent actions look meaningful for mix but do not fully change that near term risk. Execution on the multi year commercial uplift remains central to the story.
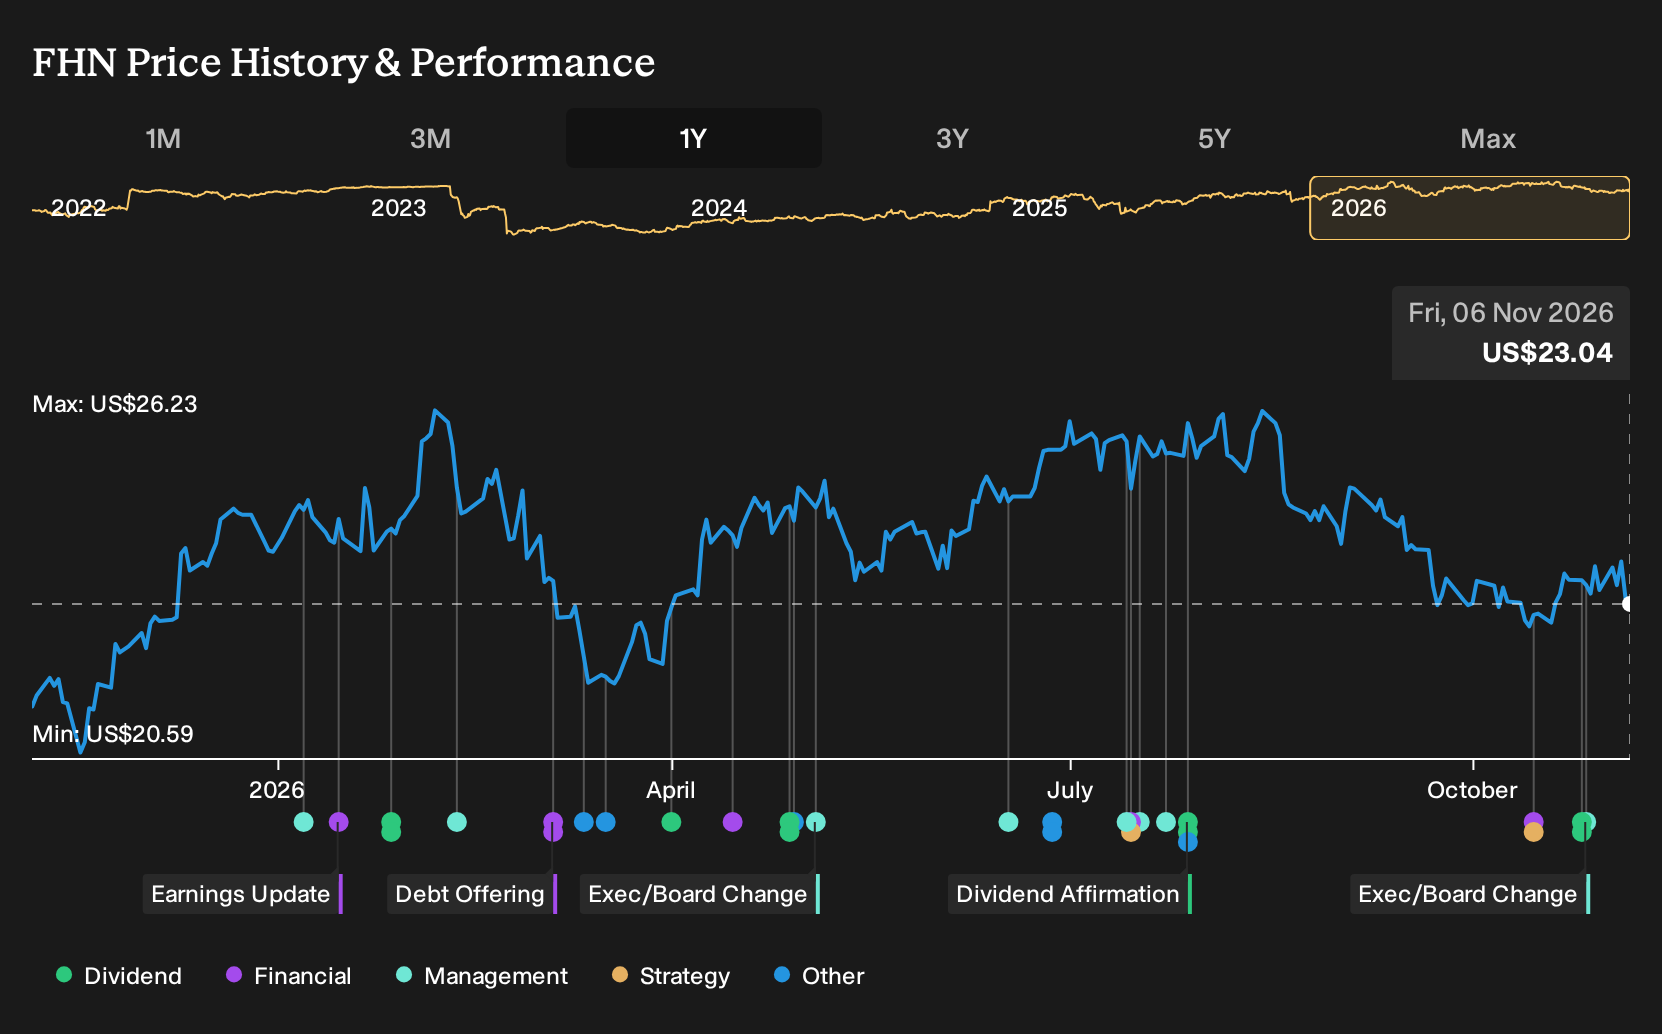
The most relevant fresh data point is the October common dividend affirmation at US$0.17 per share, payable in early January 2027. Keeping that payout signals management is holding its line on returning cash to shareholders while it reshapes the loan book and deploys capital from the US$4.5b mortgage sale.
For you, this ties straight back to catalysts and risk. If First Horizon can maintain this dividend alongside progress on commercial loan growth, wealth fees, and technology driven efficiency, income investors stay engaged. If earnings pressure from deposit costs or weaker fee income deepens, that fixed cash commitment could become a tougher balancing act.
What The Current Forecasts Assume For First Horizon
First Horizon's narrative projects US$4.0b revenue and US$1.1b earnings by 2029. This rests on analysts baking in 4.3% yearly revenue growth and an earnings increase of about US$100m from US$1.0b today.
Uncover why First Horizon's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for First Horizon from the Simply Wall St Community span roughly US$27.45 to US$47.68 across just 2 individual views, so opinions are already spread widely. When you layer on recent board changes, the mortgage portfolio sale, and committed common and preferred dividends, you can arrive at very different takeaways on future resilience. Explore the full range before deciding where you stand.
Explore another First Horizon fair value estimate, including one that suggests it could be worth just $27.45.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Horizon research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for First Horizon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Horizon's overall financial health at a glance.
Looking For More Ideas Beyond First Horizon?
If the First Horizon story has sharpened your view on risk, reward, and balance sheet strength, it can help to compare it with a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want potential mispricings with solid fundamentals, scan our set of 39 high quality undervalued stocks that might fit a value driven watchlist.
- If capital preservation and a smoother ride matter most to you, focus on companies screened as 29 resilient stocks with low risk scores that may better match a cautious profile.
- When the goal is finding resilient businesses with room to grow, broaden your search with a curated pool of 19 high quality undiscovered gems that are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com