
What Siemens (XTRA:SIE)'s Diagnostics Spin Off Means For Shareholders
- Siemens Healthineers has already set in motion a plan to separate and rebrand its in vitro diagnostics operations as Olyrian Diagnostics by mid 2028, while also dropping the Siemens name over a three year transition as Siemens prepares to relinquish its controlling stake.
- This reshaping of Siemens Healthineers tightens the Siemens group focus on industrial technology and digital infrastructure. It also leaves Healthineers to absorb separation, inflation and financing costs tied to carving out the diagnostics unit and standing up Olyrian as a standalone healthcare platform.
- We will look at how Siemens' investment narrative is influenced by the Healthineers diagnostics spin off and the related rebranding effort.
Compare how Siemens stacks up against peers reshaping factories and grids, and then broaden your watchlist with 42 power grid technology and infrastructure stocks steering the next phase of digital industrial infrastructure.
Siemens Investment Narrative Recap
To own Siemens, you need to be comfortable with an industrial group leaning harder into digital automation, electrification, and healthcare while absorbing the cost and complexity of reshaping its portfolio. The Healthineers diagnostics spin off and Olyrian carve out add execution work, but the core thesis still leans on large backlogs, software heavy revenue and data center linked demand.
In the near term, the key swing factor is how smoothly Siemens manages separation, inflation and financing expenses while keeping Digital Industries and Smart Infrastructure performing. The main risk is that project delays, weaker customer investment or Mobility related pressures hit orders and margins just as expectations around earnings quality stay high.
The Siemens Healthineers plan to separate Diagnostics into Olyrian by mid 2028 and phase out the Siemens name is the announcement that matters most here. It reinforces the parent company focus on industrial technology and digital infrastructure while pushing healthcare diagnostics costs and carve out complexity into a controlled, time bound process.
For you as a shareholder, the practical question is execution. Siemens needs Healthineers to fund separation and productivity programs without materially weakening group cash flows, while the parent leans into roles in digital transformation of factories and grids. If large project demand slows or cost savings slip, that could blunt the benefit of a more focused portfolio.
Siemens Consensus Assumptions After The Healthineers Diagnostics Spin Off
Sell side models sketch a Siemens that leans further into industrial tech while Healthineers prepares to send Diagnostics into Olyrian. That story is quantified through moderate top line growth, higher profit margins and a larger earnings base by the end of this decade.
Analysts currently assume Siemens' revenue will rise by 2.9% a year over the next three years, with profit margins moving from 9.7% today to 12.7% over the same period. Earnings are modeled at €7.9b today and are expected to reach €11.3b by 2029, which implies an earnings increase of about €3.4b over the next few years.
On those 2029 profit estimates, the equity research consensus uses a P/E of 24.4x, compared with 26.6x today and against a GB Industrials sector reference of 15.2x. Forecasts also factor in a 0.8% yearly decline in the share count over the coming three years and a discount rate of about 6.1% to bring those future cash flows back to today.
For you as an investor, that set of assumptions effectively prices Siemens as a higher quality industrial and software group that lifts margins while it simplifies the portfolio and deals with the Siemens Healthineers and Olyrian restructuring effort in the background.
Siemens' narrative projects €88.5b revenue and €11.3b earnings by 2029. This requires 2.9% yearly revenue growth and an earnings increase of about €3.4b from €7.9b today.
Discover why Siemens' fair value indicates a 16% potential upside to its current price that may not last much longer.
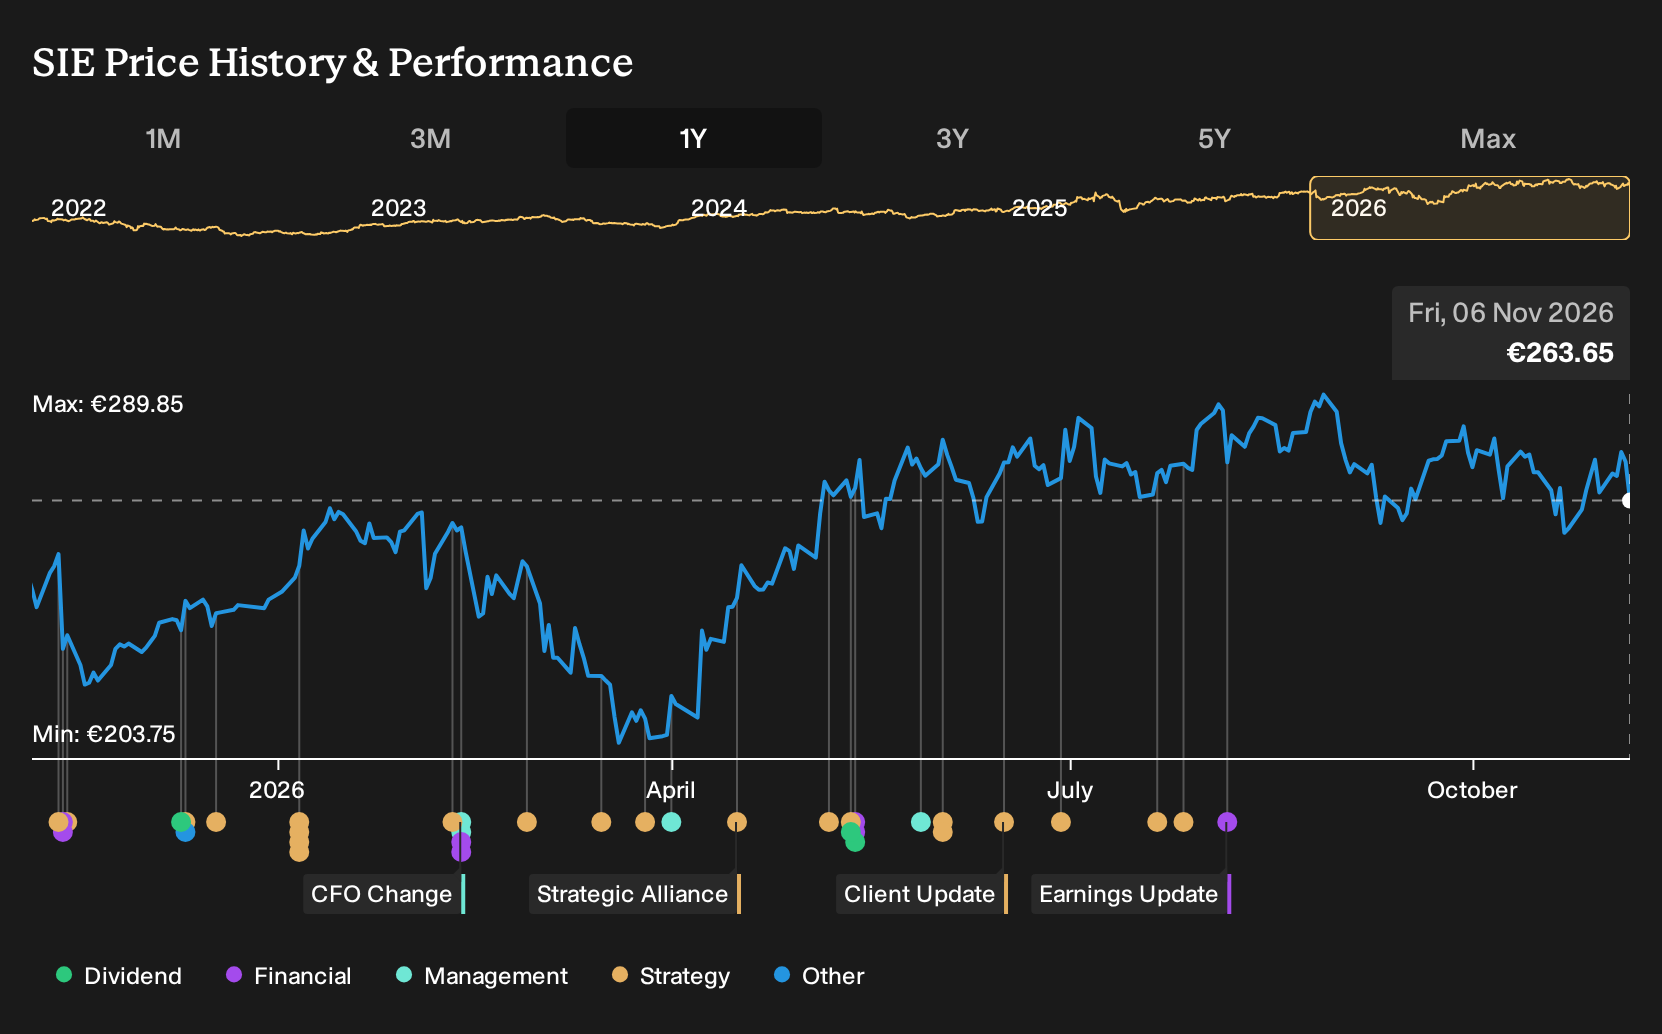
Exploring Other Perspectives
Some of the most optimistic Siemens analysts focus on a different catalyst: the potential for much faster top line expansion if AI driven software and grid work really take hold. Before this Healthineers and Olyrian update, the most bullish group was pencilling in 7.0% yearly revenue growth and about €11.5b earnings by 2029. That is far more upbeat than the consensus path and shows how far opinions can stretch. Use this news as a reason to compare those older assumptions with your own views and explore several alternative scenarios.
Explore 4 other Siemens fair value estimates, including one that suggests as much as 41% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Siemens research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siemens. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siemens' overall financial health at a glance.
Looking For More Ideas Beyond Siemens?
Once you have a view on Siemens, it can help to compare that thesis with other companies that have very different risk and return profiles. The Simply Wall St Screener lets you filter by balance sheet strength, valuation and income profile so you can build a watchlist that actually matches your goals.
- If capital preservation sits high on your list, start with companies that aim for steadier performance using the 212 resilient stocks with low risk scores.
- If you want potential mispricing with solid fundamentals behind it, look across the 588 high quality undiscovered gems and see which stories you find most compelling.
- If you care most about financial resilience and clean accounts, focus on businesses highlighted in the list of solid balance sheet and fundamentals (193 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com