
How Earnings Beat Will Impact Global Payments Stock (GPN)
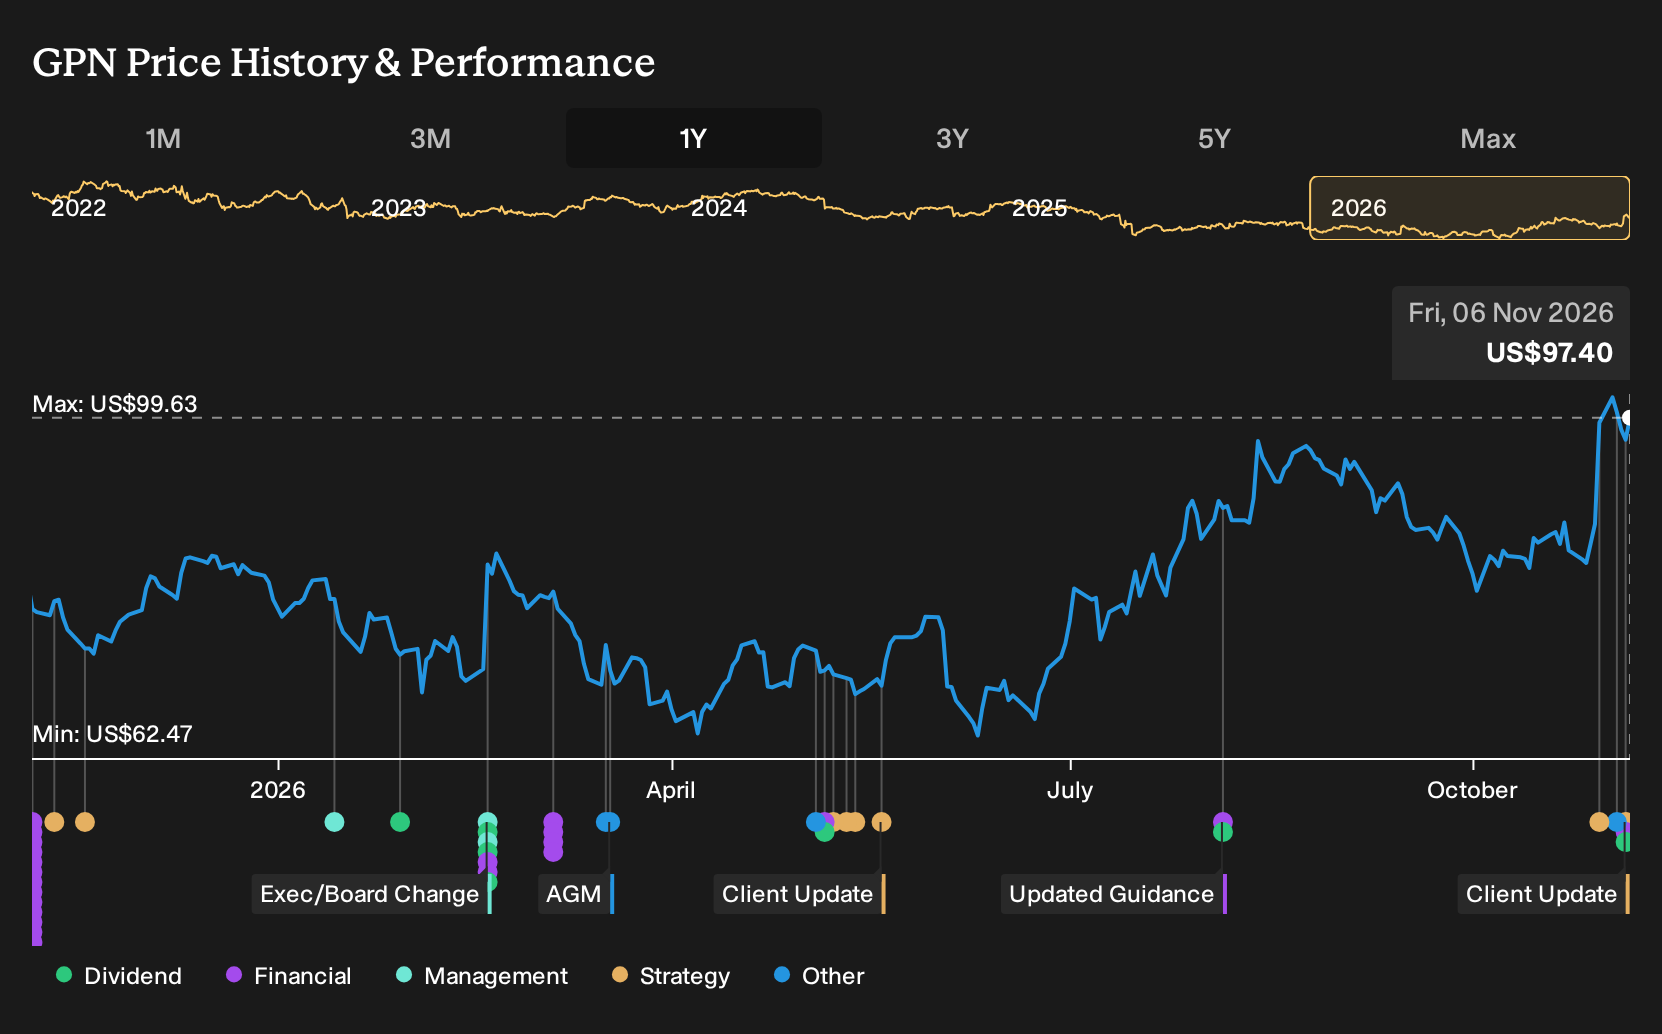
- Global Payments reported third quarter results on 5 November 2026 with adjusted earnings above analyst expectations and confirmed a multi year merchant services partnership with NASCAR, covering 12 racetracks across the United States.
- The firm paired stronger adjusted profitability with a new high profile sports venue client win, giving investors a clearer view of how its payment platforms are used in live ticketing and event operations.
- We will now look at how Global Payments' investment narrative could be influenced by its NASCAR merchant services win and earnings surprise.
Scan how Global Payments’ NASCAR deal fits into a wider venue and ticketing story by lining it up against 42 power grid technology and infrastructure stocks powering big, transaction heavy infrastructure plays.
Global Payments Investment Narrative Recap
To own Global Payments today, you need to believe the Worldpay integration, AI driven tools and venue relationships like NASCAR can turn solid transaction volume into cleaner earnings and stronger cash generation. The latest quarter shows adjusted profitability holding up, even as reported net income and margins are pressured by one off items and travel related softness.
The near term swing factor is execution on cost and revenue synergies while maintaining resilience in airline and travel exposed volumes. The biggest risk sits in integration and financial complexity, including interest coverage and one off charges. The NASCAR win helps the story, but does not materially change those core execution questions.
The NASCAR merchant services agreement feels most relevant here. It gives Global Payments a visible, transaction heavy proving ground for Genius POS, commerce software and AI driven tools such as Revenue Boost and FraudSight. Fans see faster, more flexible ticket payments. NASCAR gains clearer data on activity and payment performance across 12 large racetracks.
For investors, the interest is less about branding and more about operational proof points. A successful rollout can support the potential catalyst of higher margin, software led revenue and better free cash flow conversion, while still leaving the main risks intact. Integration work, regulatory costs and travel exposed clients remain the key variables to track after this deal.
Global Payments' narrative projects US$13.9b revenue and US$2.1b earnings by 2029. This assumes 10.8% yearly revenue growth and an earnings increase of about US$1.6b from US$494.2m today.
Discover how Global Payments' fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view zooms in on the risk that Global Payments fails to convert big venue wins into the margin gains analysts once pencilled in. The most pessimistic forecasts before this NASCAR news were for US$13.5b revenue and about US$1.1b earnings by 2029. That is far below consensus, which shows how wide opinion runs and why it can be useful to explore several competing narratives before deciding how this new partnership might reshape expectations.
Explore 3 other Global Payments fair value estimates, including one that suggests it could be worth just $105.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Global Payments research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Global Payments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Global Payments' overall financial health at a glance.
Looking For More Investment Ideas Beyond Global Payments?
Once you have formed a view on Global Payments, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If capital preservation is high on your list, check out companies that score well on balance sheet strength and fundamentals with this list of solid balance sheet and fundamentals (24 results).
- For readers focused on value, line up businesses trading below estimated worth and supported by quality metrics through this 39 high quality undervalued stocks.
- Income orientated investors can scan for reliable cash distributions and higher yields by using this 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com