
Should Dividend Hike Require Action From Kite Realty Group Trust Stock Investors?
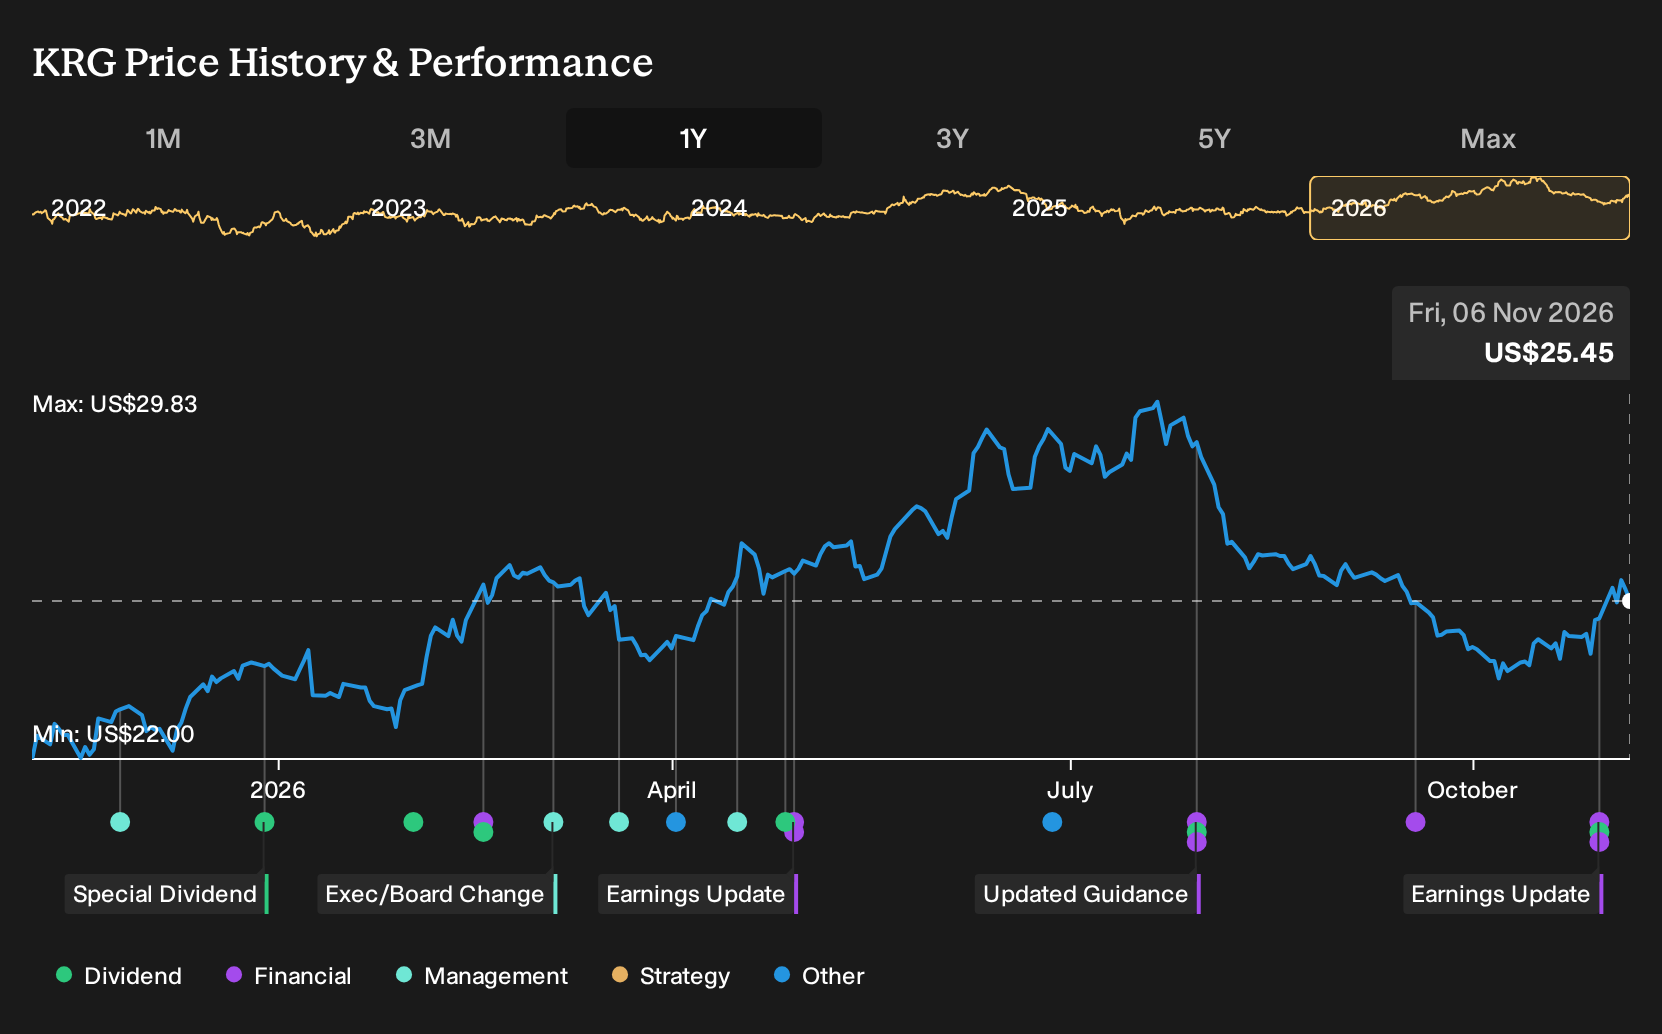
- Kite Realty Group Trust reported third quarter 2026 revenue of US$190.28 million with a net loss of US$13.3 million, reaffirmed full-year 2026 net income guidance of US$0.88 to US$0.92 per diluted share, and approved a fourth-quarter dividend of US$0.29 per share that brought 2026 dividends to US$1.16 per share.
- The 5.5% year-over-year increase in the annual dividend reflects management’s view of Kite Realty Group Trust’s cash generation despite lower year-to-date revenue compared with the prior period.
- This article examines how Kite Realty Group Trust’s higher 2026 dividend affects the existing investment narrative around cash flow durability.
Compare Kite Realty Group Trust’s income guidance and higher payout with a curated 8 dividend fortresses that also relies on consistent cash generation.
Kite Realty Group Trust Investment Narrative Recap
To own Kite Realty Group Trust, you need to believe the open air shopping center model in Sunbelt and suburban markets can keep producing consistent rent, even as some anchor tenants struggle. The recent dividend increase and reaffirmed 2026 income guidance point to confidence in cash generation, although third quarter revenue pressure and a net loss keep execution firmly in focus.
In the short term, the key swing factor is how quickly vacant space is leased and rent actually starts, given the usual 12 to 18 month lag between signing and commencement. The biggest risk is that tenant distress and interest costs offset leasing progress, which makes the latest update helpful context but not a game changer on its own.
The reaffirmed 2026 net income outlook of US$0.88 to US$0.92 per diluted share is the clearest operational signal in this batch of news. It effectively links the higher dividend to an earnings range that already reflects factors like interest expense, leasing delays and known tenant issues, which gives you a reference point to judge how stretched or conservative the payout looks.
For potential catalysts, that guidance keeps attention on rent commencements from leases already signed and any change in occupancy as backfilling progresses. On the risk side, interest payments are described as not well covered by earnings and funding relies on borrowing, so your view on Kite Realty Group Trust will likely hinge on how comfortably cash flow meets both debt service and this higher dividend over the next few reporting periods.
Kite Realty Group Trust is currently modeled by analysts to reach US$857.4 million in revenue and US$166.0 million in earnings by 2029. That profile assumes 2.0% yearly revenue growth and an earnings decline of about US$171.3 million from US$337.3 million today.
Uncover how Kite Realty Group Trust's fair value indicates a 14% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$29 and about US$36.87, which shows how widely opinions can differ even in a small sample. When you set those crowd forecasts against the higher 2026 dividend, as well as the ongoing leasing and interest cost risks, you are pushed to weigh several contrasting viewpoints before judging Kite Realty Group Trust’s performance path.
Explore another Kite Realty Group Trust fair value estimate, including one that suggests as much as 45% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kite Realty Group Trust research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kite Realty Group Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Kite Realty Group Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kite Realty Group Trust?
If Kite Realty Group Trust has you thinking harder about income, valuation and balance sheet strength, it can help to line it up against a wider field of companies that share similar traits.
- For yield hunters who still care about resilience, compare Kite Realty Group Trust with other income plays using a curated 8 dividend fortresses that focus on robust payouts backed by ongoing cash generation.
- If value is the priority, put this REIT alongside companies that screen as potentially underpriced by checking a broader 39 high quality undervalued stocks that blend quality fundamentals with discounted valuations.
- When capital preservation sits higher on your checklist than aggressive upside, weigh Kite Realty Group Trust next to a 29 resilient stocks with low risk scores that tilt toward steadier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com