
How Investors May Respond To Materion (MTRN) Record Earnings Outlook Raised
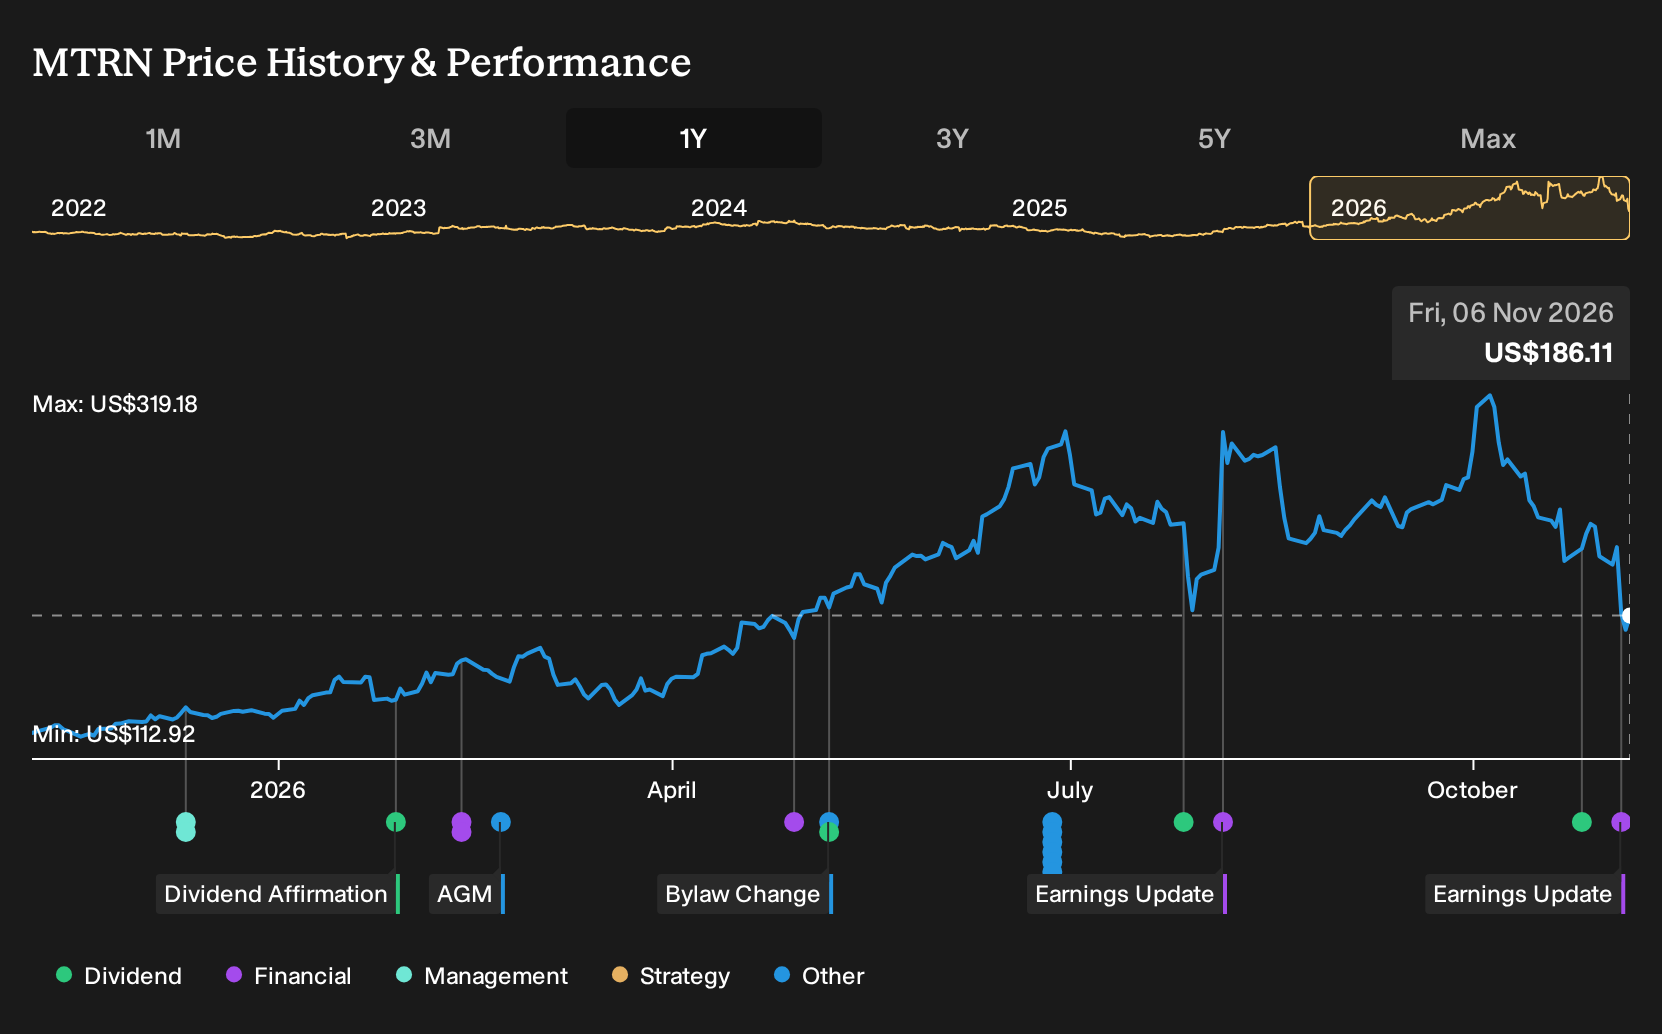
- Materion reported record third quarter and nine month 2026 results, with higher sales, net income and earnings per share, and the board affirmed a fourth quarter dividend of US$0.145 per share.
- The combination of record incoming orders, record backlog and customer or contractor funded capacity projects signals that Materion is leaning on externally supported growth rather than stretching its own balance sheet.
- Attention now turns to how Materion's record backlog and upgraded full year earnings outlook may reshape the broader investment narrative from this point.
Scan how Materion's record orders and capital efficient expansion compare with peers by jumping into a curated list of 33 best rare earth metal stocks across the materials space.
Materion Investment Narrative Recap
To stay invested in Materion, you need to be comfortable with a story built on converting its record backlog in semiconductors, aerospace and defense into high value added sales while keeping margins firm. The latest quarter supports that belief. Sales reached US$567.29 million, net income was US$38.33 million and diluted EPS from continuing operations was US$1.81.
The key near term swing factor remains order flow and program timing in those AI linked and defense heavy end markets. That is also the biggest risk. Any slowdown in orders or delays on large customer programs would quickly matter more than the headline beat or upgraded full year earnings outlook.
The clearest data point to focus on here is Materion's record third quarter and nine month 2026 earnings report. Over the first three quarters, sales were US$1,731.02 million, net income was US$96.46 million and diluted EPS from continuing operations reached US$4.57, all ahead of the prior year period.
This level of earnings power, combined with customer and contractor funded capacity projects, gives Materion more room to pursue growth without relying as heavily on its own balance sheet. The trade off is sharper exposure to customer concentration. If large defense, space or data center clients change procurement plans, both that backlog and the upgraded outlook could come under pressure.
Materion's current analyst narrative points to forecast revenue of US$3.0b and earnings of US$296.8 million by 2029, based on revenue growth of 12.4% per year and an increase in earnings from US$90.1 million today to US$296.8 million, a little more than 3x higher.
Uncover why Materion's fair value points to a 63% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate view focuses on Materion’s capital spending risk rather than its AI and defense pipeline. The most optimistic analysts were already estimating revenue of about US$3.1b and earnings of roughly US$310.1 million by 2029. You can treat those pre-news assumptions as a ceiling and then ask how this earnings surprise might shift them.
Explore 2 other Materion fair value estimates, including one that suggests as much as 95% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Materion research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Materion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Materion's overall financial health at a glance.
Looking For More Investment Ideas Beyond Materion?
If Materion has sharpened your focus on where capital might work harder, broaden the lens and use the Simply Wall St Screener to line up other candidates that fit your approach, from resilience to income to long term growth potential.
- If capital preservation sits high on your list, filter for companies with steadier profiles by scanning a curated 29 resilient stocks with low risk scores that score well on resilience metrics.
- For investors who care most about balance sheet strength and business quality, start with a list of solid balance sheet and fundamentals (24 results) and see which stocks combine debt discipline with healthy fundamentals.
- If you prefer to hunt for businesses that the market may not be fully pricing yet but that still show solid fundamentals, then work through a 19 high quality undiscovered gems that highlights quieter opportunities outside the usual headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com