
Did Guidance Cut Just Shift Ashland (ASH) Investment Narrative?
- Ashland reported fourth quarter 2026 sales of US$498 million and a net loss of US$16 million, while full year sales reached US$1.863 billion with net income of US$4 million.
- The updated fiscal 2027 outlook pairs expected sales of US$1.905 billion to US$1.975 billion with pressure on adjusted EBITDA from operational issues and currency headwinds.
- The focus now turns to how Ashland's mixed 2026 results and cautious 2027 EBITDA guidance may influence the longer term investment narrative.
Scan how Ashland's margin story compares with other specialty chemicals players by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Ashland Investment Narrative Recap
To stay on board with Ashland, you need to believe that Life Sciences, Personal Care and Specialty Additives can keep carrying the mix, while operational fixes eventually show up in cleaner margins. The latest quarter delivered higher sales but a swing to a net loss, and management is signaling near term pressure on adjusted EBITDA in fiscal 2027.
The key near term catalyst is execution at problem facilities like Hopewell and across the broader manufacturing footprint. That is where any earnings improvement will start. The biggest risk is that these operational issues linger, which could hold EBITDA margins down and keep interest coverage and dividend sustainability looking tight.
The clearest operational marker for this story is Ashland’s fresh fiscal 2027 outlook. Management is calling for US$1.905b to US$1.975b in sales, paired with adjusted EBITDA guidance of US$405 million to US$435 million. That framing matters more than the quarterly earnings volatility because it sets the bar for what “good enough” execution looks like.
For you, the question is whether that range feels achievable given recent hiccups at sites like Hopewell and weaker productivity in Specialty Additives. Progress on throughput, cost savings and currency management would support that guide. A miss against those EBITDA targets would indicate that operational risk remains the dominant part of the Ashland story.
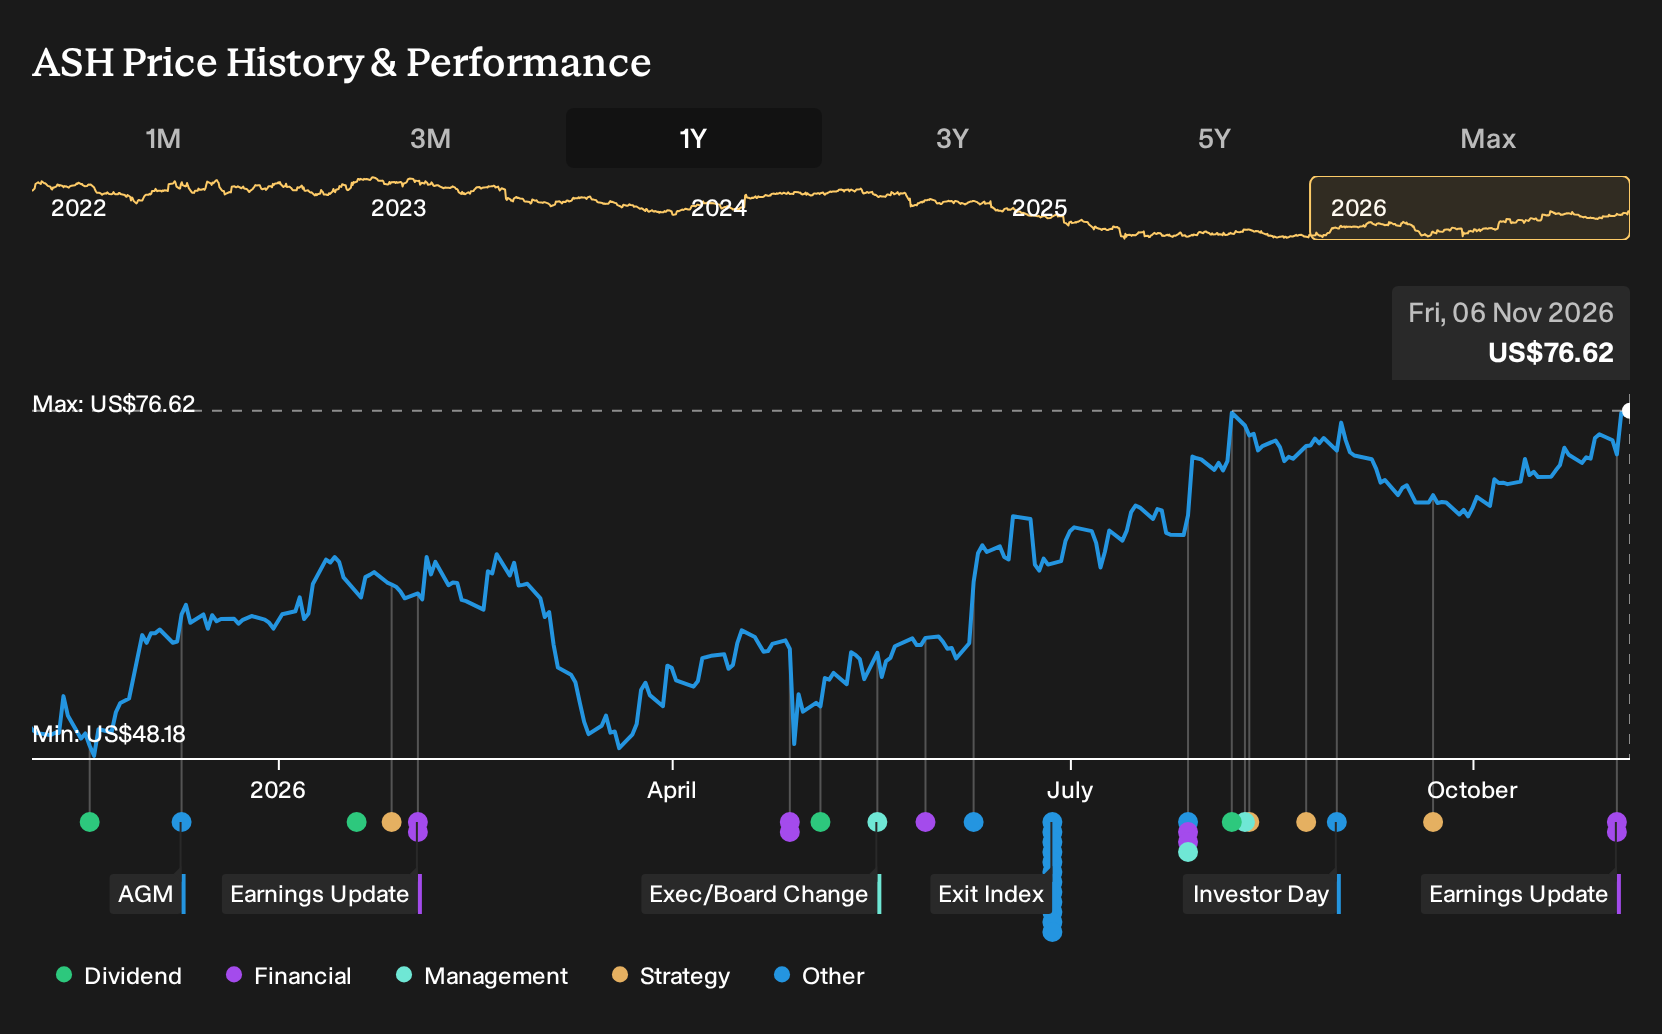
Ashland's current analyst narrative points to revenues of US$2.0b and earnings of US$195.1 million by 2029, tied to a forecast revenue growth rate of 3.2% a year, and an earnings increase of about US$120 million from earnings today of US$75.0 million.
Uncover why Ashland's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on margins. The most cautious analysts were already baking in tighter profitability before this Ashland update, even while assuming revenue reaches about US$2.0b and earnings of roughly US$216.7 million by 2029. That is a more muted story than the baseline. It shows how sharply opinions can differ and invites you to compare both sets of expectations as this new information beds in.
Explore another Ashland fair value estimate, including one that suggests it could be worth just $80.18.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ashland research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ashland. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ashland's overall financial health at a glance.
Looking for more Ashland investment ideas?
If the Ashland story has sharpened your thinking and you want to widen your opportunity set, the Simply Wall St Screener can help you quickly sort through companies that fit different risk and return profiles.
- For investors who care most about quality at a reasonable price, start with a curated group of companies trading below estimated value through the 39 high quality undervalued stocks.
- If resilience matters more than excitement, filter for businesses with steadier profiles by running the 29 resilient stocks with low risk scores.
- For those hunting for overlooked stories with strong fundamentals, expand your watchlist using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com