
Will Flat Revenue Guidance Change Match Group (MTCH) Narrative
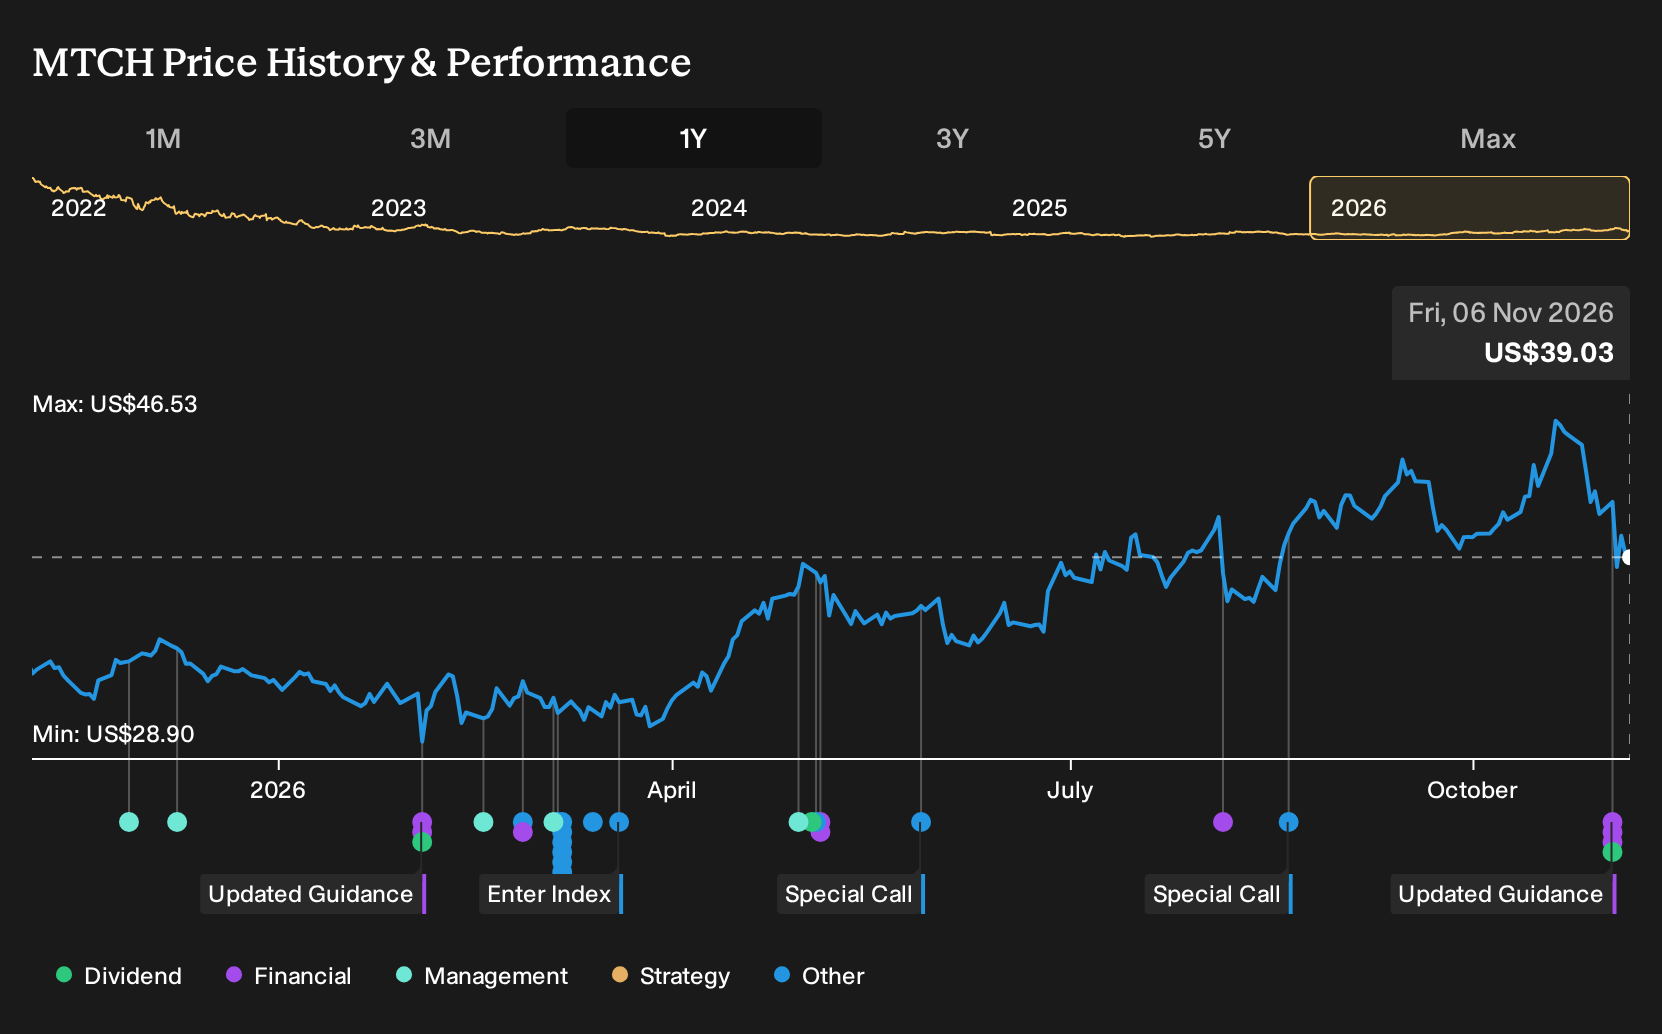
- Match Group reported third quarter 2026 sales of US$891.23 million with net income of US$174.36 million, issued updated guidance that points to flat full year revenue, and declared a US$0.20 per share cash dividend payable in January 2027.
- The mix of softer top line trends alongside higher earnings per share and a new dividend highlights management's focus on profitability and direct cash returns, even as revenue guidance points to flat or slightly weaker demand.
- We will now see how Match Group's investment narrative is affected by stronger earnings alongside flat revenue guidance and a new dividend.
Compare Match Group's flat revenue guidance and new dividend focus with other companies prioritizing resilient balance sheets and dependable fundamentals by scanning our curated list of solid balance sheet and fundamentals (24 results).
Match Group Investment Narrative Recap
For a shareholder in Match Group, the big belief is that Tinder, Hinge and the broader portfolio can keep monetising online dating even if headline revenue stays flat at around current levels. The latest guidance, which points to full year revenue that is flat year over year and a fourth quarter outlook that is down 1% to flat, reinforces that this is an efficiency and margin story in the near term.
The main short term catalyst is whether product work on engagement, AI supported development and alternative payments can stabilise payer trends while protecting a roughly 20% net income margin. The biggest risk is that competitive pressure and ongoing drag from weaker brands keep usage soft, which would limit how much earnings can offset a flat top line.
The most relevant move right now is Match Group's updated outlook that pairs flat full year revenue with higher net income and earnings per share. Third quarter 2026 sales of US$891.23 million compared with US$914.28 million a year ago, yet net income rose to US$174.36 million from US$160.75 million, with basic EPS from continuing operations at US$0.76.
Management now expects fourth quarter revenue of US$865 million to US$875 million and net income attributable to shareholders of US$172.5 million to US$177.5 million, which implies a 20% net income margin at the midpoint. For you, the link to catalysts is clear. Execution on product, payer monetisation and cost discipline needs to keep that profitability resilient while Match Group works through usage headwinds and portfolio clean up.
Match Group's current analyst framework points to revenues of US$4.0b and earnings of US$860.9m by 2029, based on expectations of 4.2% yearly top line growth. That profit figure represents an increase of about US$153m from earnings today of US$707.8m.
Uncover how Match Group's fair value indicates a 10% potential upside to its current price before other investors notice that the gap could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into Match Group’s AI and event features as a future catalyst. The most optimistic analysts were already baking in about 4.6% annual revenue growth and earnings of roughly US$836.7 million by 2029. Those projections came before this flat revenue guidance and new dividend, so you should expect opinions to shift and consider how that might reshape your own thesis.
Explore 5 other Match Group fair value estimates, including one that suggests potential upside of as much as 105% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Match Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Match Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Match Group's overall financial health at a glance.
Looking for more Match Group sized investment ideas?
Once you have tested your view on Match Group, it helps to line it up against other opportunities that match your risk tolerance, time horizon and income needs. The Simply Wall St Screener can help you quickly filter for businesses that fit the profile you care about most.
- If you want potential bargains with solid fundamentals, start by scanning a focused set of quality candidates using the 39 high quality undervalued stocks.
- For investors who care more about resilience and capital preservation, narrow your watchlist to companies that score well on financial strength filters by using the 29 resilient stocks with low risk scores.
- If reliable income is your priority, concentrate on businesses offering higher yields and consistent payouts with the help of the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com