
Should AI Partnership Require Action From Estée Lauder (EL) Investors?
- Estée Lauder Companies recently outlined its Beauty Reimagined plan through fiscal 2030 and expanded a partnership with Microsoft to build an AI enabled, data rich operating ecosystem across brands and regions.
- The combination of long dated financial targets and investment in a unified data platform highlights how Estée Lauder Companies is using technology to tighten execution, manage costs and sharpen consumer targeting across its portfolio.
- Investors can now observe how Estée Lauder Companies' investment narrative may be influenced by the expanded Microsoft AI and data partnership.
Scan how Estée Lauder Companies’ AI push and refreshed guidance compare with peers by reviewing hand picked 19 high quality undiscovered gems in beauty and consumer brands that are leaning into data driven execution.
Estée Lauder Companies Investment Narrative Recap
For a shareholder in Estée Lauder Companies, the core belief is that the Profit Recovery and Growth Plan, the One ELC model and the Beauty Reimagined strategy can keep lifting efficiency without dulling the brands. The raised fiscal 2027 sales and earnings guidance points in that direction, while the quarterly dividend of US$0.35 per share underlines a commitment to return some cash.
The key near-term catalyst is execution on margin improvement after a year that included large one-off charges and a return to profitability. The biggest risk still sits in operational disruption from restructuring or any renewed weakness in travel retail, which remains an important profit pool despite the reset.
The most relevant update here is the raised fiscal 2027 outlook that followed the first-quarter print. Management now guides reported net sales growth of 5.0% to 6.5% and diluted EPS of US$2.85 to US$3.18, compared with prior ranges of 3% to 5% and US$2.52 to US$2.85 respectively.
Those targets sit alongside first-quarter revenue of US$3,715 million and net income of US$233 million, with basic and diluted EPS of US$0.64 from continuing operations. For you as an investor, the question is whether Estée Lauder Companies can keep turning its AI investments and restructuring into cleaner earnings while managing debt levels and travel retail risk.
Estée Lauder Companies' current revenue plan implies US$17.4b in revenue and US$1.6b in earnings by 2029. Analysts are building this on 4.4% yearly revenue growth and an earnings increase of about US$1.2b from US$368.0m today.
Uncover why Estée Lauder Companies' fair value indicates a 4% potential upside to its current price that may not last much longer.
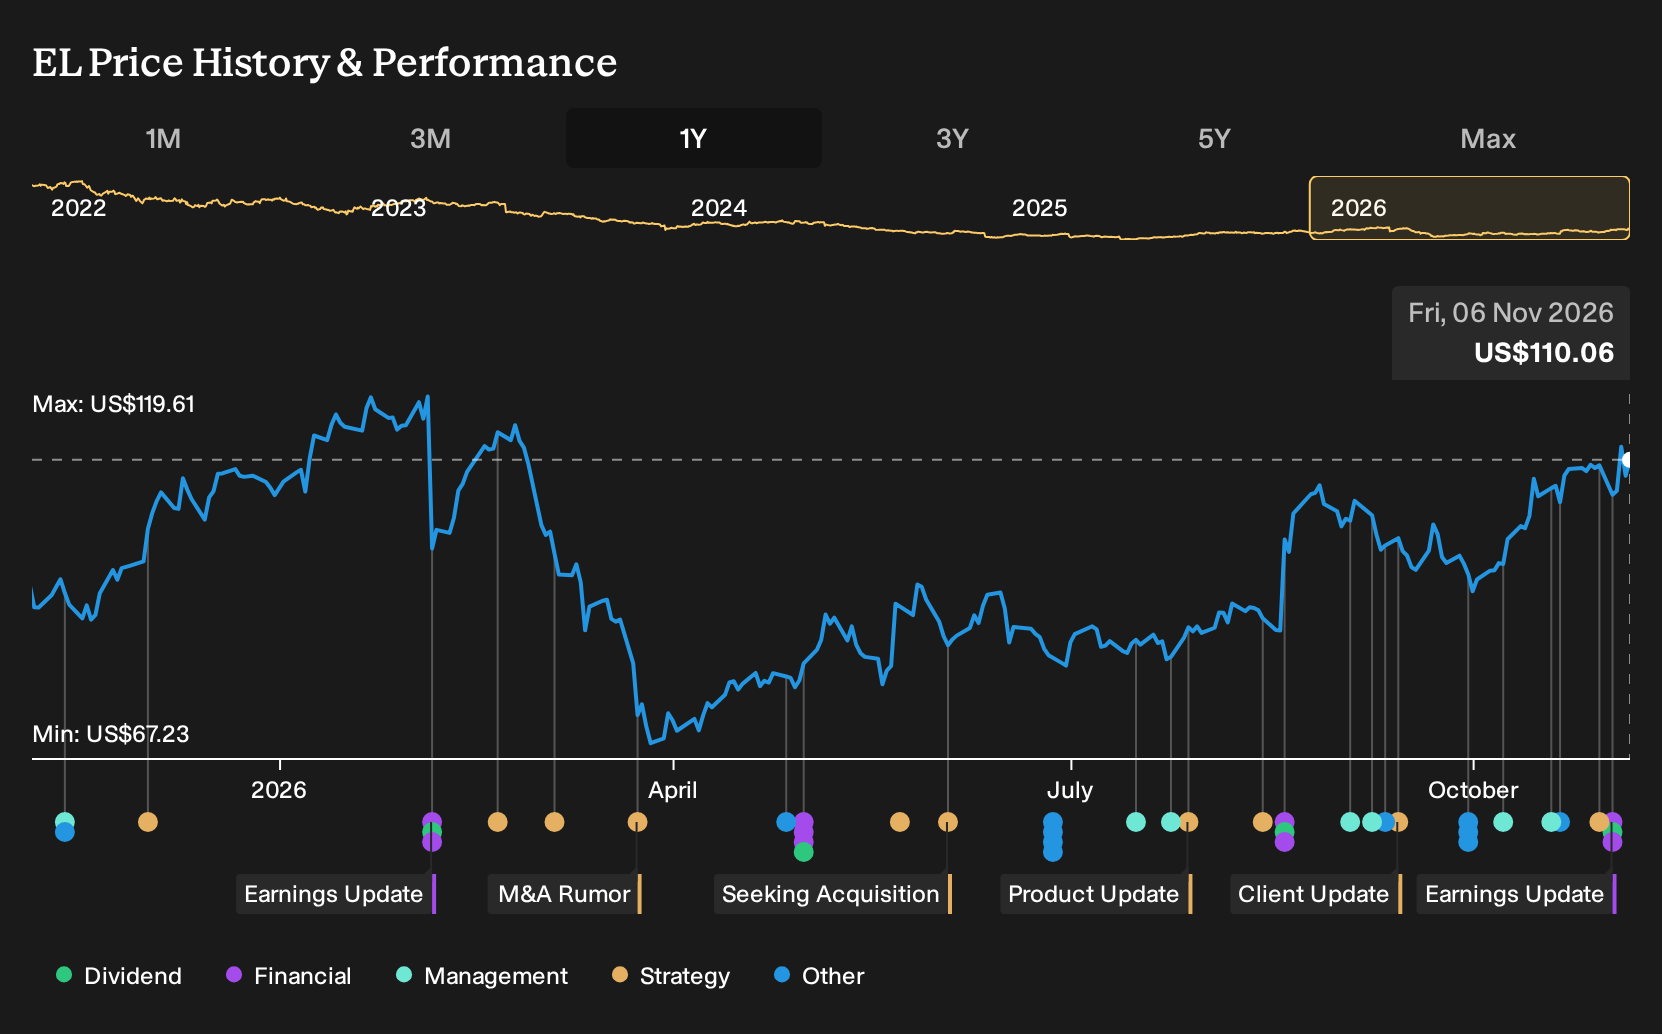
Exploring Other Perspectives
One alternate view on Estée Lauder Companies focuses less on AI upside and more on cash flow strain. The most cautious analysts were working off revenue expectations of about US$17.0b and earnings of roughly US$1.5b by 2029, paired with concerns about cash from operations trending toward US$1.3b to US$1.4b. That group presents a more conservative story than the baseline. The fresh dividend affirmation and raised guidance may be a useful trigger for you to recheck both narratives and decide which assumptions feel closer to your own.
Explore 5 other Estée Lauder Companies fair value estimates, including one that suggests as much as 20% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own instincts.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Estée Lauder Companies?
If the Estée Lauder Companies story has you thinking about where else disciplined execution and solid fundamentals might show up, it can help to widen the lens and compare across a broader watchlist.
- For investors who care most about valuation support and cash backed quality, scan a curated set of 39 high quality undervalued stocks that may warrant a closer look beside Estée Lauder Companies.
- If capital preservation sits high on your checklist, focus on resilience by reviewing a 29 resilient stocks with low risk scores that may better fit a steadier risk profile.
- When balance sheet strength is non negotiable, filter for companies with robust finances using a targeted list of solid balance sheet and fundamentals (24 results) that can sit alongside Estée Lauder Companies in your research pipeline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com