
Record Revenue And Reaffirmed Guidance Could Reshape The Astrana Health Stock Story
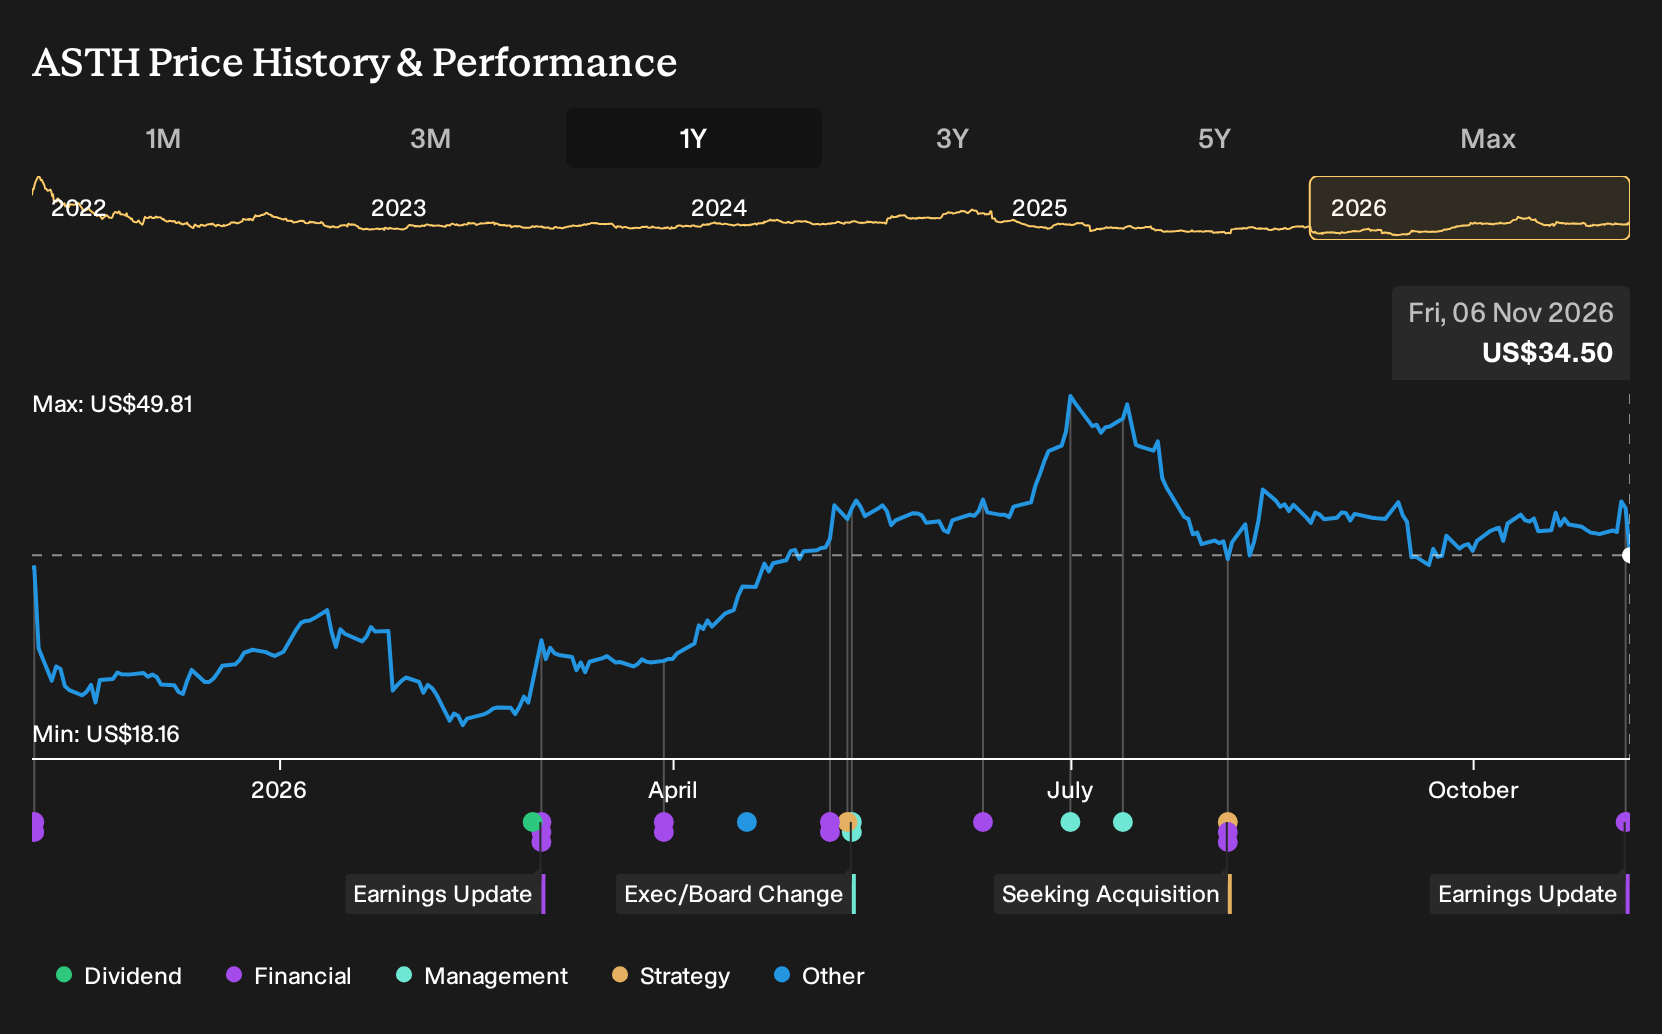
- Astrana Health reported Q3 2026 net income of US$12.95 million and earnings of US$0.26 per share, alongside record quarterly revenue of US$1.02 billion and adjusted EBITDA of US$77.2 million, while reaffirming its 2026 full year guidance range.
- The business is leaning further into Medicare Advantage and full risk contracts, using its AI powered operating platform and tuck in acquisitions to offset pressure from Medicaid and Exchange attrition that management expects to affect membership and EBITDA in 2027.
- We will now look at how Astrana Health's investment narrative could be affected by record Q3 revenue and reaffirmed full year guidance.
Compare Astrana Health's earnings story with other healthcare operators by scanning 35 healthcare AI stocks that are also leaning into data driven care and AI powered platforms.
Astrana Health Investment Narrative Recap
Astrana Health asks you to believe that value based care, full risk contracts and an AI powered platform can support earnings quality even as payer mix shifts. The Q3 print, with US$1.02b in revenue, US$77.2m in adjusted EBITDA and US$0.26 in EPS, broadly fits that story. Record revenue and reaffirmed 2026 guidance keep the near term focus on execution, not repair.
The key near term catalyst is whether Medicare Advantage and ACO growth can offset the Medicaid and Exchange attrition that management expects to affect 2027 EBITDA. That risk looks very real. Q3 results do not remove it, but they show the firm entering this reset with higher profitability and a larger full risk footprint.
The most relevant data point for that thesis is Q3 2026 net income and earnings for the quarter and year to date. Astrana Health reported quarterly net income of US$12.95m, or US$0.26 per share, and nine month net income of US$47.13m, or about US$0.96 in basic EPS from continuing operations.
Those figures give you a clearer view of how the operating model is performing while the payer mix is already shifting. They also frame the interest coverage and leverage discussion, since interest payments are not yet comfortably covered by earnings. For investors watching catalysts, execution on full risk contracts and disciplined capital use now sit under a brighter spotlight.
Astrana Health's narrative projects US$5.0b revenue and US$146.2m earnings by 2029. That profile assumes 9.0% yearly revenue growth and an earnings increase of about US$105.7m from US$40.5m today.
Uncover why Astrana Health's fair value indicates a 50% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Astrana Health, the most optimistic analysts were banking on operating leverage as the real catalyst. They were modeling revenue of about US$5.5b and earnings of roughly US$171.5m by 2029, well above consensus. Those projections were set before this Q3 report, so views like that may evolve as new information lands.
Explore 3 other Astrana Health fair value estimates, including one that suggests potential upside of up to 298% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Astrana Health research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astrana Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which allows you to evaluate Astrana Health's overall financial health at a glance.
Looking For More Astrana Health Style Ideas?
If Astrana Health's mix of value based care and AI supported operations has caught your attention, it can help to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a structured way to do that, so you can compare this stock with baskets of companies that share the qualities you care about most.
- If capital preservation and steadier profiles are a priority, start with a curated group of resilient businesses via the 29 resilient stocks with low risk scores.
- If balance sheet strength matters more than headlines, scan a list of solid balance sheet and fundamentals (24 results) to see which companies pair cleaner finances with durable fundamentals.
- If you are hunting for mispriced opportunities, broaden your watchlist with a 19 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com