
Is Waste Management (WM) Undervalued On Strong Earnings And High End Revenue Guidance?
Why Waste Management’s Latest Earnings Matter For Investors
Waste Management (WM) just posted third quarter and year to date results that show higher sales, net income, and earnings per share compared with the same periods last year, alongside guidance pointing to revenue near the top of its 2026 range.
Waste Management’s 1 month share price return of 13.08%, alongside an 8.18% year to date share price gain and 18.96% 1 year total shareholder return, points to building momentum. The latest earnings beat, raised revenue outlook, and ongoing buybacks are likely shaping how investors are reassessing both growth potential and risk around the US$236.26 stock.
Scan how Waste Management’s momentum compares with a hand-picked 39 high quality undervalued stocks that combines strong fundamentals with pricing that may still lag behind recent earnings strength.
Waste Management now trades close to analyst targets and a modest intrinsic value premium, after a sharp move higher. Is that pricing already fair, or does the recent jump still leave a gap worth examining?
Most Popular Narrative: 7% Undervalued
Waste Management’s most followed valuation story pins fair value at $253.84 against the latest $236.26 close, which paints a picture of a solid franchise priced slightly below its modeled cash flows under a 7.31% discount rate.
The main thing that has to go right is that Waste Management turns its large investments in healthcare solutions, recycling automation and renewable natural gas into sustained cross sell, synergy capture and free cash flow conversion now that major capex is largely complete.
The current valuation implies the share price does not fully reflect a business that is growing operating EBITDA, expanding margins, lifting free cash flow conversion toward the high 40s% to low 50s% range and benefiting from scarce disposal and energy assets.
See why 99 investors see Waste Management as 7% undervalued.
Result: Fair Value of $253.84 (UNDERVALUED)
Still, the narrative around Waste Management could shift if renewable natural gas tax credits roll off, or if Stericycle synergies and healthcare margins fall short of expectations.
Find out about the key risks to this Waste Management narrative.
Another View On Waste Management’s Valuation
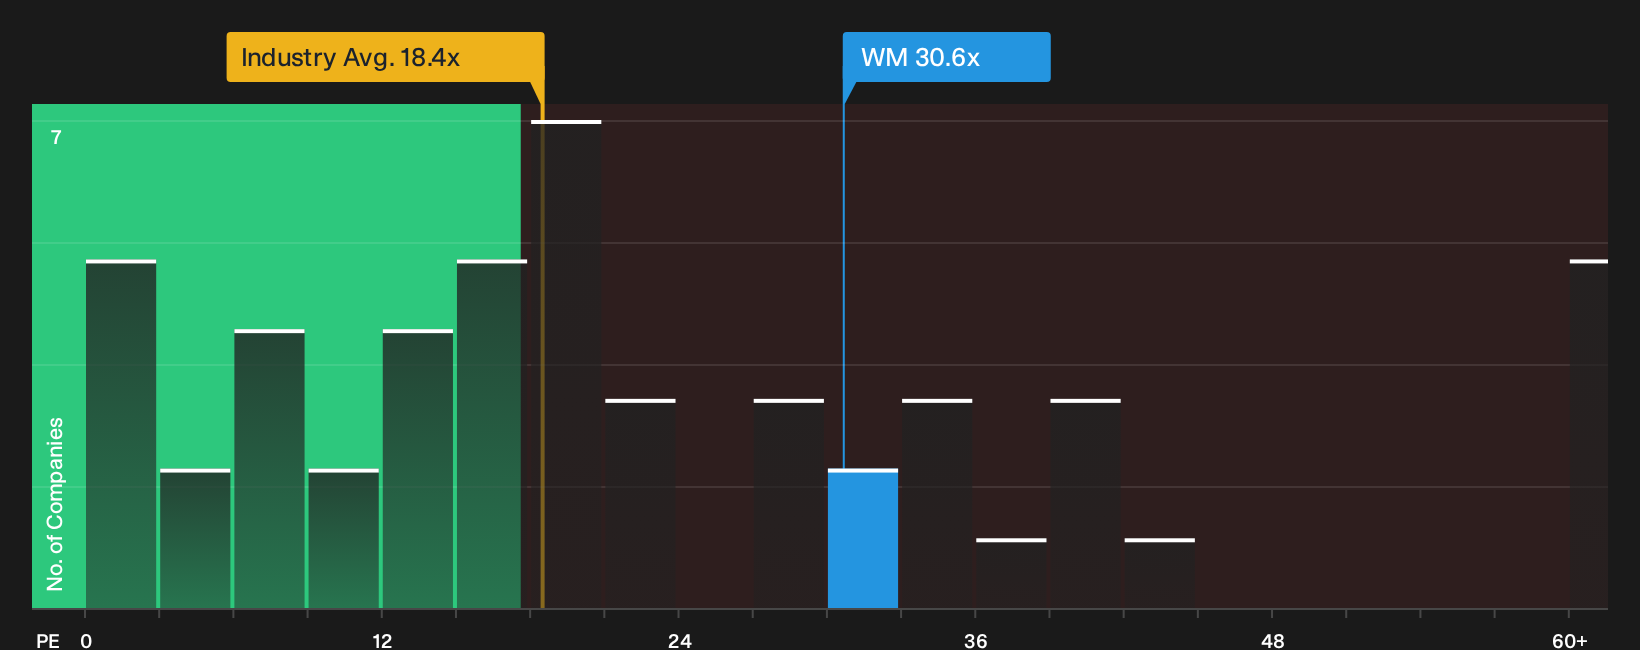
The first story frames Waste Management as modestly undervalued on future cash flows. A simple P/E check tells a tougher story. WM trades at 30.6x earnings compared with 18.4x for the wider Commercial Services group and 34.6x for peers, and sits almost exactly on a 30.7x fair ratio. That combination points to limited valuation slack if expectations slip, or room for re rating if earnings keep pace with richer peers. Which side of that trade off do you think is more realistic?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Waste Management’s valuation narrative are clear, so move fast, look through the numbers for yourself, and weigh both sides with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Waste Management?
If you stop with Waste Management, you only see part of the opportunity set. Cast the net wider now and let the data surface fresh candidates.
- Target dependable income by reviewing companies in the 8 dividend fortresses that focus on combining strong yields with staying power.
- Hunt for mispriced strength through the 19 high quality undiscovered gems that highlights quality businesses the crowd may be ignoring.
- Dial down portfolio stress and concentrate on resilience with a curated 29 resilient stocks with low risk scores built around sturdier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com