
Arcus Biosciences (RCUS) Could Be 55% Undervalued As Third Quarter Losses Land
Arcus Biosciences (RCUS) just laid out its third quarter scorecard, reporting revenue of US$9 million and a net loss of US$128 million. The results give investors fresh data on the company’s cancer drug pipeline efforts.
Arcus Biosciences shares closed at US$18.28 on 4 November, with a 1 day share price return of 3.34% and a 7 day gain of 0.49%. However, the 30 day share price performance is down 25.45% and the 90 day move is lower by 36.13% as investors absorb the third quarter revenue decline and continued losses. That short term weakness contrasts with a relatively modest 1 year total shareholder return decline of 5.33% and a 3 year total shareholder return gain of 35.01%, suggesting sentiment has cooled recently after a stronger multi year run.
Spot other cancer and biotech stocks that may be setting up for their next move by scanning our hand picked 19 high quality undiscovered gems alongside Arcus Biosciences today.After a sharp pullback on weaker recent revenue and ongoing losses, Arcus Biosciences now trades at a level where opinions split. Is most of the rerating already done, or is the real upside still ahead?
Most Popular Narrative: 55% Undervalued
On the most followed view, Arcus Biosciences screens as undervalued, with a fair value of $41 against a last close of $18.28, and that gap leans heavily on the kidney cancer program actually delivering.
Arcus Biosciences is prioritizing the launch of its late-stage development program for the HIF-2 alpha inhibitor casdatifan, and new ARC-20 data showing deep and durable HIF-2α inhibition with prolonged progression free and overall survival in late-line RCC reinforces the view that successful registrational trials could expand future revenue in RCC.
The company plans to present further data from ongoing casdatifan studies, including ARC-20 cohorts where biomarker reductions in erythropoietin and PAI-1 track with higher response rates and longer progression free and overall survival. This could support future revenue growth if this biomarker framework translates into label and uptake advantages.
See why 10 investors see Arcus Biosciences as 55% undervalued.
Result: Fair Value of $41 (UNDERVALUED)
Still, the Arcus Biosciences story can break if casdatifan’s anemia and hypoxia concerns curb real world use, or if regulatory setbacks drag out approvals.
Find out about the key risks to this Arcus Biosciences narrative.
Another View On Arcus Biosciences Valuation
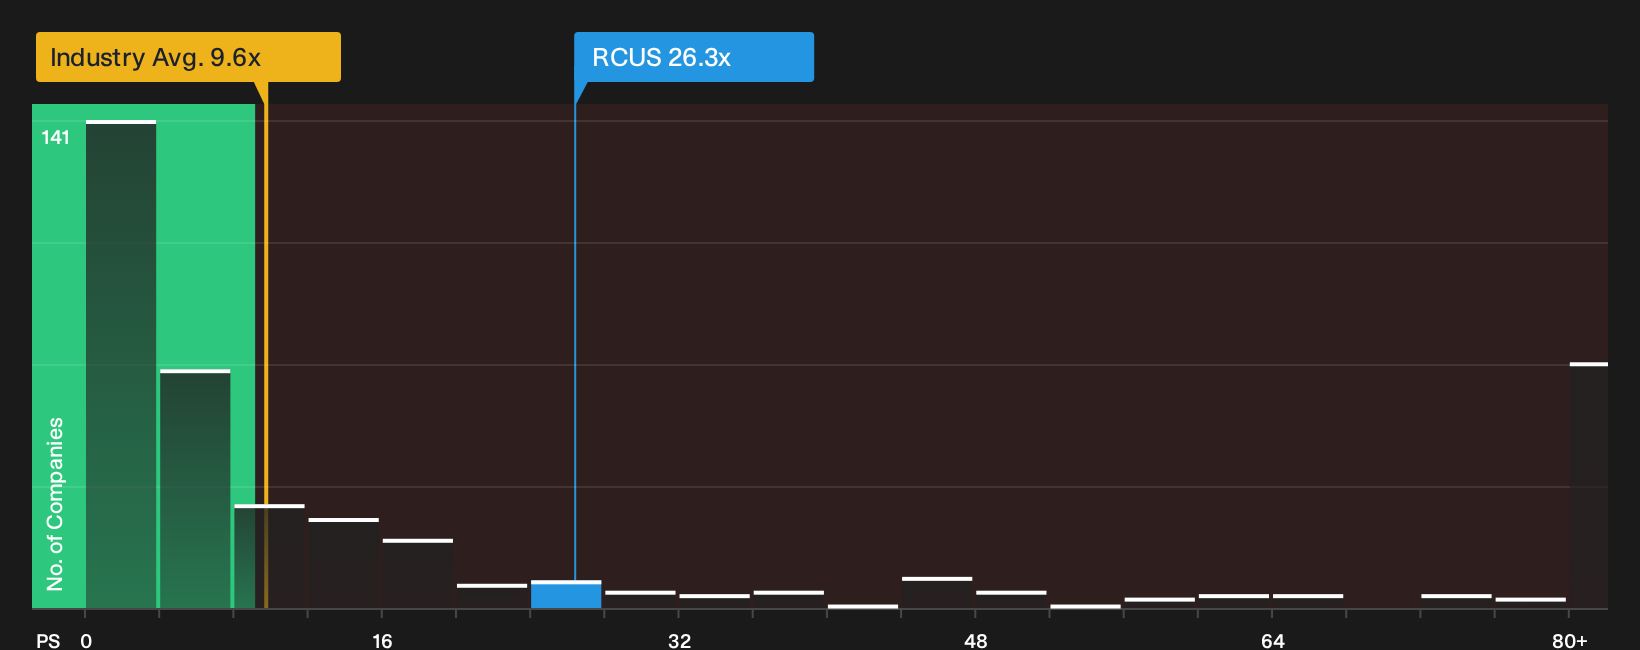
The first story around Arcus Biosciences leans on future cash flows and analyst targets that point to upside. A different lens comes from today’s sales multiple. RCUS trades on a P/S of 26.3x, which is far above the US Biotechs industry at 10.1x and its fair ratio estimate of 0.1x. That gap points to real valuation risk if sentiment or trial expectations cool.
Before leaning on any single approach, it is worth stress testing how this rich P/S, the peer gap, and the fair ratio might compress if the casdatifan narrative wobbles, or stretch further if the drug delivers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the Arcus Biosciences story so far, with both concern and optimism in play, and want to cut through the noise quickly? Weigh the 2 key rewards and 2 important warning signs against your own read of the latest data and decide where you stand.
Hunting For More Investment Ideas Beyond Arcus Biosciences?
If Arcus Biosciences has you thinking about where the next opportunity could come from, do not stop with a single ticker. Use screeners to methodically surface companies that actually fit the return profile and risk level you want, instead of chasing headlines or hunches.
- Target potential mispricing in quality businesses by scanning our curated pool of 39 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Build staying power into your portfolio by focusing on companies prioritized for financial resilience and balance sheet strength using the list of solid balance sheet and fundamentals (24 results).
- Get ahead of the crowd by reviewing a carefully filtered set of 9 elite penny stocks with strong financials before they appear on most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com