
Is Core Natural Resources (CNR) Cheap Following Earnings And New Coal Contracts?
Core Natural Resources (CNR) moved into focus after its 5 November earnings update, where higher quarterly sales came alongside sharply lower net income and fresh long term coal contracts with strengthened Chinese demand.
The earnings release and new export contracts hit a stock that had been under pressure, with the 30 day share price return down 10.8% and the year to date share price return lower by 11.8%. The 5 year total shareholder return of about 235% still reflects a strong longer run, so recent momentum looks weak even as Core Natural Resources remains well ahead over a full cycle.
Pace your next move after Core Natural Resources' earnings by scanning a hand picked 39 high quality undervalued stocks that may offer a different balance of weakness in recent returns and potential long term resilience.Core Natural Resources now trades lower despite fresh contracts, a confirmed dividend and merger savings starting to show up. Does that mix still skew the risk reward toward buyers, or has the easy part of the valuation case already passed?
Most Popular Core Natural Resources Narrative: 28% Undervalued
Compared with the $79.31 close, the most followed narrative pegs Core Natural Resources at a fair value of $109.50, so the story sits well above where the market last traded and leans heavily on contracted volumes and cost savings to bridge that gap.
Execution on merger related synergies that are already tracking at more than US$160 million of annual run rate savings, together with lower guided metallurgical cash costs in 2026, positions Core to improve operating leverage and net margins if it sustains current best practice mining performance.
See why 30 investors see Core Natural Resources as 28% undervalued.
Result: Fair Value of $109.50 (UNDERVALUED)
Still, the Core Natural Resources story hinges on coal demand holding up and regulatory support persisting, since weaker volumes or tougher rules could quickly undercut that 28% undervalued thesis.
Find out about the key risks to this Core Natural Resources narrative.
Another View: Core Natural Resources Looks Expensive On Earnings
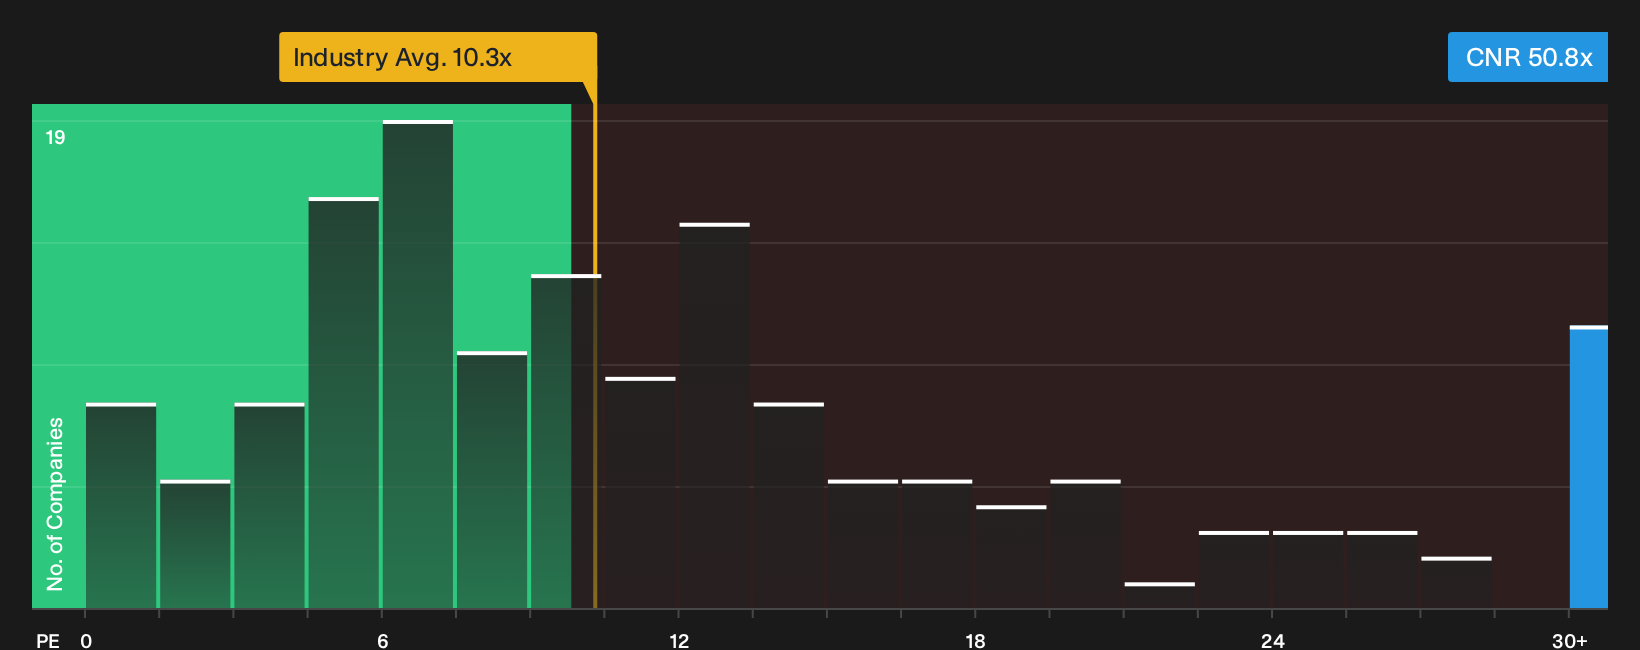
The story looks very different when you switch from cash flows to simple earnings multiples. Core Natural Resources trades on a P/E of 50.8x, while the US Oil and Gas industry sits at 11.1x and peers average 17.8x. The fair ratio points to 25.3x, so are investors paying up for growth and taking on valuation risk if sentiment cools?
To see how this earnings based view stacks up against a fuller ratios breakdown, including that fair ratio and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Core Natural Resources so far. If you want to move fast and rely on your own homework, start by weighing the 4 key rewards.
Looking for more Core Natural Resources style ideas?
If Core Natural Resources has you thinking differently about risk and reward, do not stop here. Widen your search and pressure test your next move.
- Target potential mispricing by scanning a focused group of quality companies that screens for valuation support and balance sheet strength through the 39 high quality undervalued stocks.
- Prioritise capital protection first and hunt for businesses that score well on stability and resilience using the 29 resilient stocks with low risk scores.
- Spot earlier stage opportunities with stronger fundamentals than the usual small cap crowd by working through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com