
Is Stryker (SYK) Cheap On Earnings Weakness And A Goodwill Impairment?
Stryker (SYK) has been in focus after third quarter earnings, a US$293 million goodwill impairment, and a fresh universal shelf registration that covers common stock, preferred shares, and multiple financing instruments.
The recent move in Stryker’s share price reflects how mixed these headlines feel to the market. The stock has climbed with an 11.65% 7 day share price return and an 18.33% 30 day share price return, yet it is still down 6.41% on a year to date share price basis and shows a 7.46% decline in 1 year total shareholder return. Multi year total shareholder returns of 22.67% over 3 years and 29.95% over 5 years point to a longer record that investors continue to weigh against current earnings pressure, the US$293 million goodwill impairment, manufacturing issues in Peripheral Vascular and the new universal shelf filing.
Scan beyond Stryker by comparing it with other healthcare stocks on our hand picked 35 healthcare AI stocks, which blends medical technology exposure with AI driven growth themes.
Stryker now trades close to analyst targets but sits at a deeper discount to some intrinsic value estimates. After this sharp rebound and mixed quarter, the question is where a reasonable fair value range really lands.
Most Popular Narrative: 5% Overvalued
Stryker’s share price of $325.87 sits slightly above the most followed narrative’s fair value estimate of $311.21. This frames it as quality at a mild premium rather than a clear bargain.
Stryker is my defensive-growth anchor, a high-quality medtech leader in orthopaedics, surgical equipment and MedSurg, riding the durable tailwind of an ageing population. Demographics, not hype, drive this thesis.
See why 6 investors see Stryker as 5% overvalued.
Result: Fair Value of $311.21 (OVERVALUED)
Still, Stryker’s thesis can wobble if hospital capital spending slows or if acquisitions and the goodwill impairment flag deeper integration and execution issues.
Find out about the key risks to this Stryker narrative.
Another View: Cash Flows Point Higher For Stryker
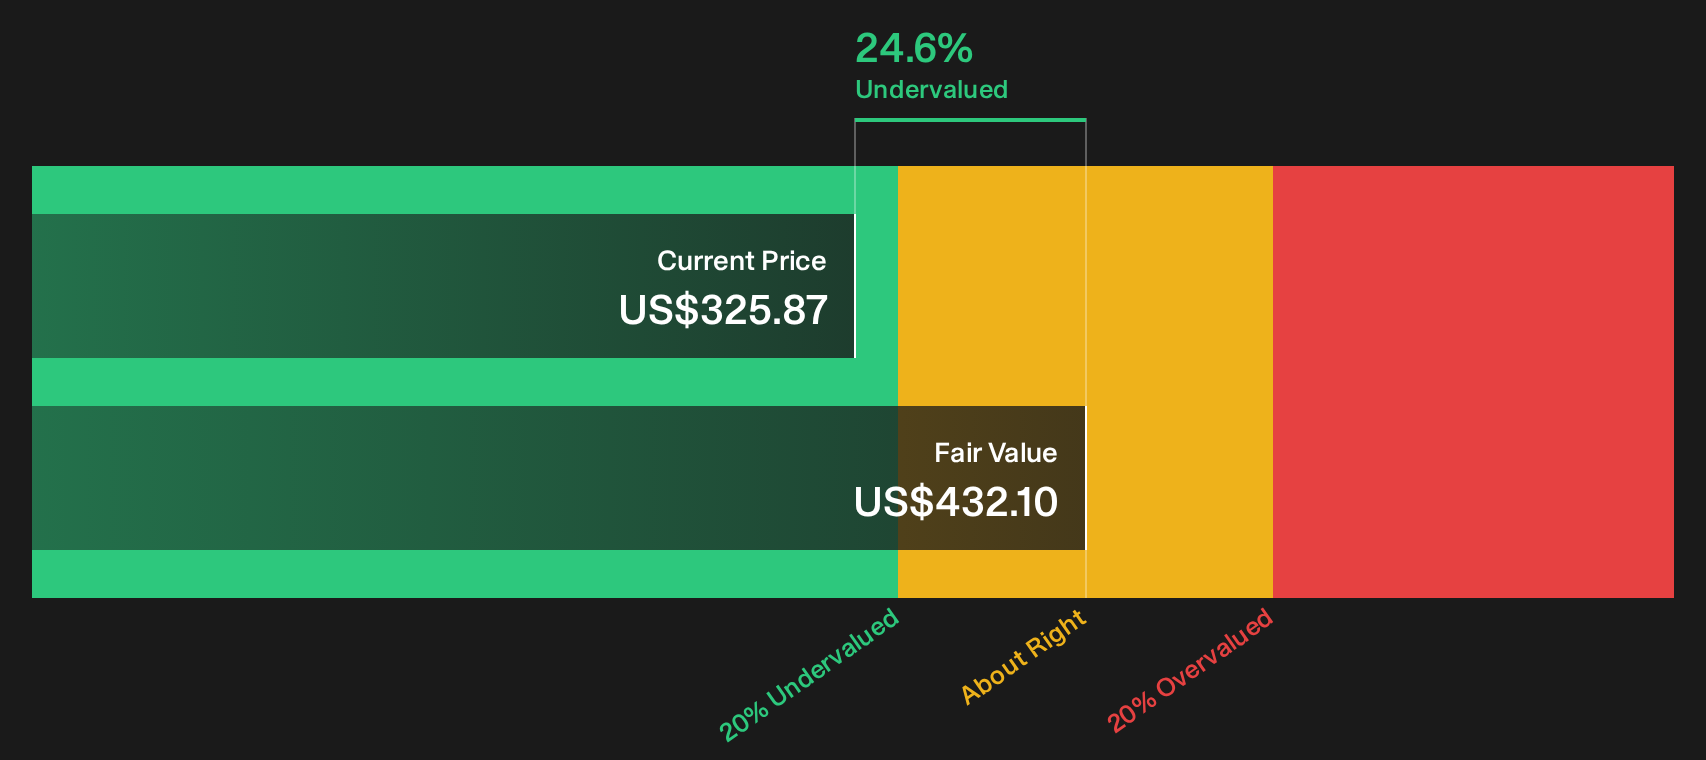
Where the leading community narrative calls Stryker about 5% overvalued at a fair value of $311.21, our DCF model lands in a very different place. It points to a future cash flow value of $432.10, which is roughly 24.6% above the current $325.87 share price.
This gap shows how sensitive Stryker is to assumptions about durability of earnings and reinvestment. One approach focuses on today’s multiple and sentiment, while the SWS DCF model leans into long term cash generation. Consider which lens feels more useful for the way you invest.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stryker for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Stryker’s valuation and outlook only matter if you put the numbers in context for yourself, so move quickly and weigh both the risks and the upside by checking the 3 key rewards and 2 important warning signs
Looking for more Stryker sized investment ideas?
If Stryker has you thinking harder about quality, risk and valuation, you do not want to stop here because the next idea could change your portfolio.
- Target dependable compounding and see which high quality companies trade at a potential discount by running the 39 high quality undervalued stocks.
- Prioritise resilience and stress test your downside by filtering for businesses on the 29 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd pays attention by scanning our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com