
What Hanwha Life Insurance Holders Saw Early
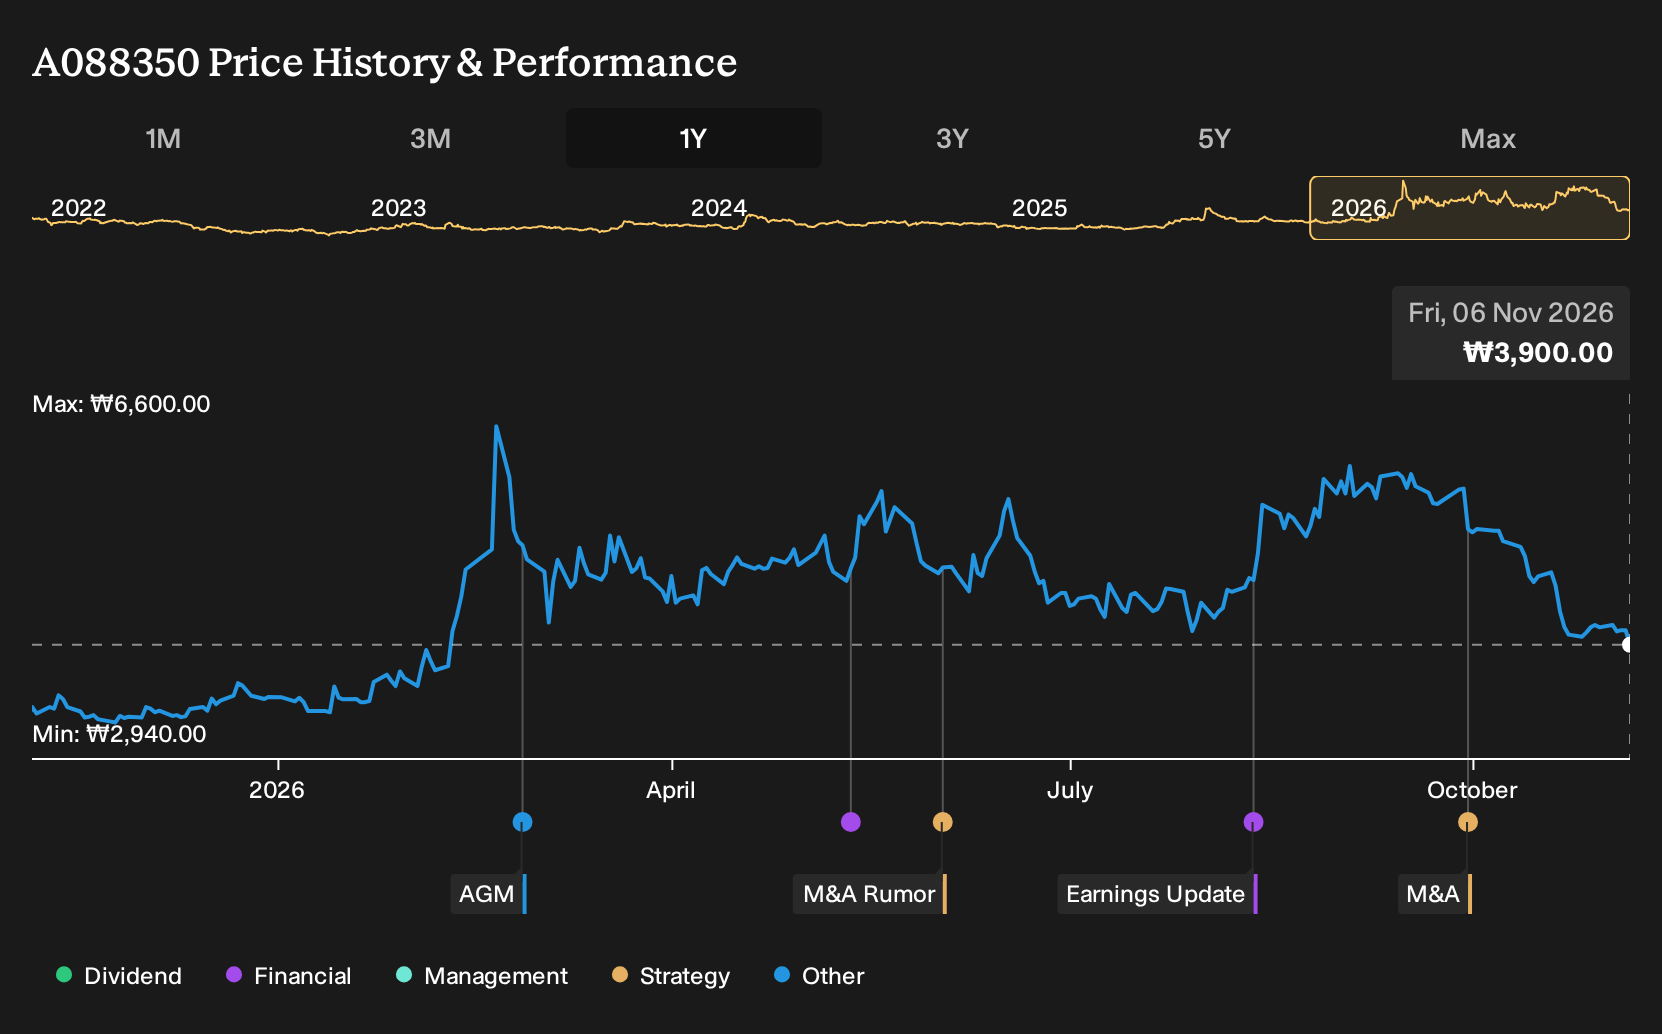
If you only glanced at Hanwha Life Insurance’s headlines this year, the story might look muddled. Revenue and profit on record in Q2 2026 were higher than a year earlier, yet analysts had been split between a bullish digital expansion story and worries about an aging Korean market and regulation. Holding Hanwha Life Insurance over the past year would have returned 27.9%, including dividends. If you had bought at the start of that period, what exactly were you being paid to believe about this business?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Hanwha Life Insurance. Zero in on 221 high quality undervalued stocks for companies trading below our estimates.
The Two Hanwha Life Insurance Stories Investors Were Weighing
The shares cost ₩3,130 at the start of the period, and buying Hanwha Life Insurance meant picking between two very different stories about where the insurer could head next.
On the bullish side, the Narrative argued for a Fair Value of ₩4,500. That view leaned on accelerated digital transformation and insurtech tools such as AI-powered underwriting to support customer growth, margin expansion, and multi year premium growth.
The bearish case pointed to a Fair Value of ₩1,900. That camp focused on an aging Korean market, low interest rates, and a legacy book of guaranteed products that could strain net margins and future premium income.
What The Results Changed For The Hanwha Life Insurance Debate
The cleanest datapoint came from Q2 2026. Hanwha Life Insurance reported total revenue of ₩11,992,068m and net income of ₩426,210m, with net margin moving from 1.9% in Q2 2025 to 3.6%. That shift in profitability gave more weight to the bullish story that talked about stronger economics, although one quarter of fatter margins did not remove the long term bear concerns.
The key assumption tested here was margin resilience, not headline growth. When you look at another insurer, track whether net income and margin are moving in the same direction as the upbeat story you are being asked to believe.
What Hanwha Life Insurance's Price Already Assumes
With Hanwha Life Insurance now at ₩3,900, this Narrative sees Fair Value below that level and argues the market may be giving generous credit for earnings quality and capital strength.
The current price leans on the idea that recent profit and capital metrics prove repeatable, so you need to weigh that against the Narrative’s concern over CSM sensitivity, health-claim volatility, and overseas execution risk.
"The numbers imply that Hanwha Life Insurance shares are pricing in an earnings and capital trajectory that appears optimistic relative to ongoing claims variability, sizeable CSM effects from new actuarial guidelines, and the execution risk around further overseas expansion and product mix shifts."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking One Step Beyond Hanwha Life
Hanwha Life highlights how insurers juggle scale, technology and cost control. The next step is seeing where similar digital ambition quietly shapes competitors.
One large global insurer now leans on digital tools and AI across operations. Its management links underwriting, claims handling and customer contact to group wide AI systems.
The goal is direct. Reach more price sensitive, underserved customers while keeping expense growth in check.
Health coverage sits at the center, combining prevention, care delivery and integrated digital services with traditional protection.
If that mix of AI, discipline and broader reach works, it could quietly reset how a diversified insurer earns and spends across regions.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 16% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com