
Dole (DOLE) Draws Fresh Interest As Efficiency Push Puts Valuation Back In Focus
Fresh commentary from Dole (NYSE:DOLE) leadership on technology, infrastructure upgrades, and operational streamlining has drawn new attention, as management links these efforts to supporting profitability and margins despite ongoing cost pressures.
Recent buying interest reflects this shift in tone, with the 7-day share price return of 6.2% and 30-day share price return of 8.4% suggesting momentum has picked up even though the year-to-date share price return is down 5.1% from earlier levels. Over the longer term, total shareholder return of 8.2% over one year and 29.6% over three years points to a stock where sentiment has periodically improved as Dole focuses on efficiency, infrastructure, and technology upgrades.
Scan for other efficiency-focused plays that are moving on fresh cost discipline and margin stories with our hand picked 39 high quality undervalued stocks.
Dole looks like a solid produce platform with global reach and fresh efficiency plans. However, after the recent share price bump, investors may want to consider whether that quality is already fully reflected in the valuation being paid today.
Most Popular Narrative: 20% Undervalued
Dole last closed at $13.88, while the most followed narrative pegs fair value around $17.44. That gap sits on a thesis that execution on efficiency, deleveraging, and demand resilience can support stronger earnings over time.
The main thing that has to go right is that Dole successfully redirects capital and management focus toward higher return segments, automation projects, and portfolio pruning, so that earnings power improves rather than just balance sheet strength.
The current valuation implies the market is pricing Dole as if cost inflation, legal risk, and segment volatility will cap earnings momentum, which leaves room for potential upside if the company’s diversification, deleveraging, and efficiency efforts gain more credit over time.
See why 10 investors see Dole as 20% undervalued.
Result: Fair Value of $17.44 (UNDERVALUED)
Still, this hinges on execution, since persistent legal costs in Hawaii or sustained pressure in Fresh Fruit input expenses could challenge the current Dole efficiency story.
Find out about the key risks to this Dole narrative.
Another View: What Dole’s P/E Is Telling You
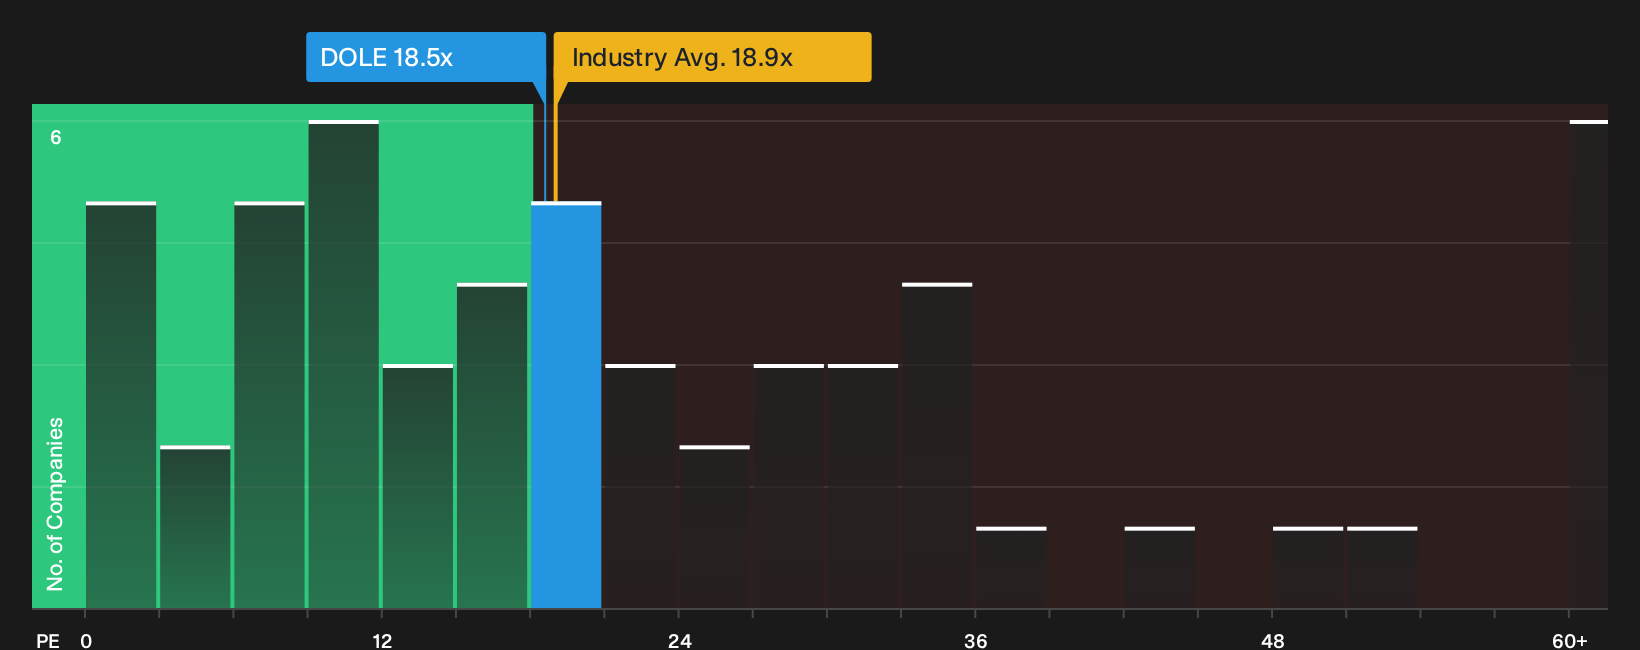
Dole screens as undervalued on future cash flows, yet the P/E story is less generous. The current multiple of 18.5x is above the 16.2x fair ratio and in line with the US Food sector on 18.5x, although below peers at 23.7x. Is that a safety margin or a value trap in disguise?
To see how this price tag lines up with earnings power and peer comparisons, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Dole has you thinking, put the numbers under your own microscope and move quickly while sentiment is still forming. To balance the upside story against the concerns being flagged, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dole?
Do not stop at one idea. Broaden your watchlist now with fresh opportunities that match your style before other investors move first.
- Target higher potential in smaller companies by scanning the 9 elite penny stocks with strong financials that fit your risk appetite and growth focus.
- Prioritize quality at a sensible price by reviewing the 39 high quality undervalued stocks that combine stronger fundamentals with appealing valuations.
- Build steadier portfolio income by checking the 8 dividend fortresses that meet your yield needs with supportive balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com