
Is Arrow Electronics (ARW) Undervalued After Record Q3 Results And New Guidance?
Arrow Electronics earnings and guidance move into focus
Arrow Electronics (ARW) has put fresh numbers on the table. Record third quarter results, new fourth quarter guidance, and an active buyback have given investors a dense cluster of information to assess.
Arrow Electronics has seen its share price retreat recently, with a 7-day share price return down 13.08% and a 30-day share price return down 21.94%. At the same time, the year-to-date share price return of 60.20% and 1-year total shareholder return of 62.11% point to strong longer term momentum that the latest record earnings, new Q4 guidance, product launch with NetApp Keystone, executive appointment, and active buyback now have to justify in the eyes of investors.
Scan how Arrow Electronics compares to a hand-picked group of AI and infrastructure beneficiaries by checking the 52 AI infrastructure stocks that investors are watching right now.
Arrow Electronics has just paired record earnings, fresh guidance and a buyback with a sharp pullback in the share price. Is the market re-pricing the business, or just its mood about it? And does the current valuation reflect that?
Most Popular Narrative: 23% Undervalued
Arrow Electronics closed at $181.09, while the most followed narrative pegs fair value at $235. That gap frames the current debate around whether the recent pullback has overshot what the underlying business and its risks justify.
Productivity and cost saving initiatives, together with multi year restructuring that has brought operating expenses down to roughly 63% to 64% of gross profit and allowed non GAAP operating margins to reach about 4% of sales in the first half of 2026, provide operating leverage that can translate future revenue into earnings.
See why 3 investors see Arrow Electronics as 23% undervalued.
Result: Fair Value of $235 (UNDERVALUED)
Still, ECS contract restructuring charges and external models that flag Arrow Electronics as 25% to 35% above some intrinsic value estimates could both pressure the bullish fair value story.
Find out about the key risks to this Arrow Electronics narrative.
Another View: cash flows paint a tougher Arrow Electronics picture
Price based narratives point to Arrow Electronics trading at good value on earnings multiples, yet the Simply Wall St DCF model tells a different story. At $181.09, the share price sits above an estimated future cash flow value of $113.23, which frames Arrow as expensive on this lens.
That kind of gap matters. It suggests earnings today may look attractive, while longer term cash generation assumptions inside the model are less generous. The question for you is simple: Do you trust the current P/E signals more, or the cash flow scenario embedded in the DCF?
Look into how the SWS DCF model arrives at its fair value.
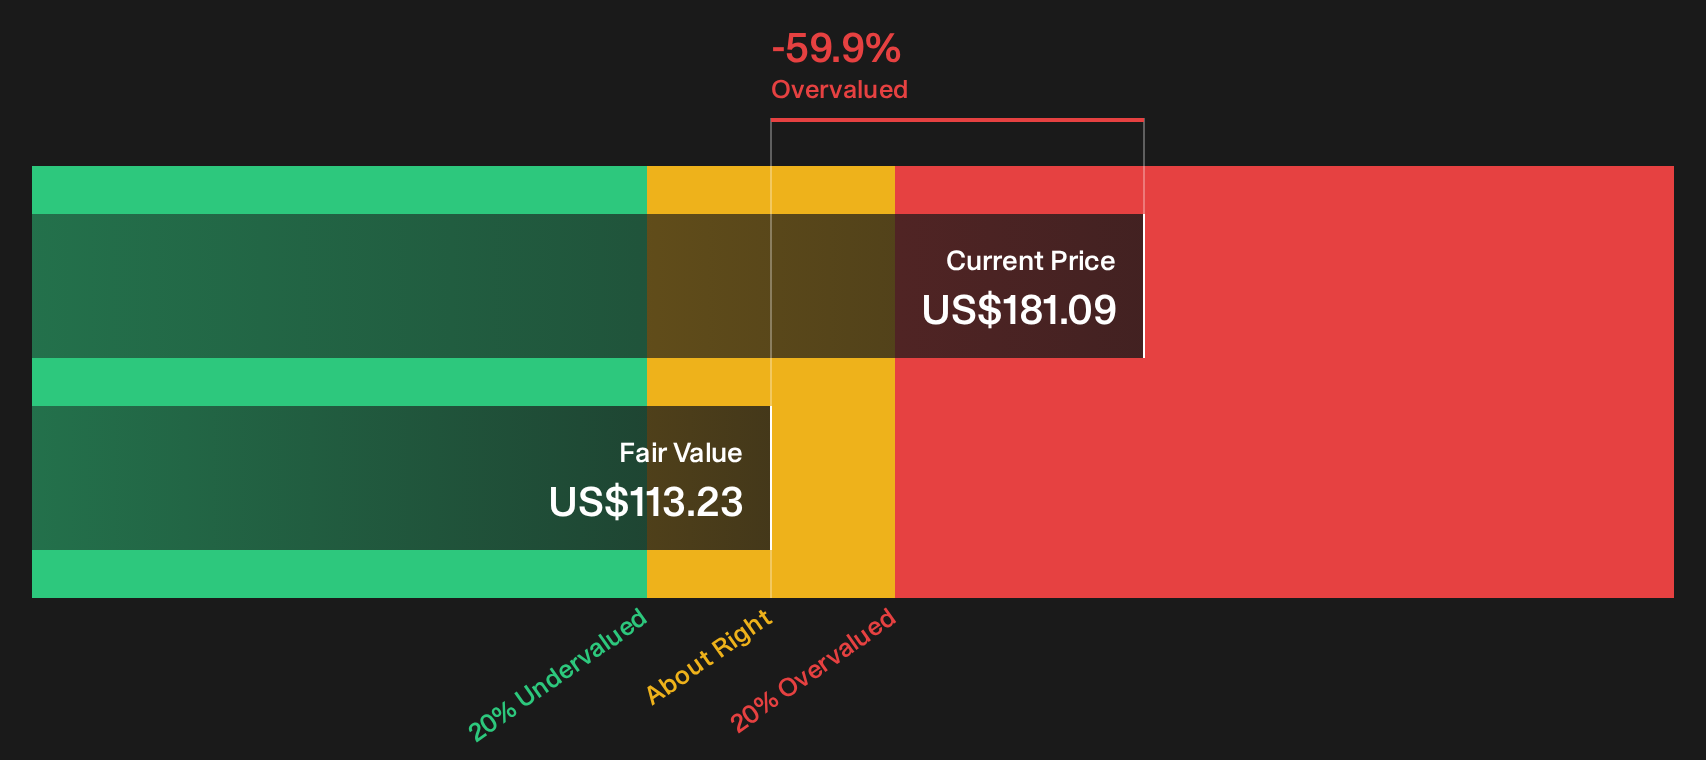
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Arrow Electronics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Arrow Electronics is clearly split, and that kind of disconnect between price and narratives does not usually last. Take a closer look at the data and form your own take before the crowd settles on a view, then weigh those positives against the 5 key rewards.
Looking for more Arrow Electronics investment ideas?
Do not stop your research with Arrow Electronics alone. Fresh opportunities keep showing up, and the investors who act on them tend to move first.
- Target resilient compounding potential by scanning companies with a strong financial cushion and consistent fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for value opportunities that combine quality operations with pricing that still looks reasonable through the 39 high quality undervalued stocks.
- Build a stream of potential cash returns by reviewing income focused businesses screened in the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com