
How International Sales Growth At Monster Beverage (MNST) Has Changed Its Investment Story
- Monster Beverage reported Q3 2026 sales of US$2,563.05 million and net income of US$568.43 million, with diluted EPS from continuing operations at US$0.29, alongside a US$19.9 million property and equipment impairment charge.
- Strong international demand lifted net sales; however, margin pressure from higher input costs and a heavier mix of lower margin overseas business limited profit growth relative to revenue.
- The next step is to assess how Monster Beverage's investment narrative holds up in light of strong international sales combined with ongoing margin pressure.
Expand your watchlist beyond Monster Beverage by scanning a curated set of consumer-focused stocks with the 36 high quality undervalued stocks.
Monster Beverage Investment Narrative Recap
To own Monster Beverage, you need to be comfortable with a story where broad energy drink demand and a growing global footprint are the main drivers, while cost inflation and mix pressure sit on the other side of the scale. The latest quarter kept that trade off in focus. Sales moved higher, profits also rose, but gross margin slipped as overseas volume and input costs weighed.
Right now, the key short term swing factor is whether pricing and efficiency work can steady profitability while international growth remains strong. The biggest risk is that freight, aluminum and distribution expenses, along with lower margin international mix, run ahead of those pricing actions and keep squeezing earnings.
The most relevant recent update is Monster Beverage’s Q3 2026 report, which showed net sales of US$2,563.05 million and net income of US$568.43 million, plus a US$19.9 million property and equipment impairment charge. Basic and diluted EPS from continuing operations were US$0.29 compared with US$0.27 a year earlier.
This impairment is relatively small against a business generating US$7,453.82 million of sales and US$1,722.45 million of net income over nine months, so it does not change the core thesis. For catalysts, the more important levers remain international expansion, the 2027 product pipeline and selective price increases, set against the ongoing risk that higher freight, fuel and aluminum costs cap margin progress.
What The Current Monster Beverage Forecasts Assume
Monster Beverage's narrative projects US$12.1b revenue and US$2.9b earnings by 2029. This rests on analysts assuming 9.6% yearly revenue growth and an earnings increase of about US$0.8b from US$2.1b today.
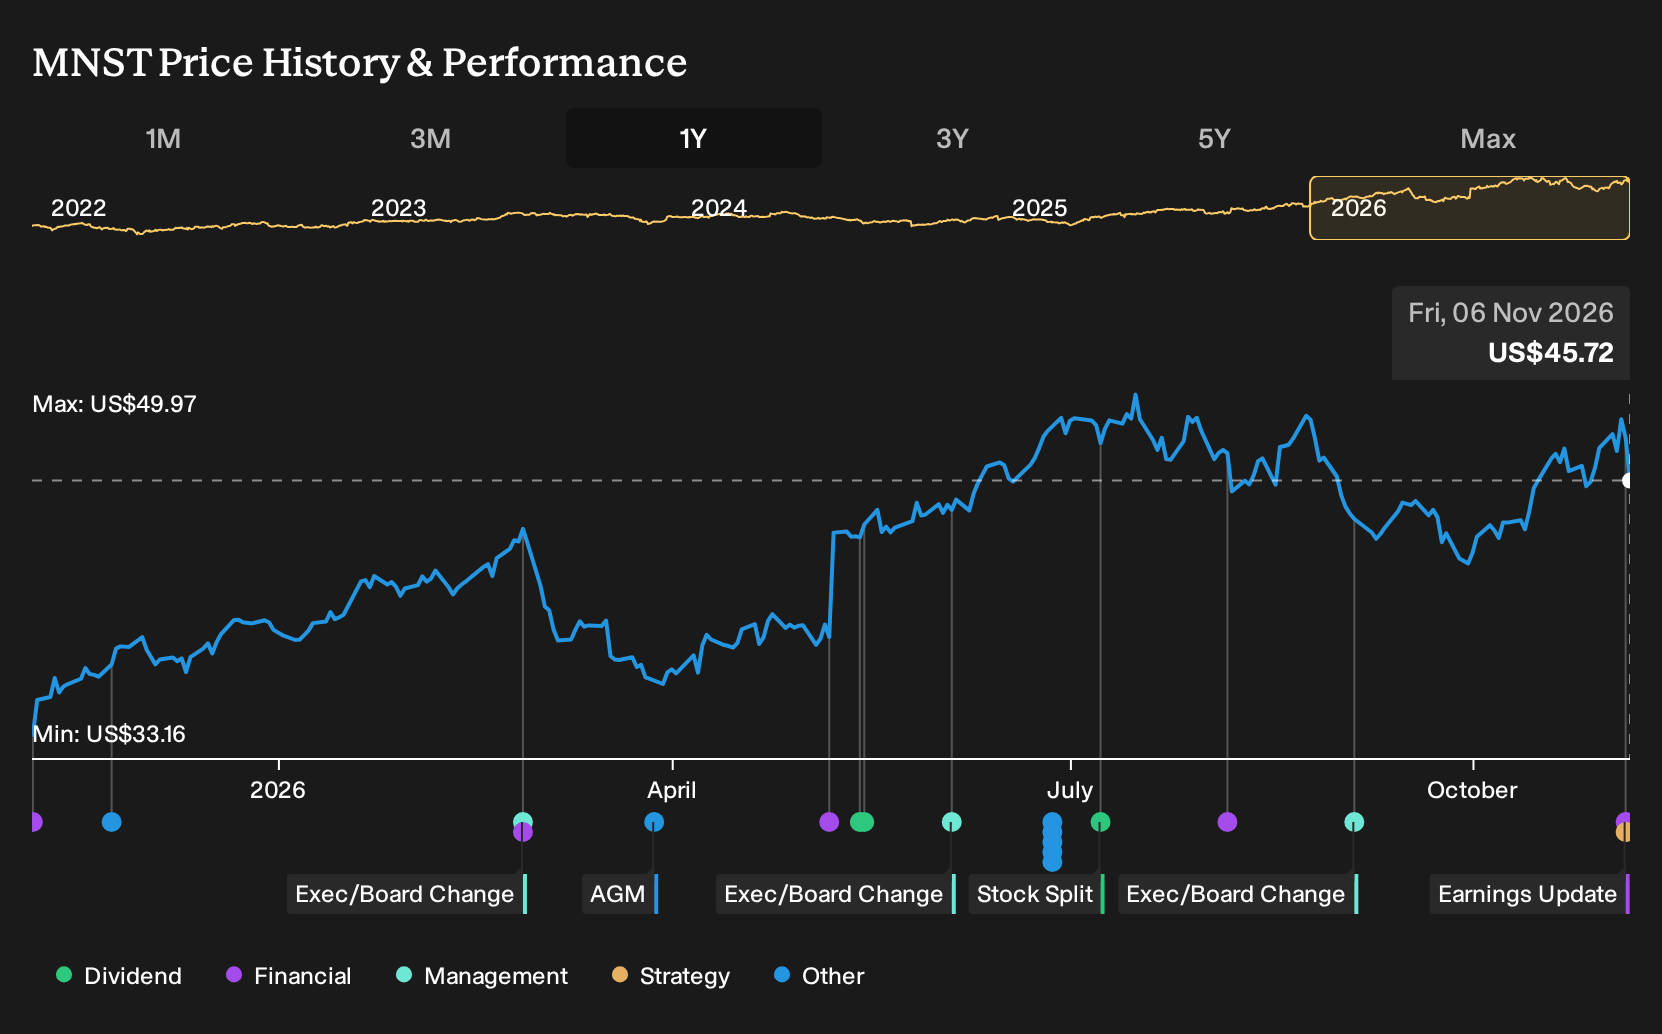
Uncover how Monster Beverage's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view worries less about Monster Beverage’s growth and more about execution risk after the announced Americas leadership change. The most cautious analysts were pencilling in about US$11.7b in revenue and US$3.0b in earnings by 2029 before this Q3 update, so their narrative is already more pessimistic. Use this quarter’s numbers as a prompt to compare those assumptions with your own and explore how your view might differ.
Explore 4 other Monster Beverage fair value estimates, including one that suggests as much as 11% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Monster Beverage?
Once you have formed a view on Monster Beverage, it can help to compare it with other opportunities that share similar qualities or very different risk profiles. Use the Simply Wall St Screener to scan for candidates that match the kind of portfolio you want to build, rather than just reacting to headlines.
- If you want income to do more of the heavy lifting, focus on higher yielding opportunities by reviewing the 7 dividend fortresses.
- For steadier balance sheets and stronger fundamentals, narrow your search with a list of solid balance sheet and fundamentals (25 results) to see which businesses might better handle tougher conditions.
- Readers looking for underfollowed prospects with room for the story to develop can scan a 19 high quality undiscovered gems and spot ideas that are not yet widely discussed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com