
Cementos Molins (BME:CMO) Could Be Overvalued Following Strong Nine Month Results
Cementos Molins (BME:CMO) just released its nine-month 2026 results, reporting sales of €1,241 million compared with €751 million a year earlier. Net income was €172 million, up from €141 million in the previous period.
The fresh nine month figures land as Cementos Molins’ share price has risen 18.75% over the past 30 days and is 21.02% higher year to date. Meanwhile, the 34.14% one year total shareholder return and very large 3 year and 5 year total shareholder returns suggest momentum has come in waves rather than in a straight line.
Scan Cementos Molins alongside a hand picked 583 high quality undiscovered gems that have been moving on fresh earnings updates and reported fundamentals.
Bulls see Cementos Molins’ recent earnings and share price strength as confirmation of a solid franchise, while bears point to the valuation and price target gap. Which side do the current numbers support next?
Price-to-Earnings of 11.2x: Is it justified?
Cementos Molins closed at €38.00 while trading on a P/E of 11.2x that screens as low next to both the Spanish market and its Basic Materials peers.
The P/E ratio compares the current share price with earnings per share. For a construction materials group like Cementos Molins, that metric helps you see how much investors are paying for each euro of profit in a sector that can be tied to the economic cycle.
Here, the stock carries a P/E of 11.2x against 16.2x for the wider Spanish market and 20.7x for the European Basic Materials group. That gap signals the market is attaching a cheaper tag to Cementos Molins’ earnings than to both the home market and sector, even after 25.5% earnings growth over the past year and 14.5% per year over five years.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 11.2x (UNDERVALUED)
Still, Cementos Molins trades above the €32.10 analyst price target, and reported annual revenue declined 1.7%, which could challenge the bullish momentum narrative.
Find out about the key risks to this Cementos Molins narrative.
Another View: What Cementos Molins’ Cash Flows Say
The earnings multiple paints Cementos Molins as cheap, yet our DCF model tells a very different story. With the shares at €38 and the future cash flow value estimated at €17.41, the stock screens as expensive on this second yardstick. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
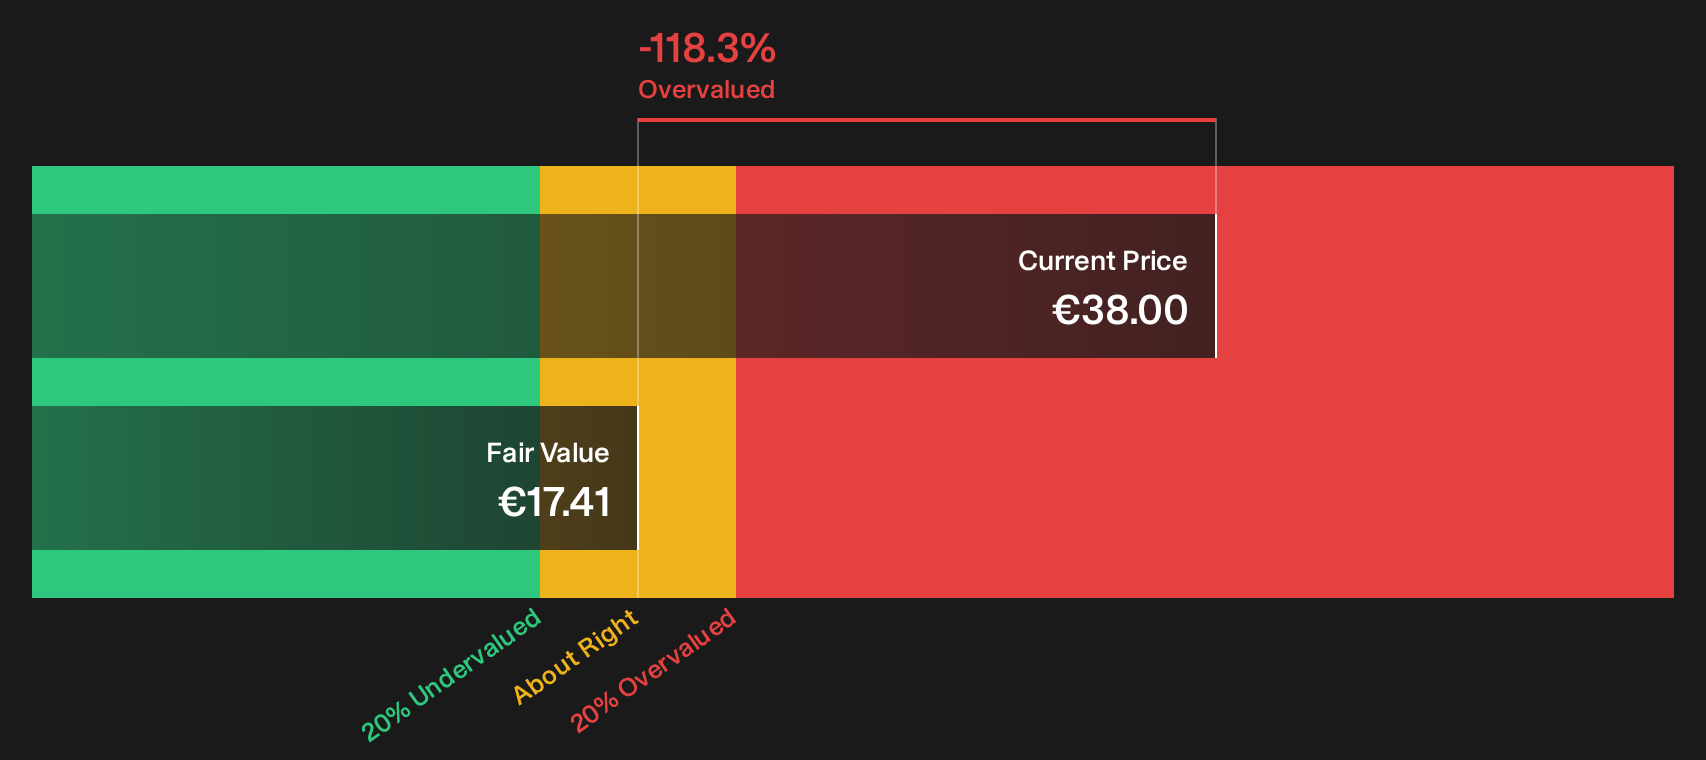
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cementos Molins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 218 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Cementos Molins is split, which makes this exactly the kind of situation where you should move fast and test the numbers yourself. To weigh the upside against the concerns directly, go through the 3 key rewards and 2 important warning signs
Looking for more Cementos Molins sized ideas?
If you stop with Cementos Molins, you risk missing other setups where quality, price and risk all line up in your favour.
- Spot potential mispricings by scanning companies that combine quality fundamentals with attractive valuations through our 218 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses with strong yields and payout histories using the 228 dividend fortresses.
- Sleep easier at night by concentrating on resilient businesses with stronger financial footing through the 211 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com