
Conagra (CAG) Stock Seems About Right For Its Sales Base
Conagra Brands has spent the last few years out of favor with the market, yet the recent rebound in the share price now puts a fresh spotlight on what investors are paying for its sales. With a long slide followed by a short burst of gains, the question is whether the current valuation lines up with the revenue base of this packaged foods group.
- Over the past 5 years the stock has fallen 38.8%, which puts pressure on the case for how much investors should be willing to pay for each dollar of Conagra Brands' sales today.
- The business leans on established food brands that can support relatively steady volumes and pricing. This may influence how investors think about the durability of its revenue stream and the multiple applied to those sales.
- There is a second opinion on Conagra Brands worth weighing. See what analysts think Conagra Brands's shares could be worth.
The stock's next move may depend on whether the current market price fairly reflects Conagra Brands' sales base.
If you want to test the same sales based valuation question beyond Conagra Brands, you can scan the broader market using 38 high quality undervalued stocks.
Where Does Conagra Brands Sit on Sales?
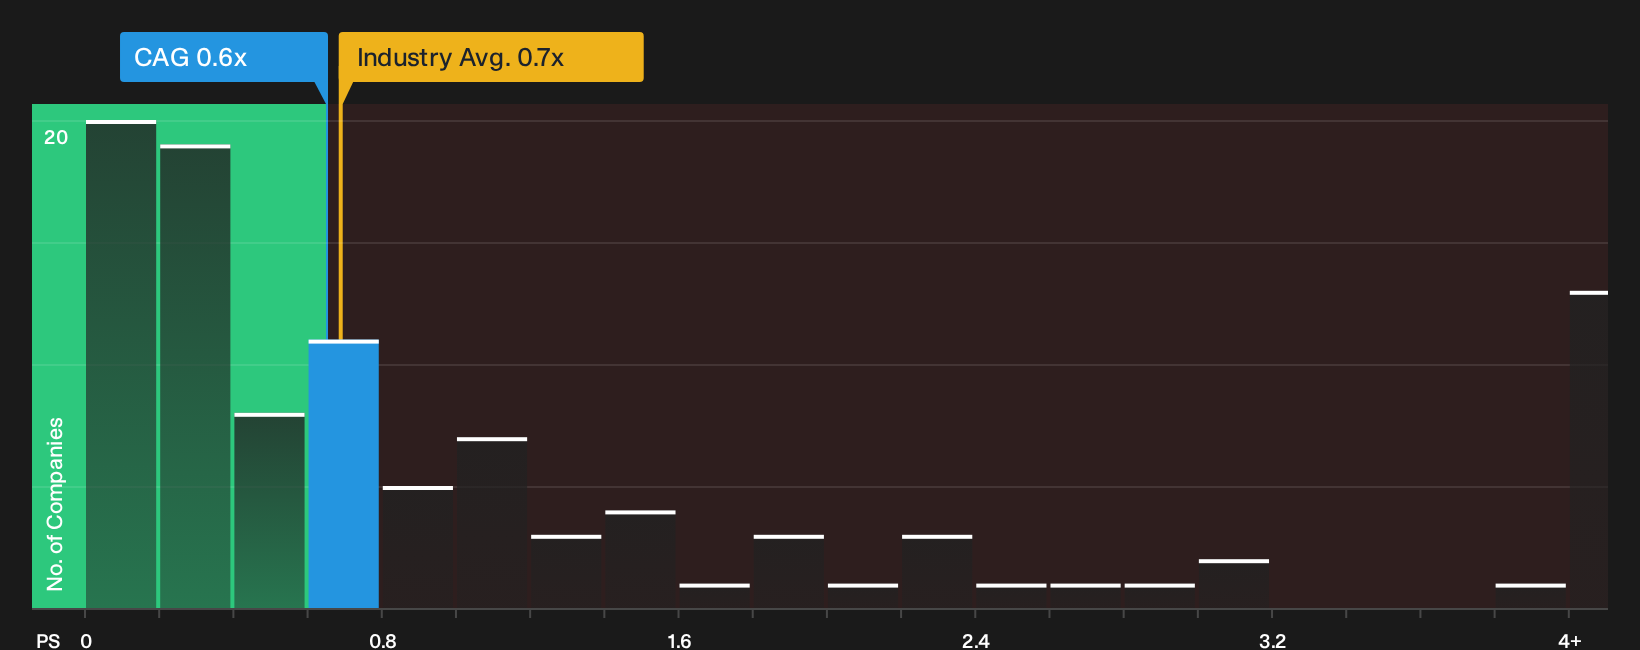
P/S is a good fit for Conagra Brands because the business leans on established packaged food labels where investors often focus on what each dollar of revenue costs in the market. On this yardstick, the stock trades on a P/S of about 0.6x, which is slightly below the food industry average of roughly 0.7x and very close to the peer group on around 0.7x. That keeps the share price anchored more to its sales base than to earnings swings, which can move around for reasons that have little to do with demand for its products.
The valuation model that blends Conagra Brands' growth outlook, profitability profile, scale and risk suggests a P/S level that is close to where the market currently prices it. The current multiple sits near that tailored reference point rather than showing a strong discount or a big premium, so the share price asks investors to judge the quality and staying power of its revenue stream more than to bet on a clear mispricing. Explore the numbers behind Conagra Brands's P/S valuation.
The Conagra Brands Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Conagra Brands' P/S ratio leaves off and state directly what kind of future for revenue, margins and earnings would need to play out for the stock to be worth meaningfully more or meaningfully less than it is today on the market. Each narrative links its number to a clear view on how growth, profitability and risk could evolve, giving you something concrete to compare against as new information comes through.
Community views on Conagra Brands split between those who see modest upside from execution and those who think the current price already bakes that in.
Bull case: roughly fairly valued
"The planned exit of smaller businesses such as Celeste pizza and the review of more than 5,500 SKUs over the next 12 to 18 months could surface underappreciated mix benefits if resources shift toward higher margin frozen meals and snacks..."
Discover why this Narrative puts Conagra Brands at roughly fairly valued.
Bear case: 11% overvalued
"Continued inflation and tariffs, together with higher than expected price elasticities already reflected in guidance for mid single digit volume declines and an adjusted operating margin of only 10% to 10.5% in fiscal 2027, could keep cost pressures above the targeted productivity benefits and weigh on net margins and earnings..."
Explore why this Narrative puts Conagra Brands at 11% overvalued.
One more Conagra Brands check that sits beside the price tag
The last missing piece is who actually runs Conagra Brands and how their pay packets line up with your interests, because the leadership scorecard can matter as much as the multiple. See who runs Conagra Brands and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com