
What Cavco Industries Stock Earnings Report Means For Shareholders
- Cavco Industries reported second quarter 2026 sales of US$633.74 million and net income of US$55.44 million, with diluted earnings per share from continuing operations of US$7.17, compared with the prior year period.
- Across the first six months of the fiscal year, Cavco Industries recorded higher sales of US$1,219.71 million alongside lower net income of US$97.71 million. This highlights how cost pressures and product mix can move in a different direction from top line progress.
- The next step is to examine how Cavco Industries’ higher quarterly sales and earnings may influence its broader investment narrative for investors.
Scan how Cavco Industries compares with other manufacturers facing similar earnings twists by reviewing a curated set of list of solid balance sheet and fundamentals (25 results) in the current market backdrop.
Cavco Industries Investment Narrative Recap
To own Cavco Industries, you need to believe that demand for factory built housing and financing can support steady throughput while management works on profitability. The latest quarter shows higher sales and slightly higher quarterly net income, yet earnings for the first half of the year are lower than last year. That mix keeps the short term focus on execution rather than pure volume.
The key near term catalyst is whether Cavco Industries can ease tariff and input cost pressure enough to stabilise margins after a period of compression. The main risk is that higher SG&A, tariffs and a higher effective tax rate keep chipping away at earnings even if sales hold up, which the six month figures already reflect.
The fresh earnings release for the quarter and first half to September 26, 2026 is the central update investors have to work with right now. Cavco Industries reported quarterly sales of US$633.74 million and net income of US$55.44 million, plus first half sales of US$1,219.71 million with net income of US$97.71 million.
Those numbers keep the spotlight on operational levers already in play. Plant investments, the American Homestar integration and the more profitable Financial Services arm all matter more if cost inflation and tariffs remain a drag. The earnings pattern in this report tests whether those internal efforts can offset headwinds rather than relying on end market growth alone.
Cavco Industries' current earnings of US$184.2 million are set against analyst expectations for US$270.9 million of earnings on US$3.0b of revenue by 2029, based on a projected 7.3% yearly revenue growth rate and an earnings increase of about US$86.7 million by that forecast year.
Uncover how Cavco Industries' fair value indicates an 11% potential upside to its current price, a discount Cavco Industries investors may see close sooner than anticipated.
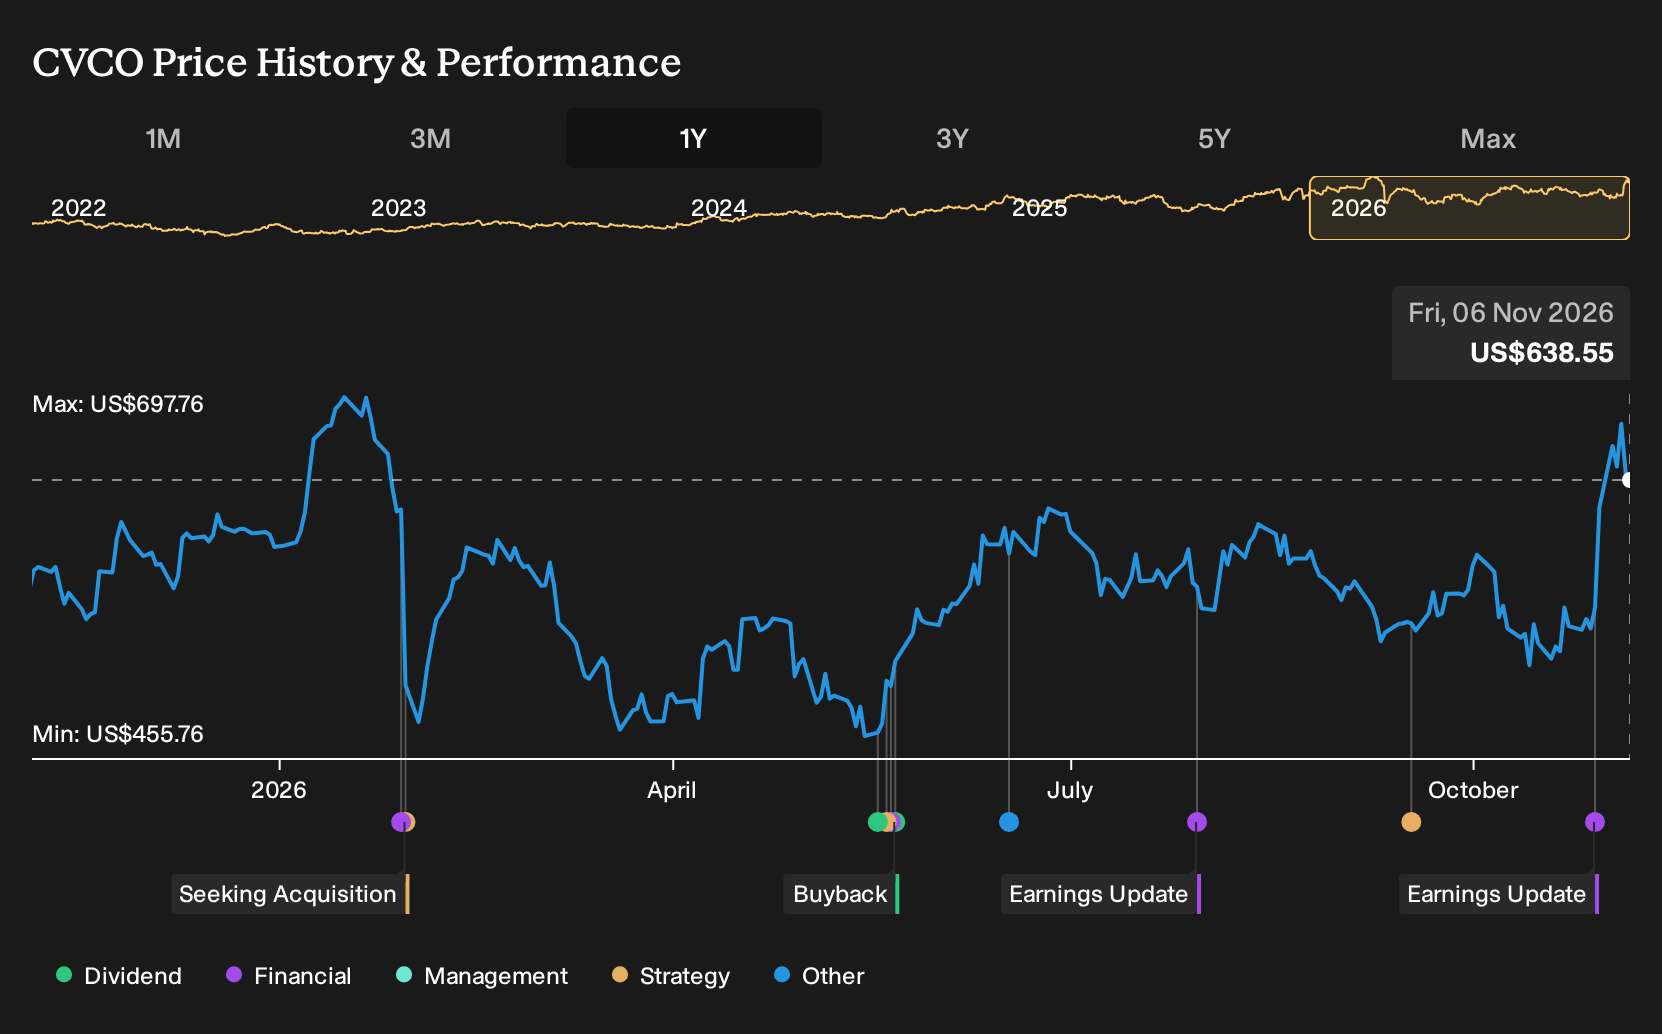
Exploring Other Perspectives
Fair value estimates for Cavco Industries from the two Simply Wall St Community contributors range from about US$159 to US$712, which already shows how far apart retail opinions can be. Those views sit beside tariff risk, margin pressure and acquisition related costs, so you are wise to examine several contrasting viewpoints before acting.
Explore another Cavco Industries fair value estimate, including one that suggests as much as 11% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cavco Industries research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cavco Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cavco Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cavco Industries?
If Cavco Industries has sharpened your interest in how earnings quality, balance sheets and cash flows interact, it can be useful to scan a wider field of companies that share similar strengths or offer different risk profiles.
- If capital preservation is front of mind, start with a basket of businesses that screen for lower risk profiles through the 31 resilient stocks with low risk scores.
- For readers hunting for quality at a discount, cast a wider net over companies that combine solid fundamentals with more modest valuations using the 19 high quality undiscovered gems.
- If income is your priority, focus your attention on companies with robust cash generation that also return capital to shareholders via the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com