
Did Return To Profit Just Shift Del Monte (DMC) Investment Narrative?
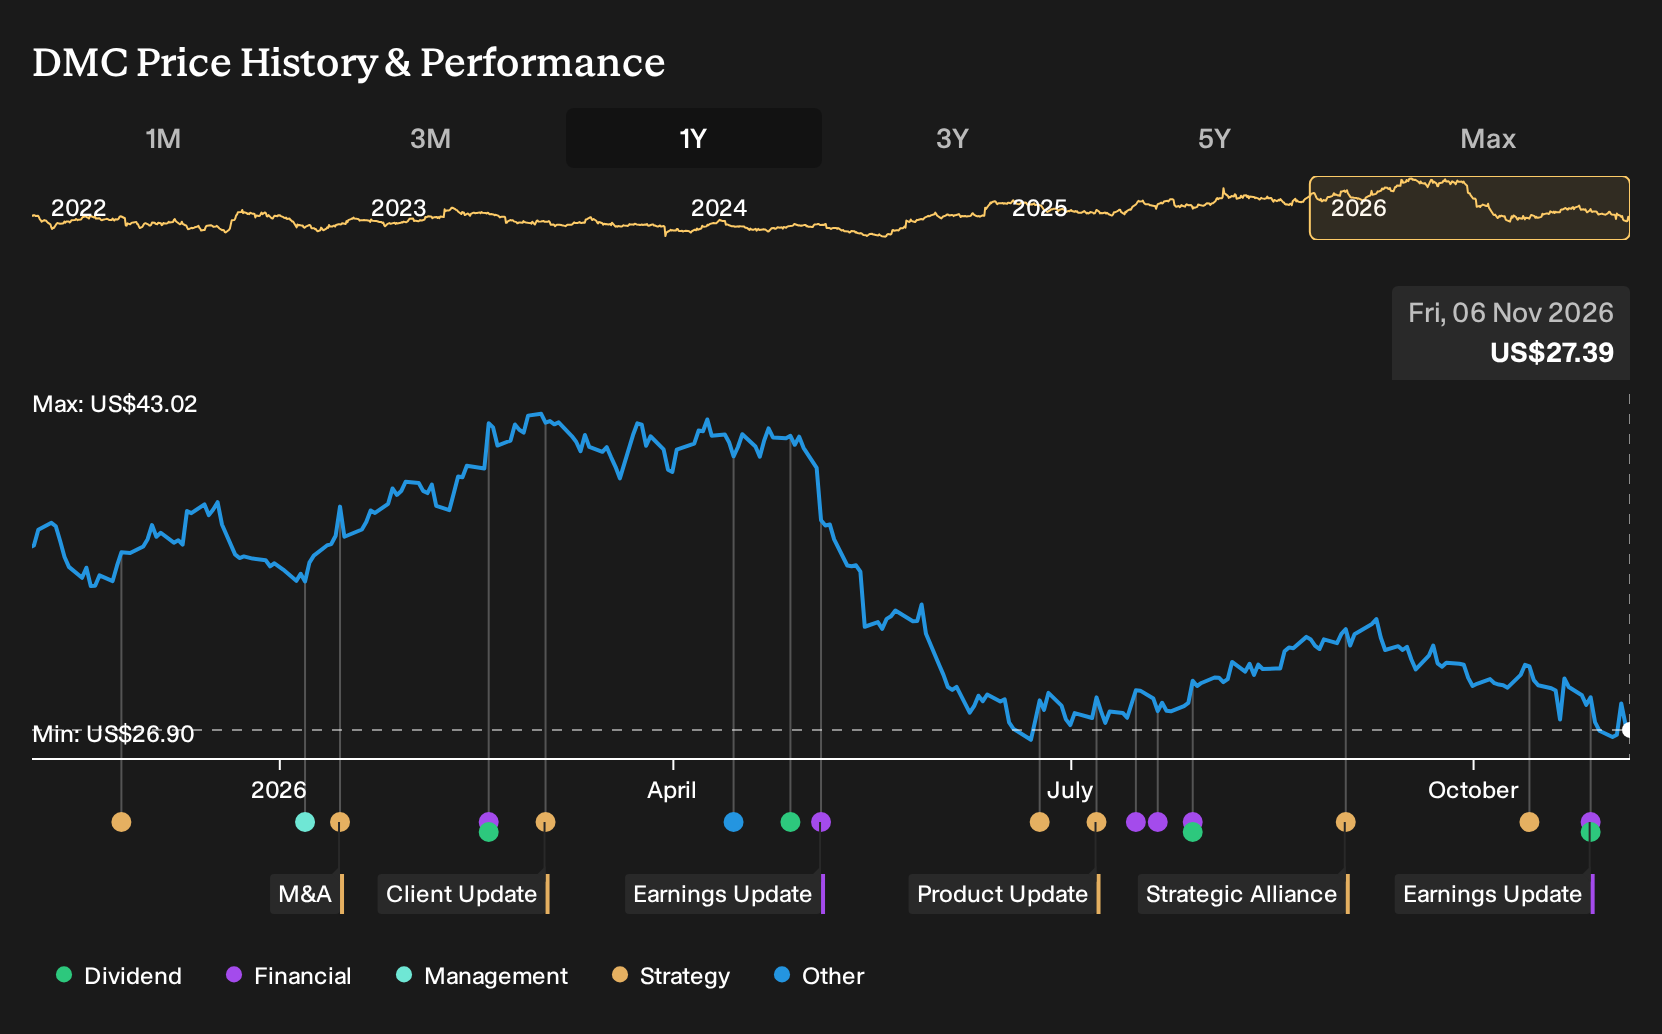
- Del Monte Corporation reported third quarter 2026 sales of US$1,095.3 million and net income of US$18.3 million, and the board declared a US$0.30 per share quarterly cash dividend payable on December 4, 2026 to shareholders of record on November 11, 2026.
- The return to profit alongside a cash dividend reflects how Del Monte is balancing margin execution in its core food operations with cash returns to shareholders.
- This article examines how Del Monte's return to quarterly profit and its latest dividend decision may influence its broader investment narrative.
Scan how Del Monte's profit return and dividend fit alongside other income focused opportunities by reviewing the hand picked 7 dividend fortresses.
Del Monte Investment Narrative Recap
To own Del Monte, you need to be comfortable with a food producer that earns relatively thin net margins and is working to lean more on prepared and value added products instead of pure commodity fruit. In the short term, the main swing factor is execution on pricing and mix in fresh produce while keeping volumes steady in a competitive banana market.
The biggest near term risk is that cost pressures in freight, fertilizer and packaging, combined with aggressive banana pricing by rivals, could eat into the progress reported in the latest quarter. The return to profit supports sentiment but does not remove exposure to disease issues in the banana supply chain or higher funding costs.
The recent third quarter earnings release is the key announcement here. Sales of US$1,095.3 million and net income of US$18.3 million indicate the business is producing profit again after a loss in the prior year period. This matters when considering how Del Monte funds capex, integration work and potential product launches from internal cash generation.
The same update showed nine month net income of US$49.4 million on US$3,358.5 million of sales. This frames the current earnings base that supports both the US$0.30 dividend and ongoing investment. For potential catalysts such as premium pineapple expansion or prepared foods growth to be meaningful, this earnings engine and the cash coverage of the payout remain key watch points.
What Del Monte's Analyst Forecasts Are Pricing In
Del Monte's latest analyst setup leans heavily on moderate expansion rather than dramatic reinvention. Forecasts point to revenue growing by 4.3% a year over the next three years, helped by a richer mix from prepared foods and premium fruit rather than a pure volume story in bananas.
The same consensus assumes profit margins rise from 1.9% today to 2.2% in three years. That is a relatively small move in absolute terms. For an income focused investor, it still matters because even a modest margin lift on a multi billion dollar sales base can influence how repeatable the current dividend and future cash returns feel.
Earnings expectations give a clearer profit anchor. Analysts see earnings today at US$81.3 million and are projecting US$107.4 million by 2029. That is an increase of about US$26 million in absolute profit, supported by the shift toward higher margin products, tighter cost control and some help from a shrinking share count, with shares outstanding expected to decline by 1.31% a year.
Valuation work in the consensus report centers on those same 2029 targets. To line up with the current analyst framework, you would be looking at Del Monte generating about US$5.0b of revenue and US$107.4 million of earnings in 2029. The implied fair value case uses a P/E of 21.1x on those future earnings and a discount rate of roughly 7.2% to translate that back to today.
Del Monte's narrative projects about US$5.0b of revenue and US$107.4 million of earnings by 2029. This requires 4.3% yearly revenue growth and an earnings increase of roughly US$26 million from US$81.3 million today.
Explore why Del Monte's fair value is estimated to have a 48% potential upside to its current price before the market adjusts.
Exploring Other Perspectives
Some of the lowest ranked analysts focus on banana weakness as the key risk, arguing that freight, fertilizer and disease costs could keep future returns tight even if Del Monte grows prepared foods. Before this dividend and profit news, that group was pencilling in about US$5.0b of 2029 revenue and roughly US$106.7 million of earnings. Their view is more cautious than consensus, so use it as one reference point while you compare several potential paths for Del Monte from here.
Explore 2 other Del Monte fair value estimates, including one that suggests it could be worth just $40.60!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Del Monte research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Del Monte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Del Monte's overall financial health at a glance.
Looking For More Investment Ideas Beyond Del Monte?
If Del Monte's mix of thin margins, dividends and steady execution has your attention, it can help to compare it with other companies that have different risk and income profiles. Using the Simply Wall St Screener, you can quickly scan groups of stocks that share traits you care about, then decide which ones deserve a deeper look.
- For investors who care most about resilience, you can filter for companies with stronger finances through a curated list of solid balance sheet and fundamentals (25 results) that helps you focus on balance sheet strength before anything else.
- If you want ideas where downside risk is the first question, you can start with a 31 resilient stocks with low risk scores that concentrates on businesses with more measured risk scores.
- Those hunting for less crowded opportunities can survey a 19 high quality undiscovered gems that highlights under the radar companies with solid fundamentals that may warrant further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com