
Is International Petroleum (TSX:IPCO) Undervalued After Strong Earnings And Blackrod First Oil?
Why International Petroleum’s latest earnings matter for investors
International Petroleum (TSX:IPCO) just paired a sharp jump in quarterly profit with steady 2026 production guidance and early output from its Blackrod Phase 1 project, putting fresh attention on the stock’s risk reward trade off.
The latest move tells a mixed story. International Petroleum’s share price jumped 2.37% on the day of the earnings update; however, it is still down 11.62% over the past week and 2.88% over the past month, while a year-to-date share price return of 39.29% and a 5-year total shareholder return of 412.28% point to momentum that has built over a longer horizon.
Scan International Petroleum’s peers that also combine strong recent earnings with asset depth can be found using our curated list of 7 high quality undervalued stocks.
International Petroleum now combines a softer share price with stronger earnings and fresh Blackrod volumes. Do the current numbers still skew the risk reward toward buyers or toward patience?
Most Popular Narrative: 18% Undervalued
International Petroleum last closed at CA$35.45 against a widely followed fair value estimate of about CA$43.06, so the current share price sits below what that storyline considers a reasonable level based on future cash flow and earnings assumptions.
The ramp up of International Petroleum’s Blackrod Phase 1 project, which reached first oil on 31 May 2026 and targets a 30,000 bbl/d plateau with a breakeven of US$47 WTI, is expected to shift the business from heavy growth capex toward structurally higher operating cash flow and free cash flow, supporting revenue and earnings.
See why 10 investors see International Petroleum as 18% undervalued.
Result: Fair Value of CA$43.06 (UNDERVALUED)
Still, the International Petroleum story can change quickly if Blackrod Phase 1 stumbles on its production ramp, or if unhedged oil prices weaken meaningfully.
Find out about the key risks to this International Petroleum narrative.
Another View: What International Petroleum’s P/E Ratio Signals
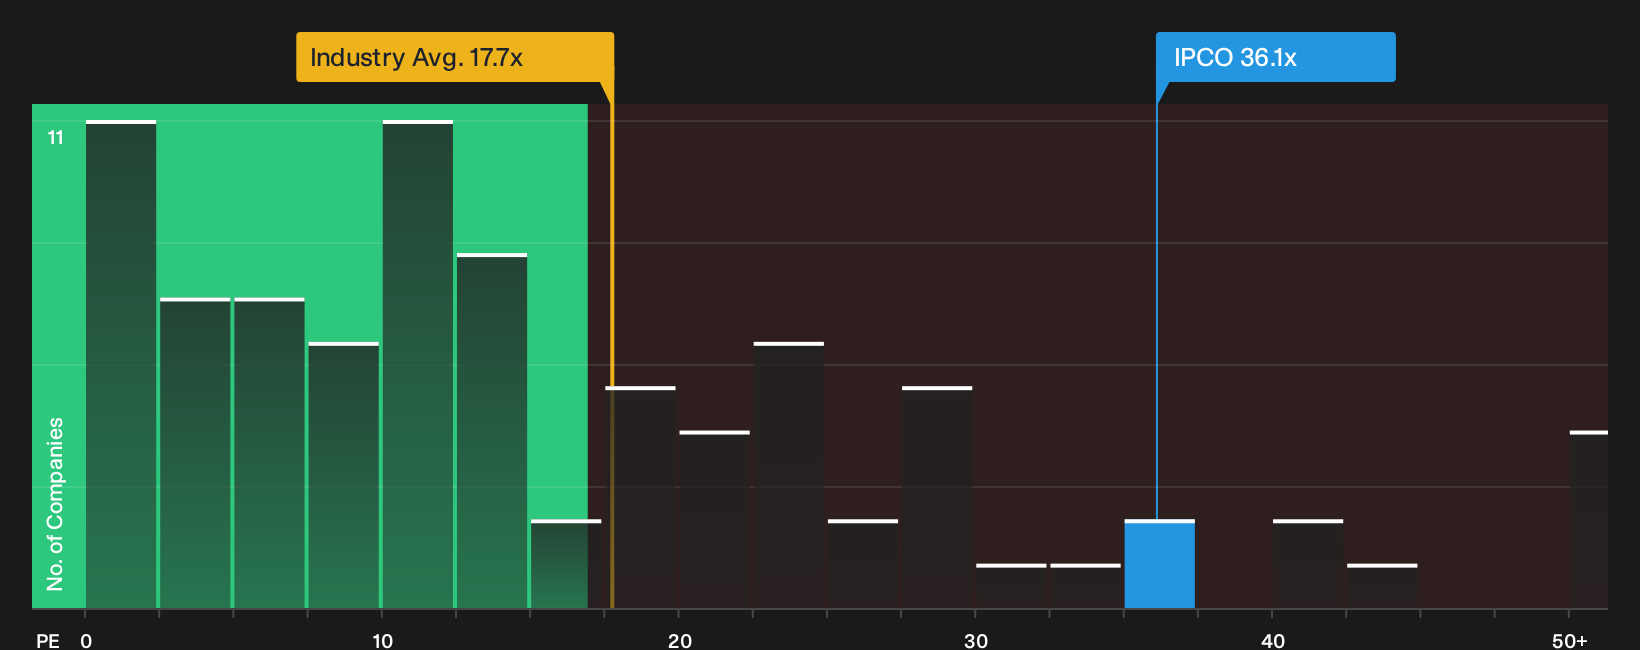
International Petroleum looks cheap on a cash flow model, yet its P/E of 36.1x is high compared with the Canadian oil and gas industry at 17.7x and a fair ratio of 19.4x. That gap suggests you are paying up for the earnings story, even if the shares look discounted on other metrics. Which signal do you trust more right now?
Before leaning too heavily on any single metric, it helps to see how these valuation numbers fit together over time. This includes how the current P/E compares with peers and the fair ratio trend, in our breakdown of See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or a clear setup? Act quickly by checking the key positives and negatives for yourself in our breakdown of 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond International Petroleum?
If International Petroleum has your attention, do not stop here. Use the same structured thinking to compare other companies and pressure test your next move.
- Target resilient balance sheets and solid fundamentals by running companies through our curated list of solid balance sheet and fundamentals (5 results) so weak finances do not catch you off guard.
- Hunt for quality at a discount using the 8 high quality undiscovered gems before the broader market starts paying attention to these quieter opportunities.
- Dial down portfolio risk by focusing on stability first with the 9 resilient stocks with low risk scores so sudden swings do not dictate your long term results.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com