
What Erste Group Bank Shares' Earnings Beat Means For Shareholders
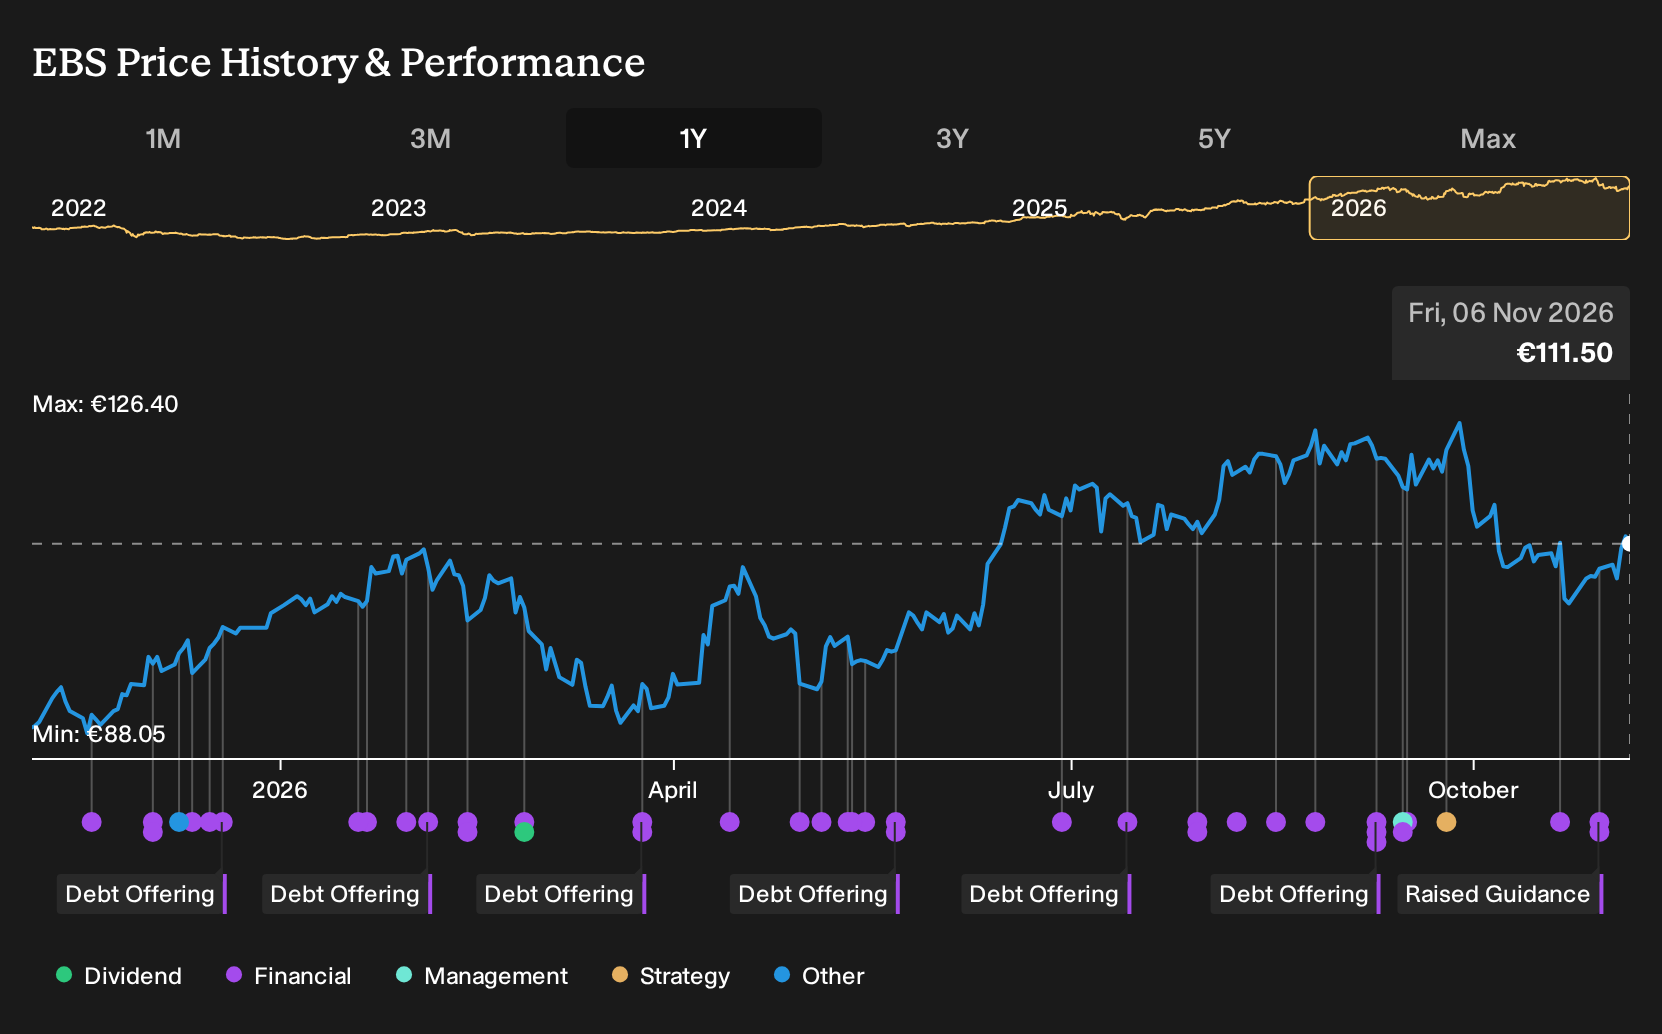
- Erste Group Bank reported Q3 2026 net income of €1,121 million and basic EPS of €2.74, with nine month net income of €3,095 million and EPS of €7.37, and also raised full year 2026 net interest income guidance excluding Erste Bank Polska to growth of more than 6%.
- The combination of higher earnings and upgraded guidance reflects how Erste Group Bank is using volume trends and the current interest rate backdrop to support its income mix across its Central and Eastern European footprint.
- The next step is to examine how Erste Group Bank's updated guidance and earnings strength could influence the investment narrative for long term holders.
Scan beyond Erste Group Bank and compare it with a curated list of solid balance sheet and fundamentals (192 results) that could benefit from similar earnings resilience and interest rate tailwinds.
Erste Group Bank Investment Narrative Recap
To own Erste Group Bank, you need to be comfortable with a simple idea. The group is a leveraged play on Central and Eastern Europe banking demand, supported by a larger Polish presence and heavy use of digital channels like George to keep costs in check. The raised net interest income guidance points to management seeing the operating backdrop as supportive, although that does not change the basic thesis.
The near term swing factor is still how well Erste Bank Polska is absorbed into group systems, while loan books in markets such as Romania and Hungary hold their credit quality. The biggest current risk sits with banking taxes and levies across the region, and any weaker conditions in markets like Romania feeding into higher impairments.
The most relevant update here is the decision on 30 October 2026 to lift full year 2026 net interest income guidance, excluding Erste Bank Polska, to growth of more than 6%. That sits alongside Q3 2026 net income of €1,121 million and nine month net income of €3,095 million, with EPS figures of €2.74 and €7.37 respectively.
For you as a shareholder, this pairing of upgraded guidance and reported profitability ties directly into the main catalysts. A larger Polish footprint, an ongoing fee income focus and broad use of the George platform all rely on capital and earnings capacity to keep growing. Banking taxes, bad loan coverage of 68% and a 2.2% bad loan ratio remain important watchpoints against that story.
Erste Group Bank's narrative projects €18.0b revenue and €5.1b earnings by 2029. This implies 11.2% yearly revenue growth and an earnings increase of about €1.4b from €3.7b today.
Uncover how Erste Group Bank's fair value indicates a 16% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One bullish twist in the alternate view is the focus on fee income and digital distribution at Erste Group Bank. The most optimistic analysts were already assuming revenue of €19.8b and earnings of €6.0b by 2029 before this earnings call and guidance upgrade. You should expect those forecasts to be revisited as opinions adjust, and use the spread in views to test your own assumptions.
Explore 4 other Erste Group Bank fair value estimates, including one that suggests as much as 112% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your Erste Group Bank research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Erste Group Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Erste Group Bank's overall financial health at a glance.
Looking for more investment ideas beyond Erste Group Bank?
If you want to stress test your thesis on Erste Group Bank, compare it with other businesses that share similar strengths in balance sheet quality, income generation or resilience to shocks. The Simply Wall St Screener can help you quickly surface a shortlist that fits the kind of profile you are looking for.
- For investors who want potential mispricing coupled with quality fundamentals, start with a curated set of 581 high quality undiscovered gems that may not yet be widely followed by the market.
- If capital preservation sits high on your priority list, filter for businesses with steadier profiles using a tailored view of 209 resilient stocks with low risk scores that screens for resilience first and returns second.
- Income focused investors can immediately zero in on companies offering stronger yields by running a custom search built around 228 dividend fortresses that highlights payout potential and consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com