
ICON (ICLR) Just Gave Investors Something To Think About
ICON (NasdaqGS:ICLR) just flipped its earnings story. Third quarter basic earnings per share from continuing operations came in at US$1.59, compared with a basic loss of US$3.67 a year earlier.
The earnings swing arrives as ICON’s share price has gained 24.7% over the past month and 23.3% over 90 days, while the one year total shareholder return of 28.7% contrasts with a three year total shareholder return that is down 20.1%, hinting at momentum rebuilding after a weaker period for long term holders.
Scan how ICON compares with other contract research and healthcare specialists by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) in similar niches.
The rebound in ICON’s earnings and share price sets the stage for a tougher call. After this run, does the risk reward still tilt toward buyers, or has the easy upside already been claimed?
Most Popular Narrative: 9% Undervalued
ICON last closed at $204.74, while the most followed narrative pegs fair value at $225.12. This frames the recent earnings rebound as part of a broader recovery story rather than a one quarter blip.
The main factor that has to go right is that ICON converts strong net book-to-bill momentum and new AI and lab investments into healthier direct fee growth and a gradual rebuild of adjusted EBITDA margins, despite mix pressure from pass-throughs and FSP work.
Operational standardization and process streamlining now include digitized protocols and tools such as Meridian and Orbis. These are being applied across monitoring and study execution and could support gradual improvement in adjusted EBITDA margins and earnings as productivity gains accumulate.
See why 13 investors see ICON as 9% undervalued.
Result: Fair Value of $225.12 (UNDERVALUED)
Still, ICON’s story could change quickly if accounting control concerns resurface or if ongoing margin pressure from pass through and FSP work drags on profitability.
Find out about the key risks to this ICON narrative.
Another View: ICON On Earnings Versus Price Tag
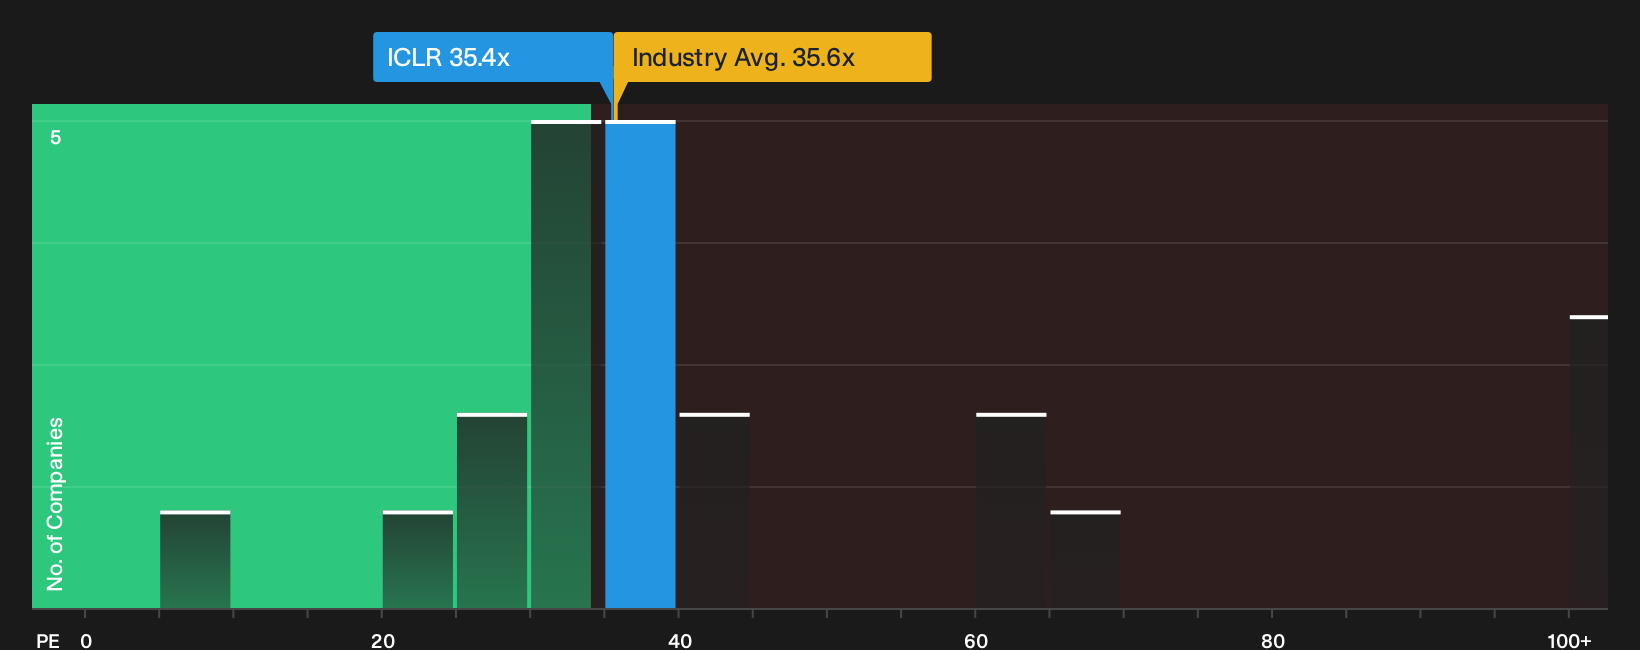
The narrative around ICON leans on a fair value of $225.12, yet the current P/E of 35.4x tells a slightly different story. That multiple sits below peers at 43x, but above a fair ratio of 28.5x, which hints at less room for error if sentiment cools.
To see how those P/E gaps could matter if the market shifts closer to the fair ratio, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in ICON’s story so far. If you want your verdict to rest on more than headlines, weigh both sides quickly and review the 3 key rewards and 2 important warning signs for a fuller picture.
Looking for more investment ideas beyond ICON?
If ICON’s story caught your attention, do not stop here. Broaden your watchlist now and give yourself more options before the next big move appears.
- Target undervalued opportunities early by scanning the 38 high quality undervalued stocks that pair quality fundamentals with compressed valuations.
- Lock in income focused candidates by reviewing the 7 dividend fortresses built around higher yielding businesses.
- Protect your downside first and then build from there by checking the 31 resilient stocks with low risk scores that emphasise resilience over speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com