
3 Biotech Stocks With Revenue Growth Up To 30%
As markets brace for possible Fed rate hikes, investors are hunting for areas that are less tied to the economic cycle and more driven by scientific progress. That is where higher risk, higher potential biotech stocks come in, especially those with more reasonable balance sheets. This article walks through three such biotech stocks from our screener to help you focus your research on ideas with some financial cushioning built in.
The three biotech stocks below are just a starting sample. The full screen surfaced 87 more companies with equally compelling narratives that are not covered here. If you want to identify and analyze higher conviction biotech ideas with stronger balance sheets and clearer stories, head straight to the Biotech Stocks screener.
Amgen (AMGN)
Overview: Amgen is a large biopharmaceutical group that discovers, develops, manufactures, and markets biologic drugs for serious autoimmune, cardiovascular, cancer, and rare diseases. This anchors its role in the Biotech Stocks theme.
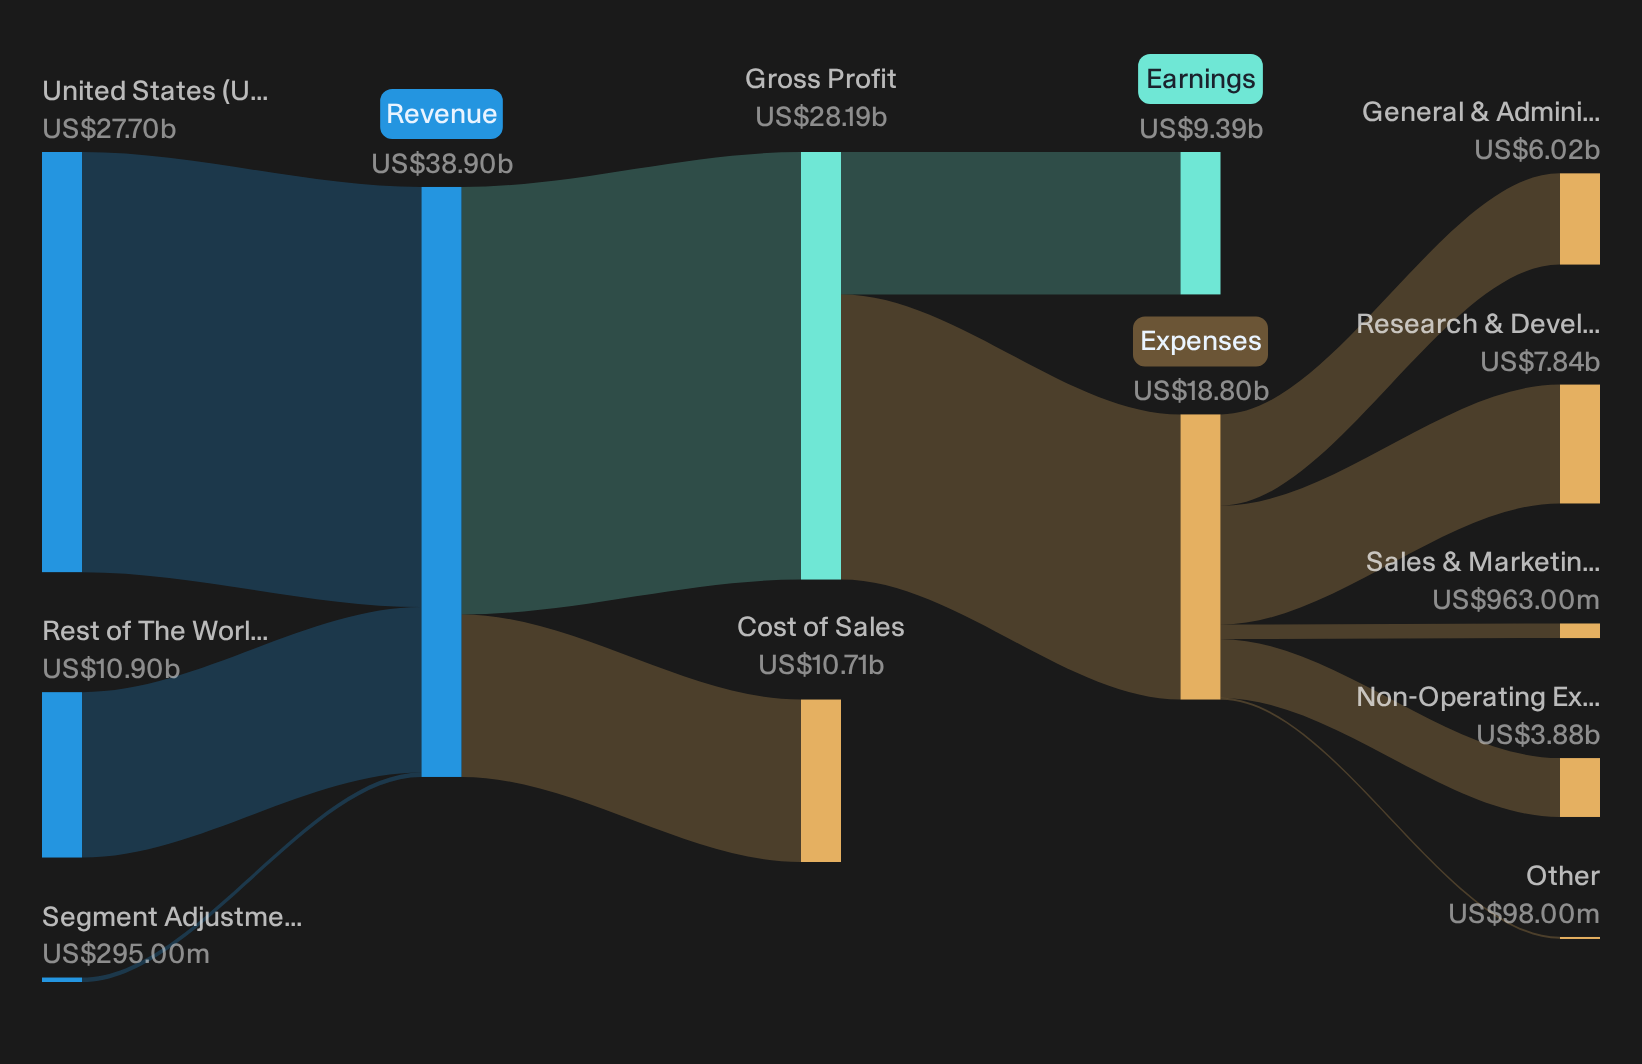
Operations: Amgen generates about US$38.9b from Human Therapeutics, with around US$27.7b from the United States and US$10.9b from the rest of the world.
Market Cap: US$249.0b
For this screener, Amgen matters because its biologic medicines like ENBREL, PROLIA, REPATHA, TEPEZZA, BLINCYTO, KYPROLIS, and LUMAKRAS are the main engines behind a mature, cash-generative biotech portfolio that still carries meaningful upside potential alongside the usual clinical and pricing risks.
"Dividend covered about 2x by free cash flow; debt from the Horizon deal is being paid down."
What really moves the needle for future returns is how one pressure on that biotech engine plays out beneath the headline numbers.
That pressure point is exactly where the story gets interesting, and the full narrative for Amgen examines how Amgen’s cash, pipeline and debt profile could be quietly changing expectations.
Eli Lilly (LLY)
Overview: Eli Lilly develops and sells biotech-driven medicines for diabetes, obesity, cancer, and immune disorders, anchored around biologic and novel therapies worldwide.
Operations: Eli Lilly generates about US$86.5b from pharmaceutical products, with roughly US$54.5b from the U.S. and US$32b from international markets.
Market Cap: US$1,206.1b
Eli Lilly fits this biotech screen because its GLP-1 and oncology biologics connect cutting edge science with a balance sheet that can support large trials, global launches, and ongoing manufacturing build outs.
"Mounjaro (for type 2 diabetes) and Zepbound (obesity) each grew rapidly in 2024, with analysts projecting Mounjaro sales of $18.4B in 2025 and $22.8B in 2026, and Zepbound jumping from $4.9B (2024) to $12.5B in 2025 (and $18.1B in 2026)."
What happens to Eli Lilly’s margins and investor enthusiasm depends heavily on how one unseen pressure on that GLP-1 franchise resolves.
That pressure point is exactly where the full narrative for Eli Lilly shows how Eli Lilly’s GLP-1 surge could be masking capacity constraints, pricing shifts, and fresh sources of upside.

Arrowhead Pharmaceuticals (ARWR)
Overview: Arrowhead Pharmaceuticals develops RNA interference medicines, with late stage drugs like plozasiran and zodasiran targeting hard to treat cardiometabolic conditions.
Operations: Arrowhead currently reports about US$669 million in Nanotechnology related revenue, all generated from customers in the United States.
Market Cap: US$8.2b
Arrowhead Pharmaceuticals gives this Biotech Stocks screen a pure play RNAi angle by pairing advanced cardiometabolic trials with a balance sheet that aims to stretch funding across multiple late stage shots on goal.
"Arrowhead Pharmaceuticals has acquired an FDA Priority Review Voucher for plozasiran in severe hypertriglyceridemia and expects a second quarter 2027 launch after submitting the supplemental filing by year end 2026."
The key factor that shapes the eventual payoff is how a hard to predict shift in real world treatment patterns interacts with those launch plans.
That launch question is exactly where the full narrative for Arrowhead Pharmaceuticals shows how Arrowhead Pharmaceuticals’ RNAi pipeline could turn today’s priority voucher into accelerating long term cardiometabolic momentum.

Seeking Alternatives Before The Crowd?
Fresh momentum often starts quietly, then moves fast once early buyers begin building positions. Before these ideas stop flying under the radar, consider reviewing them now.
- Look for potential breakouts in tiny companies that already show real profitability by scanning 40 profitable AI stocks that aren't just burning cash before momentum traders increase their activity.
- Explore opportunities around long term demand for critical resources by reviewing the curated 16 top copper producer stocks while price dislocations may still be relevant.
- Evaluate resilient cash generators with staying power by checking the hand picked list of solid balance sheet and fundamentals (25 results) before more defensive capital shifts into similar profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com