
Did Capital Returns Just Shift U.S. Bancorp (USB) Stock Narrative?
- U.S. Bancorp recently completed and announced a series of senior unsecured medium term note offerings across US dollar and Canadian dollar markets, including fixed and fixed to floating coupons, with maturities stretching into the 2040s.
- The launch of U.S. Bancorp Global Funds alongside these bond issues points to a dual funding and distribution push that links balance sheet financing with a new Ireland based U.S. Treasury liquidity vehicle for offshore clients.
- We will now look at how U.S. Bancorp's renewed capital return focus may reshape its broader investment narrative for shareholders.
Compare U.S. Bancorp's funding and capital return story with banks that also pair balance sheet strength and payout potential in our hand picked 38 high quality undervalued stocks.
U.S. Bancorp Investment Narrative Recap
To own U.S. Bancorp, you need to believe its mix of fee driven businesses, capital markets expansion and tech investment can keep supporting earnings even as banking stays highly competitive. The recent run of senior unsecured note deals and preferred stock designations points to active balance sheet management rather than a shift in that core thesis.
The near term swing factor remains how quickly management leans back into its 70% to 75% capital return framework once capital targets are met. The biggest risk still sits in credit quality, especially commercial real estate, where any reset in property values would compete directly with buybacks and dividends for capital.
The launch of U.S. Bancorp Global Funds and the Ireland based USD Treasury liquidity fund ties directly into this funding story. The bank is raising term wholesale debt in both US and Canadian markets while also building an offshore vehicle that can attract third party assets and fee income linked to U.S. Treasuries.
For you, that pairing matters because it links catalysts on both sides of the balance sheet. A deeper international liquidity platform can support deposit and fee diversification, while the stack of callable senior notes gives U.S. Bancorp more tools if credit costs rise or digital competitors pressure payments related revenue.
U.S. Bancorp's analyst narrative points to forecast revenue of US$37.8b and projected earnings of US$9.1b by 2029, based on an assumed 10.7% yearly revenue growth rate. That earnings path implies an increase of about US$1.1b from current earnings of US$8.0b to the 2029 consensus figure.
Uncover why U.S. Bancorp's fair value indicates a 15% potential upside to its current price that could narrow quickly.
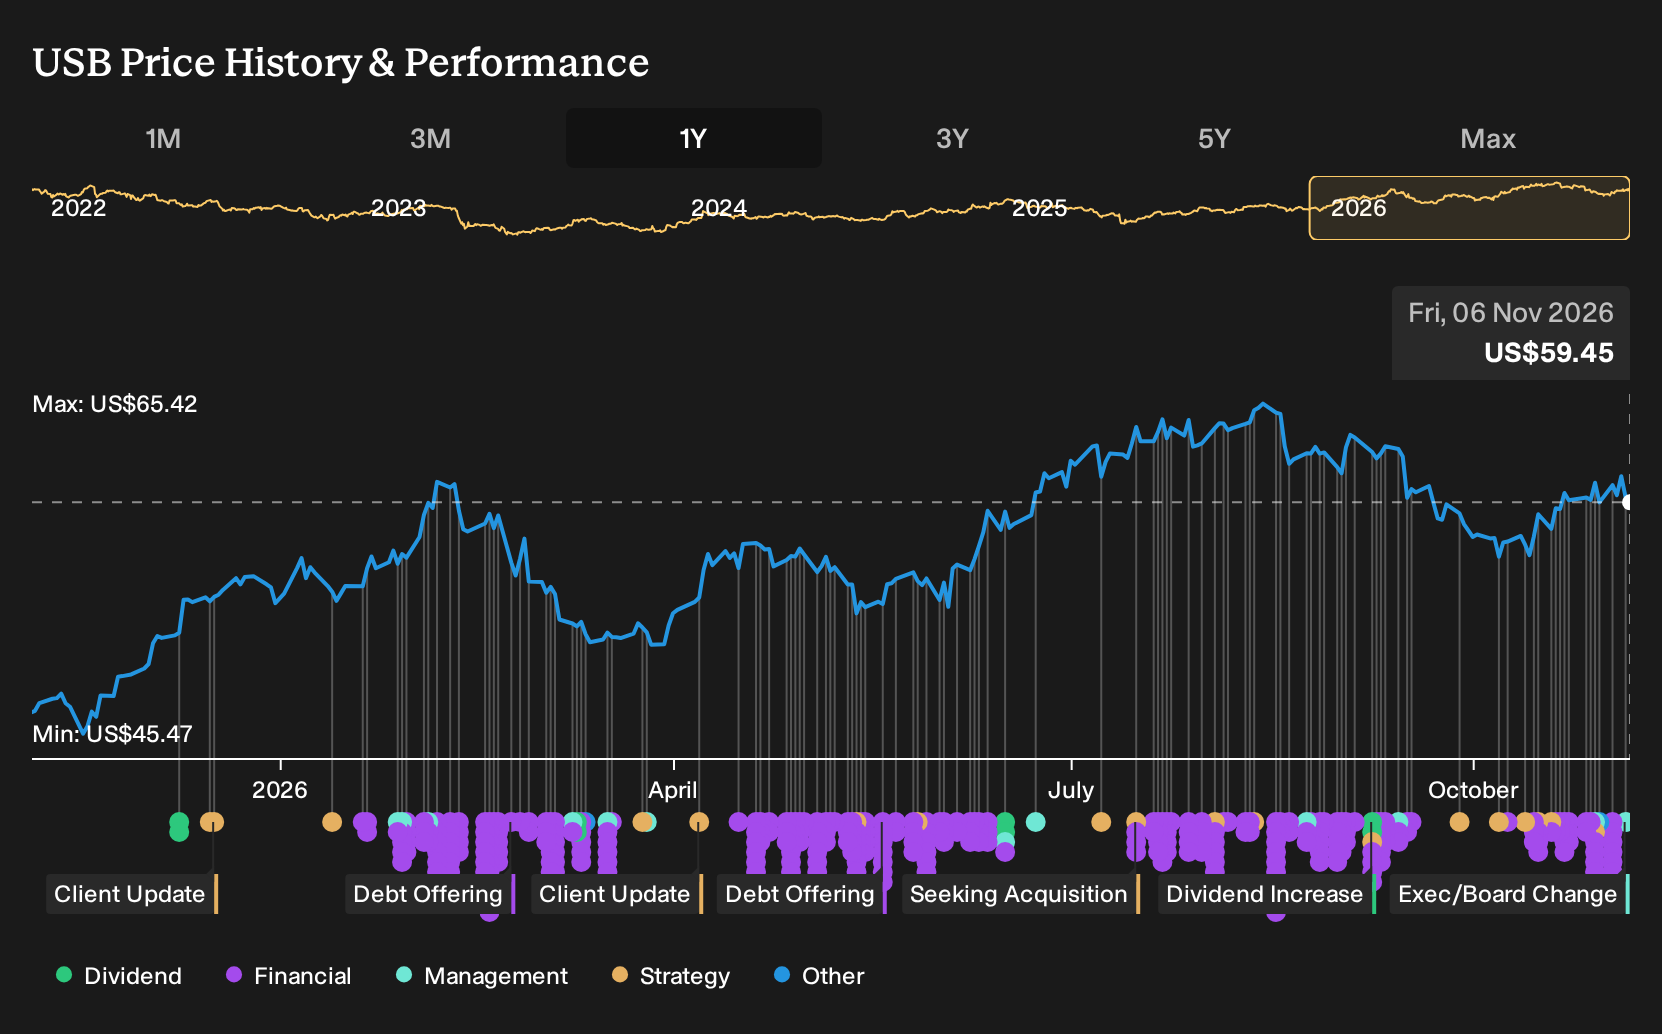
Exploring Other Perspectives
You have five fair value estimates from the Simply Wall St Community, ranging from US$58.09 up to about US$98.42 per share, so opinions on U.S. Bancorp are spread widely. Set those against fresh leadership changes in risk and payments, plus a packed calendar of fixed income offerings, and you see why viewpoints can diverge. Explore those alternative takes before leaning on any single narrative.
Explore 4 other U.S. Bancorp fair value estimates, including one that suggests it could be worth just $58.09.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your U.S. Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for U.S. Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate U.S. Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond U.S. Bancorp?
Once you have a handle on U.S. Bancorp, it can help to widen the lens and compare it with other companies that match the kind of risk, income, or quality profile you care about most. The Simply Wall St Screener can surface a mix of different opportunities so you can build a watchlist that truly fits your style.
- If you want potential upside paired with stronger fundamentals, sort through a curated set of quality candidates via the 19 high quality undiscovered gems.
- For investors who put capital preservation first, filter for steadier businesses with more resilient profiles by using the 31 resilient stocks with low risk scores.
- If balance sheet strength is non negotiable for you, focus your research on companies screened for financial resilience with the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com