
Marqeta (MQ) Could Be 10% Undervalued After Profit And 2026 Guidance
Marqeta earnings jump and guidance set the tone
Marqeta (MQ) just posted third quarter results that moved from a net loss to a profit, with higher sales and fresh revenue guidance for both the fourth quarter and full year 2026.
Marqeta shares have gained momentum in recent months, with a 90 day share price return of 19.17% and a 1 year total shareholder return of 0.38%, following a much weaker 3 year total shareholder return that declined 20.83%.
Scan how Marqeta stacks up against other potential breakout stories by reviewing our hand picked list of 19 high quality undiscovered gems in the same session.
The question now is whether Marqeta’s recent share move mainly mirrors a business that just swung to profit with fresh guidance, or reflects a sentiment reset that the current valuation already prices in.
Most Popular Narrative: 10% Undervalued
Marqeta last closed at $18.59, while the most followed narrative sets fair value at $20.65, using a 7.31% discount rate to bring expected cash flows back to today. That gap frames a view that the recent swing to profitability and updated guidance may not fully align with where the market currently prices the stock.
Marqeta is positioned to capitalize on the rapid growth of global digital payments and the expansion of embedded finance as major enterprises and fintechs seek to launch new card-based offerings, driving sustained TPV and revenue growth through increasing adoption of its platform worldwide, which can support future earnings.
See why 14 investors see Marqeta as 10% undervalued.
Result: Fair Value of $20.65 (UNDERVALUED)
Still, concentrated reliance on a few large customers and pressure on gross profit take rates could quickly challenge the Marqeta upside story that investors are leaning on.
Find out about the key risks to this Marqeta narrative.
Another View: What Multiples Say About Marqeta
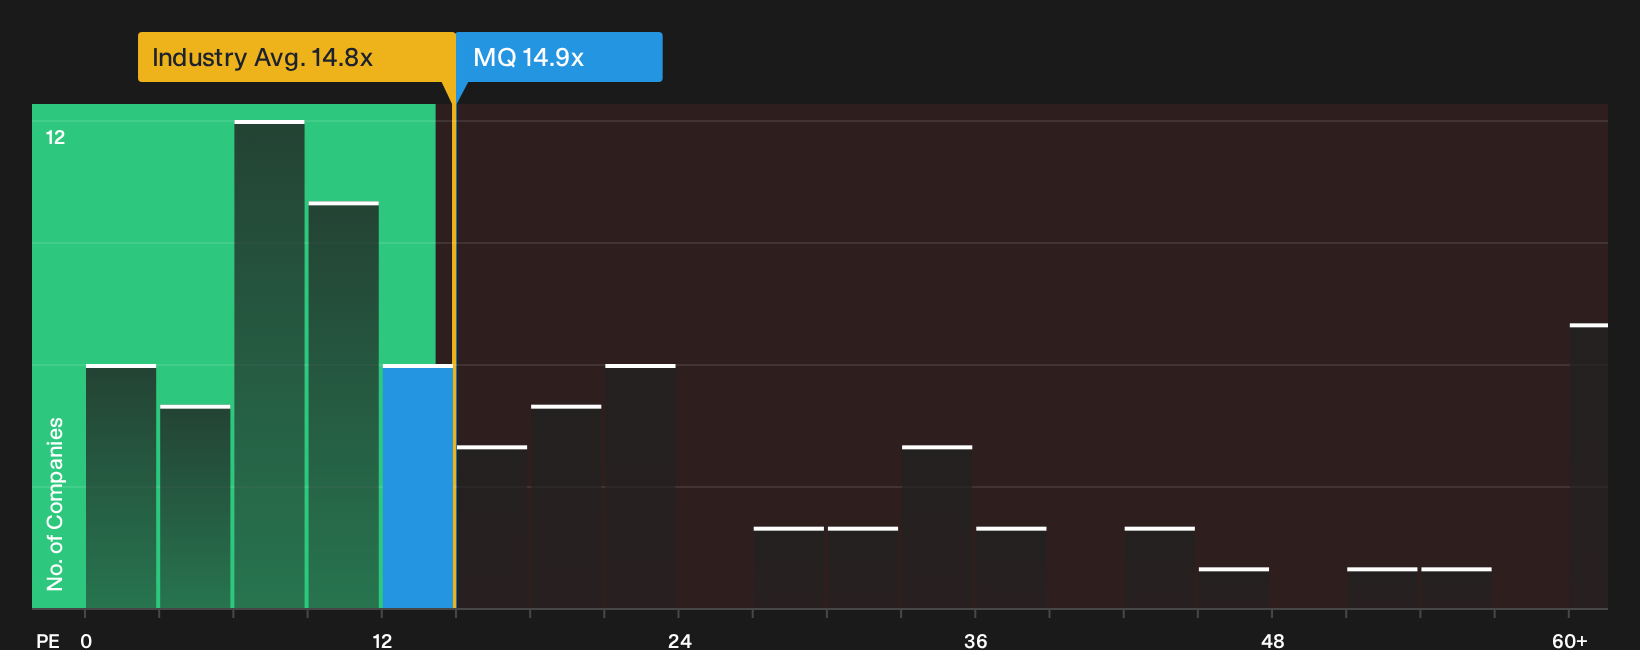
Marqeta might look 10% undervalued against the $20.65 fair value in the leading narrative, yet the market’s P/E tells a tougher story. The stock trades on 14.9x earnings versus 14.3x for the US Diversified Financial industry, 8.9x for peers, and a fair ratio of 6.2x, which points to valuation risk if sentiment cools.
Our preferred multiple work implies the market could shift toward that lower fair ratio level if expectations reset, especially with earnings forecasts calling for declines over the next three years. The open question for investors is whether to lean more on the narrative’s long term scenario or on what today’s earnings multiples already signal about downside.
See what the numbers say about this price, find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Here is how Marqeta’s current earnings multiple compares with its industry and peers visually.
Next Steps
If this Marqeta story feels finely balanced between promise and pressure, move quickly, review the full data, and weigh both sides. To see the mix of potential upsides and the key issues investors are watching, start with 2 key rewards and 2 important warning signs.
Looking for more Marqeta sized opportunities?
You have already seen how quickly sentiment can shift around Marqeta. Do not stop here when a broader watchlist could sharpen your next move.
- Target potential mispricings early by scanning a 38 high quality undervalued stocks that couples solid fundamentals with attractive entry points.
- Strengthen the defensive side of your portfolio by filtering for a list of solid balance sheet and fundamentals (25 results) that can better handle tougher conditions.
- Boost your income focus by zeroing in on a 7 dividend fortresses built around higher yields and staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com