
Brookfield Wealth Solutions (BNT) Could Be 26% Overvalued After Annuity Growth And Just Group Deal
Brookfield Wealth Solutions (BNT) drew fresh attention after reporting high profit per employee on a platform overseeing more than US$200 billion in assets, supported by strong annuity inflows and the acquisition of UK based Just Group.
Brookfield Wealth Solutions has experienced a mixed share price trajectory, with a 7-day share price return of 5.38% and a 30-day share price return of 11.49% indicating short-term momentum. However, the year-to-date share price return is down 11.48% and the 1-year total shareholder return is down 9.03%.
Scan for other insurers showing similar traction in annuities and balance sheet strength by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) alongside Brookfield Wealth Solutions.
Brookfield Wealth Solutions now trades at a sizeable discount to one intrinsic value estimate after a sharp short term rebound. Is that pricing caution about earnings quality, or a misread of what this platform is actually worth?
Preferred P/E of 118x for Brookfield Wealth Solutions: Is it justified?
On simple earnings math, Brookfield Wealth Solutions looks expensive. The stock closed at $41.32 while trading on a P/E of 118.2x, compared with a peer average of 18.1x and a US Insurance industry average of 11.4x.
The P/E ratio compares what investors are paying per share to the earnings generated per share. For an insurer like Brookfield Wealth Solutions, it reflects how much faith the market has in the durability and growth of future profits relative to current reported income.
Here, the earnings picture is soft. Net income sits at $125.0m on $11.85b of revenue, which translates to a 1.1% net margin that has narrowed from 5.5% last year. Earnings declined 84.2% over the past year and return on equity is low at 1%. Against that backdrop, a triple digit P/E signals that buyers are paying a very full price for each dollar of current profit.
Compared with both the direct peer group at 18.1x and the broader US Insurance sector at 11.4x, Brookfield Wealth Solutions trades on a far richer earnings multiple. The market is assigning a premium that is far above sector norms, which points to a valuation that is tough to justify on recent profitability alone.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 118.2x (OVERVALUED)
Still, the story around Brookfield Wealth Solutions can change quickly if annuity inflows slow or if the quality of earnings comes under renewed scrutiny after such a rich P/E.
Find out about the key risks to this Brookfield Wealth Solutions narrative.
Another view on Brookfield Wealth Solutions’ value
The P/E story says Brookfield Wealth Solutions looks expensive, while the SWS DCF model points the other way. On that framework, the shares around $41.32 trade above an estimated future cash flow value of $32.89, which implies the stock screens as overvalued on cash generation as well.
When earnings multiples and discounted cash flows both lean cautious, it raises a simple question for investors: Is the recent enthusiasm about the annuity platform running ahead of the cash that Brookfield Wealth Solutions is actually expected to produce?
Look into how the SWS DCF model arrives at its fair value.
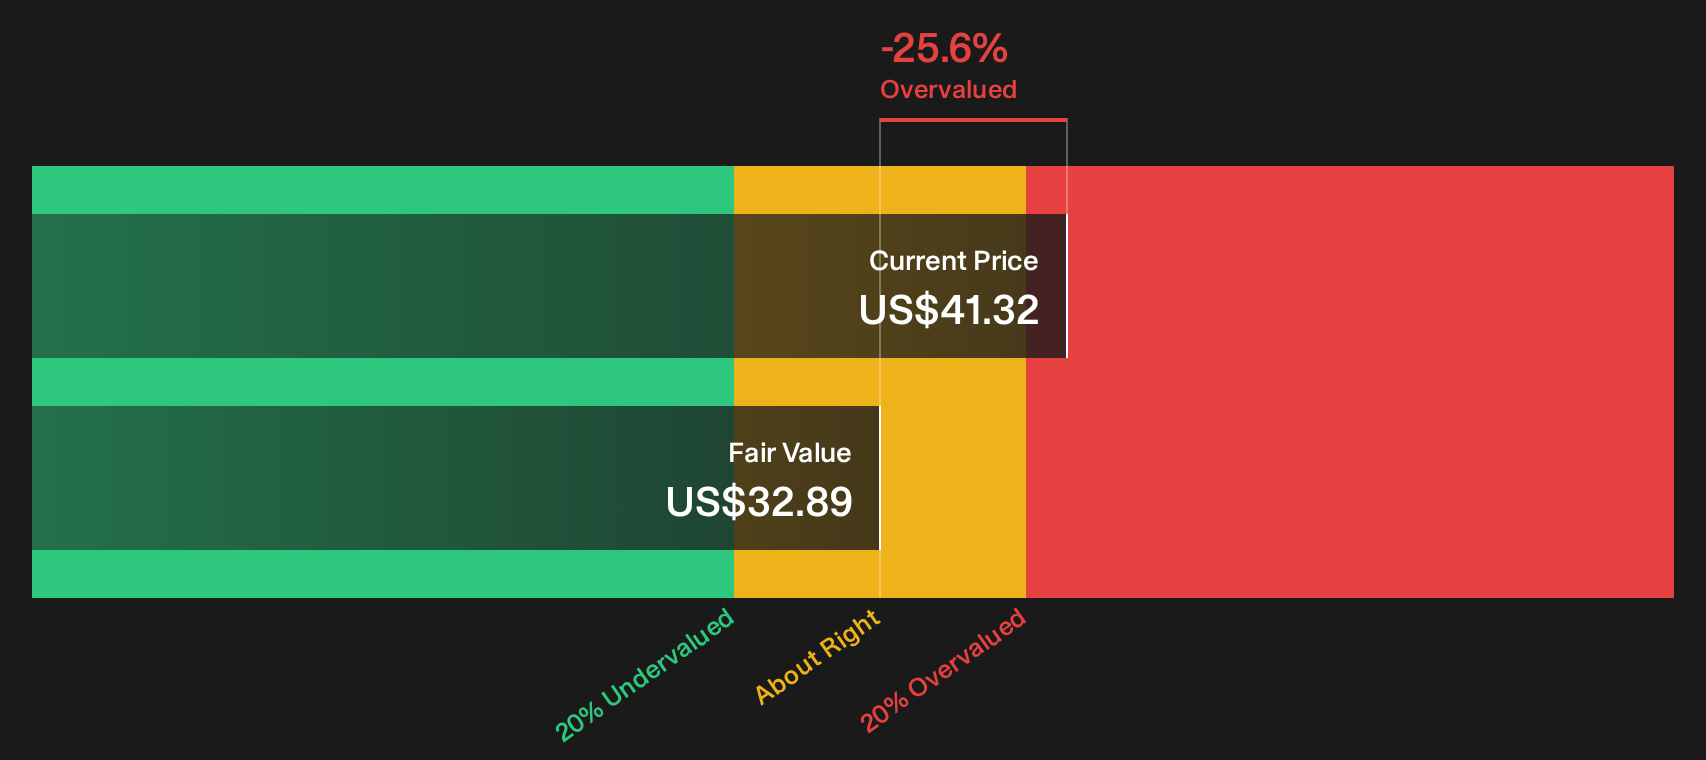
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brookfield Wealth Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Brookfield Wealth Solutions feels hard to weigh, use the full data set to stress test your own thesis. To understand what could go wrong as well as what might go right, start by reviewing the 2 important warning signs.
Looking for more investment ideas beyond Brookfield Wealth Solutions?
If Brookfield Wealth Solutions has you rethinking where risk and reward sit in your portfolio, do not stop here. Use the screeners below to pressure test fresh ideas and avoid missing opportunities that fit your style.
- Target potential value upside by running through the 38 high quality undervalued stocks that share strong fundamentals and may offer more compelling entry points.
- Prioritise resilience first and sift through the 31 resilient stocks with low risk scores that carry lower risk scores and steadier financial profiles.
- Hunt for overlooked potential and scan the 19 high quality undiscovered gems that combine quality metrics with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com