
Is Royal Gold (RGLD) Undervalued As Record Q3 Results Lift Confidence?
Royal Gold (RGLD) has become a talking point after reporting record Q3 2026 results, with revenue of about US$465 million, strong operating cash flow and a debt free balance sheet capturing investor attention.
Royal Gold’s recent rally has been sharp, with a 16.19% 7 day share price return and a 20.21% year to date move that coincides with record Q3 results and reaffirmed 2026 volume guidance for gold, silver and copper.
The trend has been in place for a while, reflected in a 12.52% 30 day and 13.53% 90 day share price return. Longer term total shareholder returns of 52.45% over 1 year and 163.80% over 5 years point to momentum that has been building rather than fading.
Capture this breakout in context by comparing it with other precious metal plays using the 34 elite gold producer stocks, focusing on quality, balance sheets and recent momentum.Royal Gold now pairs record sales, strong cash generation and no debt with a share price that has already run hard. The next step is simple: Are you paying up for quality or still getting a deal?
Most Popular Narrative: 14% Undervalued
Royal Gold last closed at $265.81, while the most followed narrative pegs fair value closer to $309.83. This implies a meaningful valuation gap that leans heavily on its portfolio depth and cash flow profile.
The main thing that has to go right is that Royal Gold continues to convert its option rich development pipeline into producing streams while maintaining disciplined capital allocation, including rapid debt repayment and ongoing dividend increases.
The current valuation implies that the market discounts Royal Gold’s multi decade growth pipeline and high margin cash flows, which supports the view that the stock may be undervalued and that the setup may be favorable for investors.
See why 88 investors see Royal Gold as 14% undervalued.
Result: Fair Value of $309.83 (UNDERVALUED)
Still, that narrative depends on Royal Gold meeting analyst earnings targets and on recent insider selling not signaling lower confidence, both of which could easily reduce the perceived upside.
Find out about the key risks to this Royal Gold narrative.
Another View: Royal Gold Looks Expensive On Earnings
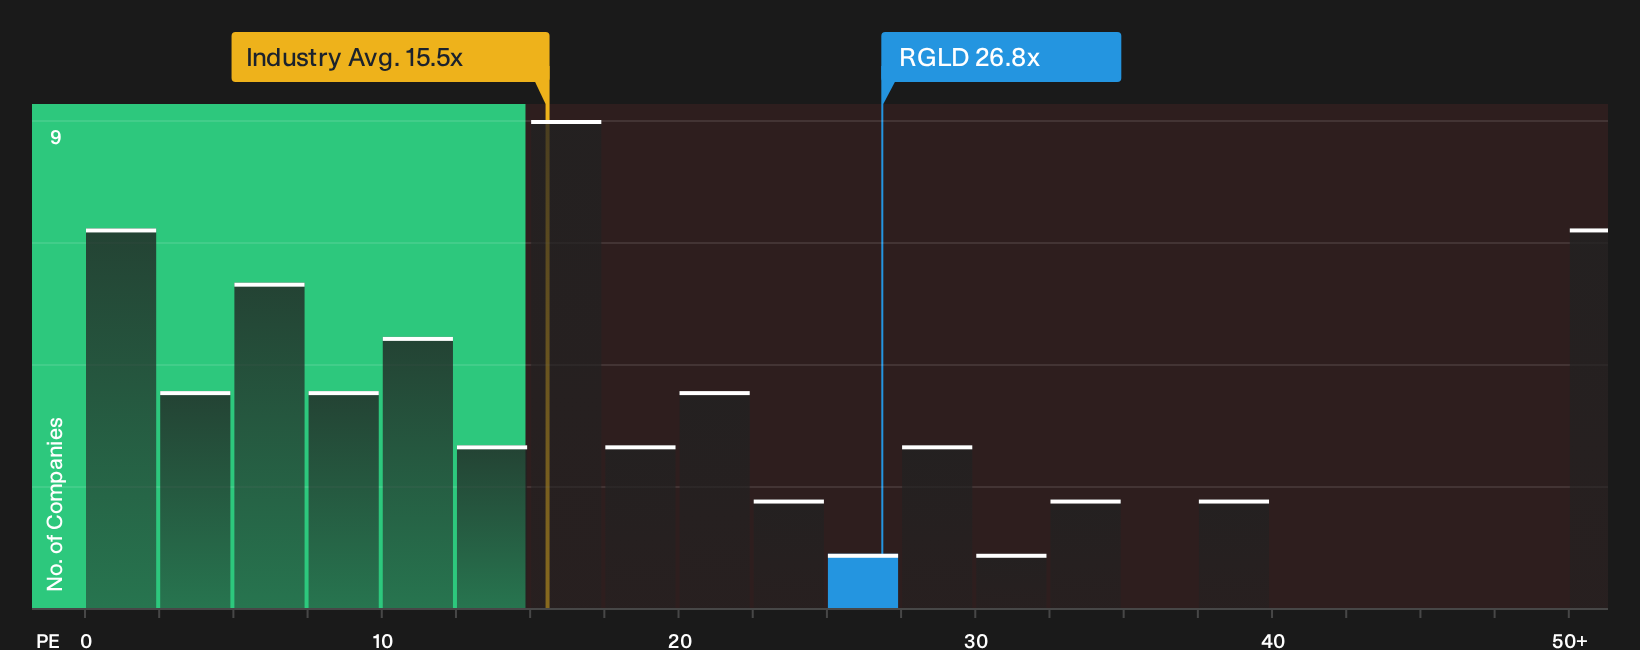
The fair value narrative leans on future cash flows and growth, but today Royal Gold trades on a P/E of 26.8x. The fair ratio is 20.4x, while the US Metals and Mining group sits near 15.5x and peers around 16.4x. That is a rich premium. Is the quality story strong enough to justify it?
For a closer look at how this earnings based view stacks up against market history and similar businesses, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages around Royal Gold have you on the fence, take a moment to review the numbers for yourself, then weigh up the 2 key rewards
Looking for more Royal Gold style investment ideas?
Do not stop with Royal Gold. Put the broader market to work for you by scanning other opportunities that match your risk, income and value preferences.
- Target potential bargains that combine quality fundamentals with appealing pricing by starting with the 38 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies built around robust payouts using the 7 dividend fortresses.
- Prioritize resilience and capital protection by filtering for companies that score well on stability through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com