
3 Bank Stocks Worth Watching As Higher Interest Rates Support Margins
Rate hike odds climbing to 76%, inflation holding at 3.7% and a market fixated on every data release create a simple tension for you as an investor. Cash feels safer, yet pockets of the market can see earnings power shift as borrowing costs reset. This article walks through three stocks from our U.S. banks and insurance screener that are closely tied to this rate story and may merit closer analysis.
The stocks highlighted below are just a small sample, and the full screen surfaced 39 more U.S. banks and insurers with equally compelling rate-sensitive stories that are not covered in this article.
If you want to identify and analyze the highest-conviction ideas from this broader universe, head straight into the U.S. Financials – Banks and Insurance Benefiting from Higher Interest Rates screener.
Fifth Third Bancorp (FITB)
Fifth Third Bancorp is one of the clearest rate plays in this screener, with a deposit rich franchise that can react directly as the Fed keeps short term borrowing costs higher for longer.
Fifth Third Bancorp is a large regional U.S. lender with Commercial Banking generating about US$5.2b of revenue, Consumer and Small Business Banking about US$5.5b, and Wealth and Asset Management about US$1.0b. This provides a diversified set of interest and fee streams on a roughly US$47.9b market cap platform.
Growth in payments and deposit rich platforms such as Direct Express and Newline, which together contribute several billions of dollars of low cost deposits and rising fee revenue, gives Fifth Third Bancorp additional levers to support net interest income and noninterest income over time.
The real swing factor is whether one pressure on funding costs quietly reshapes how much of that higher rate income ultimately reaches the bottom line.
That funding squeeze is the crux, and the full narrative for Fifth Third Bancorp explains how Fifth Third Bancorp’s deposit engine, rate sensitivity and credit risks could be reshaping its earnings power.

United Community Banks (UCB)
United Community Banks plugs directly into the higher rate story, with a balance sheet built around loans and deposits that can reprice as the Fed moves. This makes its earnings engine closely tied to the same forces driving this screener.
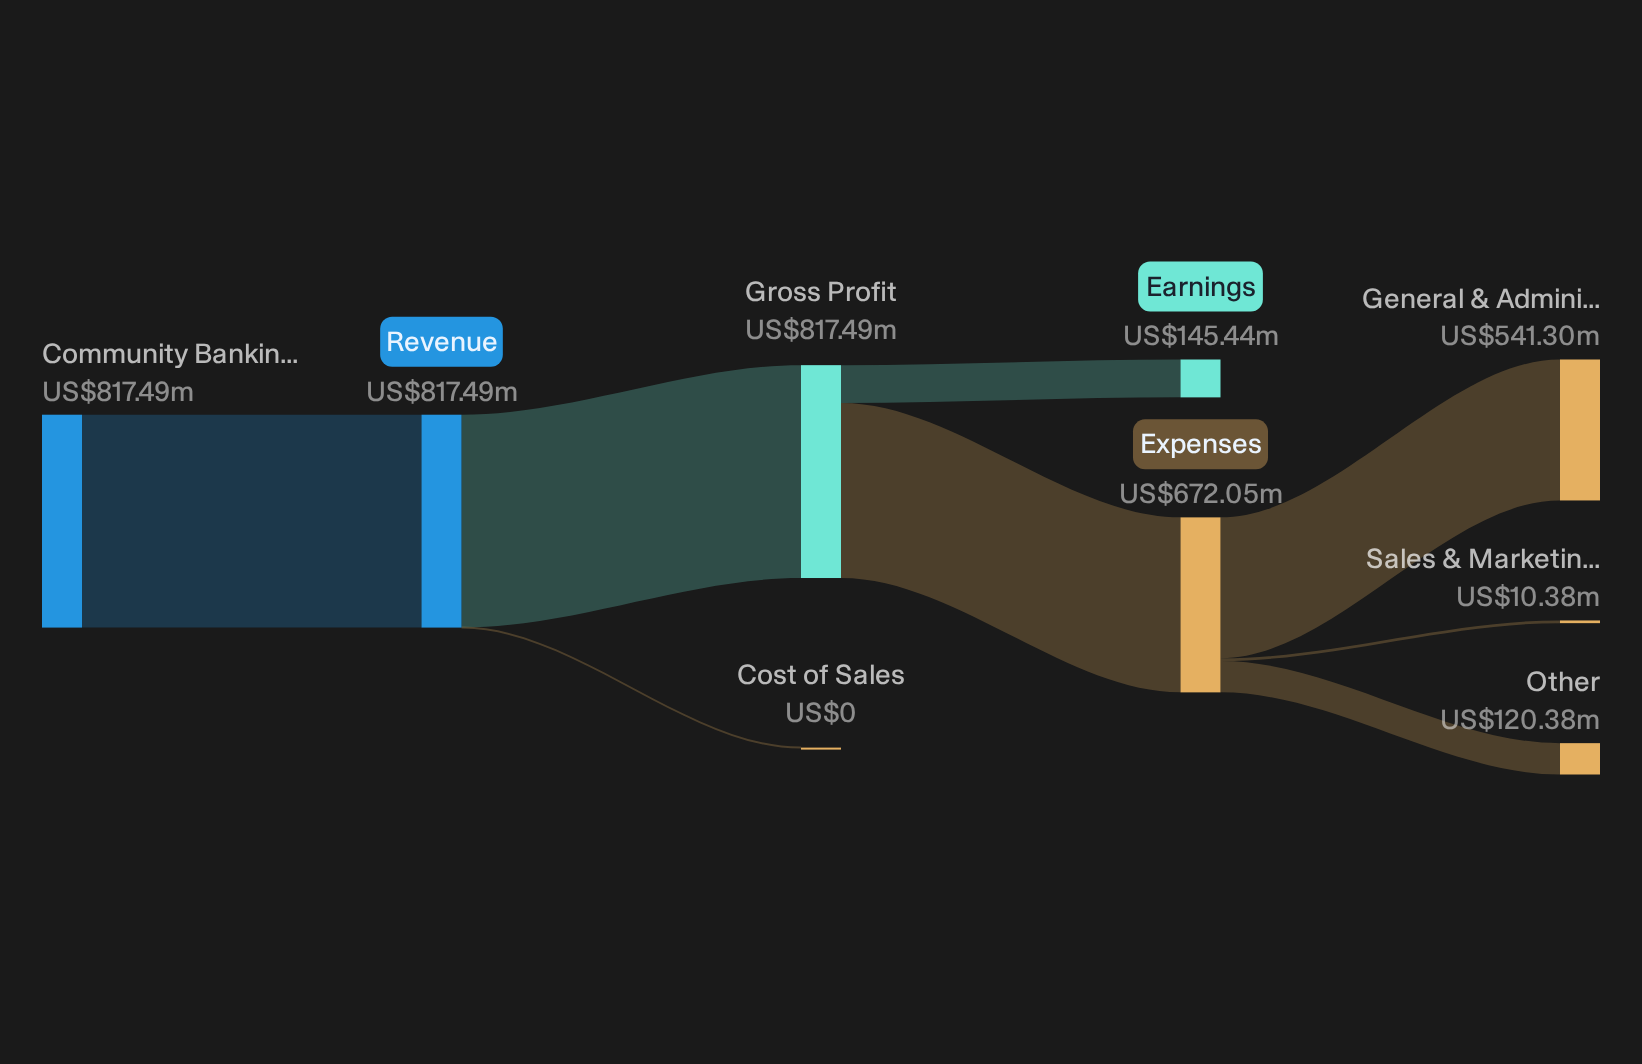
United Community Banks runs a broad community banking and wealth platform across the United States, earning about US$817 million of revenue from Community Banking and carrying a market value of roughly US$4.4b.
Active restructuring of the securities portfolio, including the sale of US$2.6b of lower yielding long duration securities and reinvestment at yields closer to 4%, is expected to add about US$40m of annual pretax spread income and support net interest margin and earnings.
The key issue is how one quiet shift in its deposit and funding mix shapes the margin story investors actually experience.
That quiet shift is exactly what the full narrative for United Community Banks unpacks, showing how deposit mix, securities reshaping and credit trends could be masking where earnings power is really heading.
Banc of California (BANC)
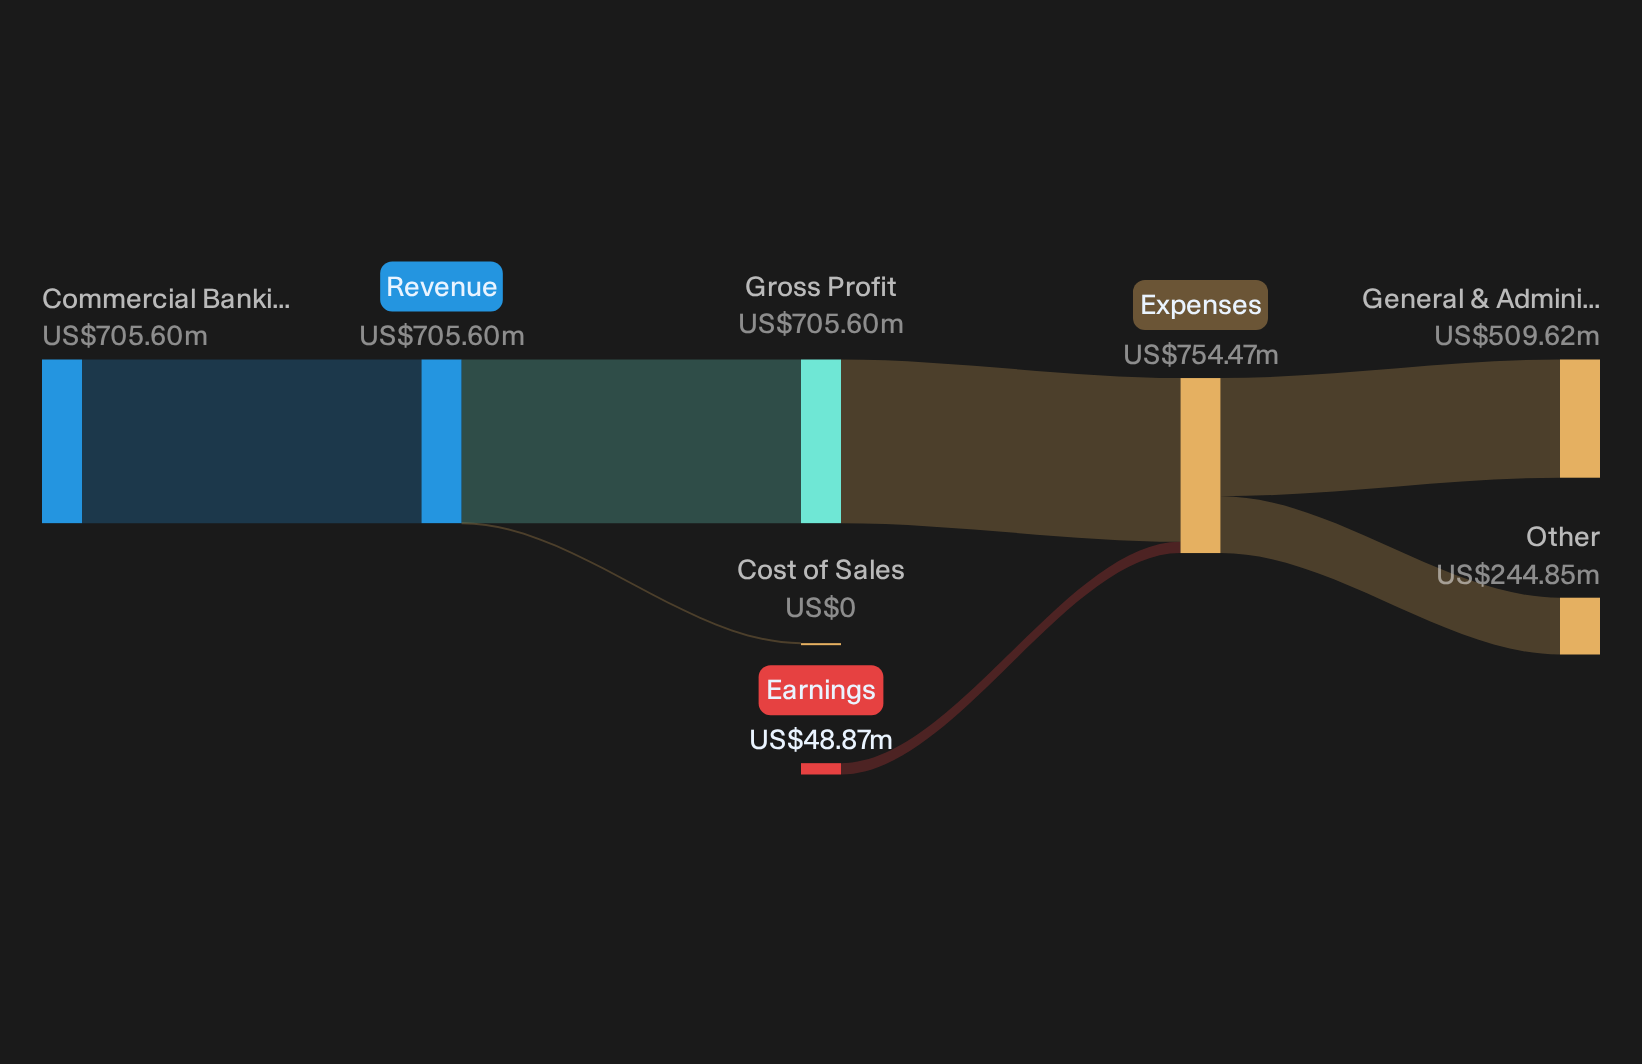
Banc of California plugs directly into the higher rate theme, since its loan and deposit book is built around commercial banking and treasury services that respond to Fed moves, with US$705.6 million of Commercial Banking revenue in the United States and a roughly US$2.8b market value.
Banc of California sits closer to the sharp end of this screener, with its balance sheet actively repositioned toward assets that can reset as policy rates shift and its funding mix under constant review.
Although Banc of California expects higher yielding reinvestment from securities repositioning and multifamily loan repricing to lift net interest margin over time, the recent net loss of $251.3 million tied to securities losses and elevated provision expense suggests that future balance sheet optimization could continue to require sizeable upfront charges that weigh on earnings and tangible book value accretion.
What happens when one quiet variable in that repricing effort moves against expectations will matter far more for future returns than any single rate decision.
When that repricing wildcard shifts, the full narrative for Banc of California shows how Banc of California’s earnings engine could be quietly resetting and where upside or risk might be building.
Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout themes, quiet momentum and under-the-radar stories can be caught early, before the crowd reacts and prices adjust. Act now.
- Target resilient income streams by scanning a curated pool of potential high-yield payers through the 7 dividend fortresses before yields drop or valuations move away.
- Hunt for early-stage compounding stories with solid finances using the curated 38 high quality undervalued stocks before the market fully prices in their strength.
- Track infrastructure behind the AI surge through the hand picked 53 AI infrastructure stocks and spot potential beneficiaries while the build out is still accelerating.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com