
Learn Why The Bull Case For Schwab Stock Could Change Following Advisor AI Rollout
- In late October 2026, Charles Schwab Corporation introduced new AI solutions for registered investment advisors inside Schwab Advisor Center and deepened its collaboration with third party tools that connect to the platform, while also forming a partnership and investment relationship with Nevis to streamline advisor workflows.
- The Nevis alliance points to Charles Schwab focusing on reducing manual operational work for RIAs, which could influence technology spending, efficiency targets, and how advisors use the firm’s custody and advice infrastructure over time.
- We will now assess how Charles Schwab's Nevis powered advisor workflow automation might affect the broader investment narrative around technology efficiency.
Scan the AI adoption trend in wealth management beyond Charles Schwab by reviewing a curated group of advisors' platform partners in our 40 profitable AI stocks that aren't just burning cash.
Charles Schwab Investment Narrative Recap
To own Charles Schwab, you need to be comfortable with a story built on scale, advice penetration and disciplined cost control. The key short term swing factor is whether expense growth, including heavier technology and AI spending, stays below revenue expansion so operating leverage is preserved as trading and advice activity move around.
The biggest near term risk is cost creep. Management is already guiding to faster expense growth for 2026, and the new AI builds sit inside that spend. If these tools do not translate into a lower cost per account or smoother advisor operations, higher outlays could bite into pre tax margins rather than support them.
The fresh AI partnership with Nevis ties directly into Schwab's push to use automation to manage scale. Management is already rolling out AI tools to tens of thousands of employees, and coders are reporting 15% to 20% productivity gains, so tighter workflow integration for advisors fits with that operational theme.
For you as an investor, the interest is simple. If Nevis powered workflows help RIAs open accounts, move assets and process service requests with fewer manual steps, that can support the catalyst of growing advice and custody revenues while containing unit costs. Execution risk sits in integration quality and adoption, especially with tech spending already elevated.
Charles Schwab's narrative projects revenues of $36.3b and earnings of $15.0b by 2029. This rests on analysts assuming 10.3% yearly revenue growth and an earnings increase of about $4.7b from $10.3b today to the $15.0b forecast for 2029.
Uncover why Charles Schwab's fair value indicates a 29% potential upside to its current price that could narrow quickly.
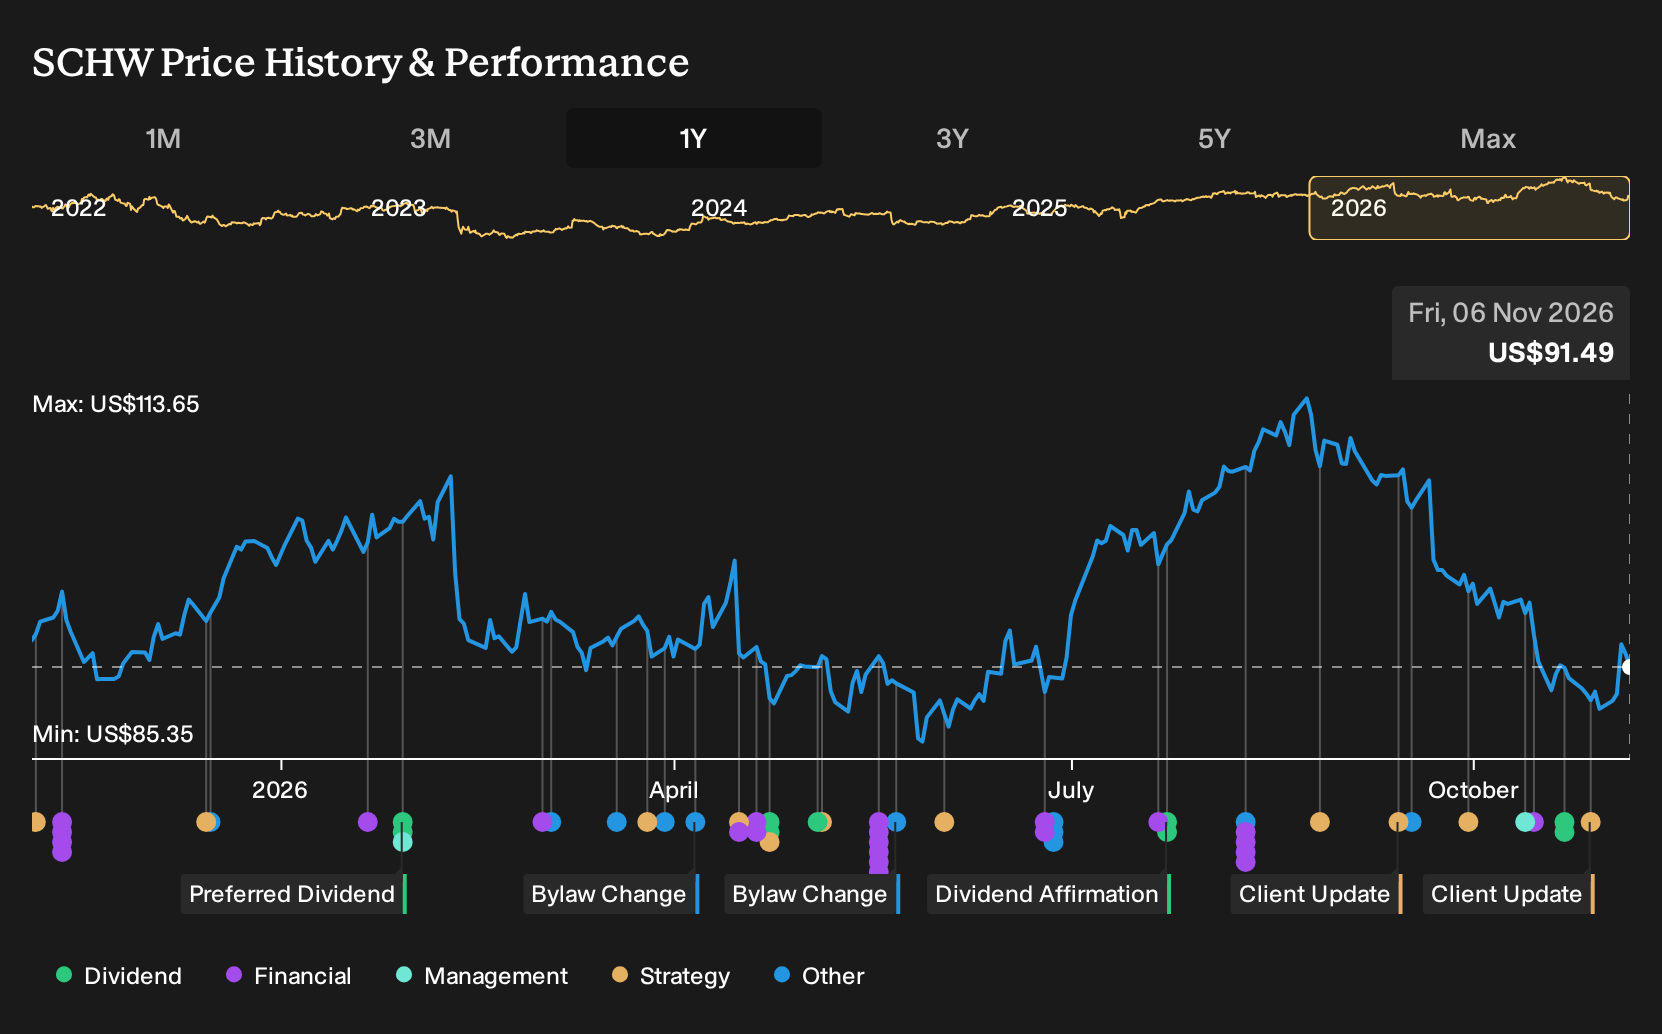
Exploring Other Perspectives
Some of the most cautious analysts focus less on Charles Schwab's AI push and more on pressure around net interest income. Before this Nevis news, the bearish group was only modeling revenue of about US$34.4b and earnings of roughly US$13.7b by 2029. That is a much more restrained story. Use this as a prompt to compare several narratives yourself.
Explore 3 other Charles Schwab fair value estimates, including one that suggests it could be worth just $116.86!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Charles Schwab research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charles Schwab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charles Schwab's overall financial health at a glance.
Looking for more investment ideas beyond Charles Schwab?
Once you have a view on Charles Schwab, it can help to broaden your watchlist with other companies that match different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential value with quality fundamentals, consider scanning a 38 high quality undervalued stocks that combine solid balance sheets with constructive cash flow profiles.
- If capital preservation and steadier business models matter most to you, focus on companies filtered from a 31 resilient stocks with low risk scores that screens for resilient operations and lower risk scores.
- When the goal is uncovering less followed ideas with robust underlying metrics, widen your search through a 19 high quality undiscovered gems that highlight strong fundamentals before broader attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com