
Benchmark Electronics (BHE) Raises 2026 Outlook As Its Undervalued Narrative Faces A Test
Benchmark Electronics (BHE) just raised its 2026 revenue and earnings outlook after record third quarter results, with earnings growth running nearly twice the pace of sales and demand broadening across advanced computing and AI infrastructure customers.
Despite raising guidance and expanding U.S. production for Oxide Computer Company in late October, Benchmark Electronics shares have retreated, with a 30 day share price return down 25.9% and a 90 day share price return down 25.7% from recent highs near the current US$60.40 level. However, the 1 year total shareholder return of 38.4% and roughly 3 year total shareholder return of about 2.6x still point to strong longer term momentum that recent volatility has not erased.
Scan beyond Benchmark Electronics to see how other AI infrastructure suppliers are setting up for their next move with our hand picked 53 AI infrastructure stocks today.
Benchmark Electronics now trades well below the average analyst target after a sharp pullback, even as guidance moves higher. Is that discount reflecting risk or mispricing the strength of this AI infrastructure story?
Most Popular Narrative: 30% Undervalued
Benchmark Electronics is framed as undervalued in the most followed narrative, with a fair value of $86 against a last close of $60.40. This puts the focus squarely on whether its execution in AI infrastructure and medical programs can justify that gap.
Benchmark Electronics is positioned to benefit from surging demand for advanced computing and AI infrastructure, now supported by 41% and 71% year-over-year AC&C revenue growth in Q1 and Q2 2026 driven by clustered AI and on prem cloud programs and by recognition as HPE’s 2026 Manufacturing Partner of the Year. Together these factors point to further contribution from upcoming high performance computing ramps into 2027 that can support revenue and gross margin.
See why 7 investors see Benchmark Electronics as 30% undervalued.
Result: Fair Value of $86 (UNDERVALUED)
Still, the bullish Benchmark Electronics narrative runs into real pressure if insider selling continues and reported sales or free cash flow fall short of expectations.
Find out about the key risks to this Benchmark Electronics narrative.
Another View: Benchmark Electronics On Earnings Multiples
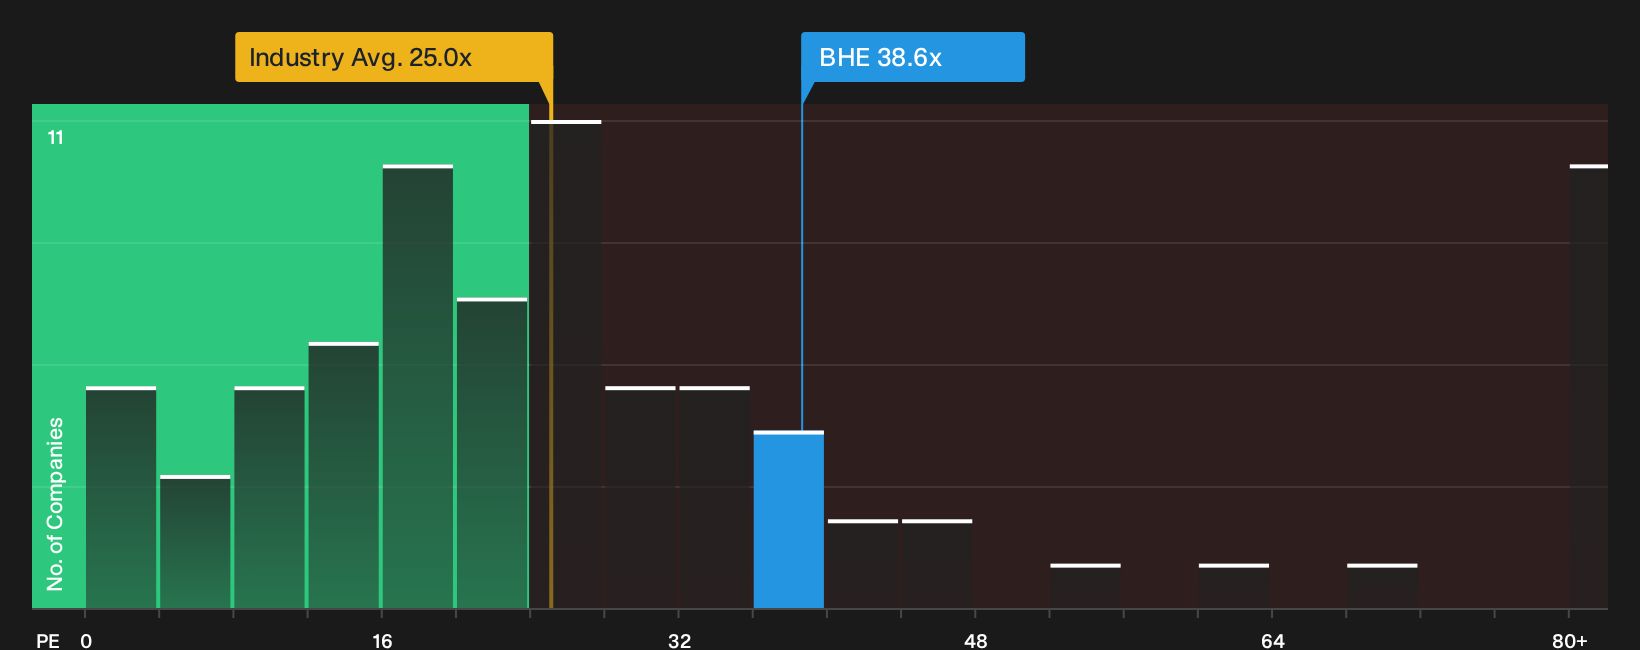
There is a different angle once you step away from fair value estimates and look at what the market is paying for Benchmark Electronics today. The stock trades on a P/E of 38.6x versus a fair ratio of 26.9x, above both the US Electronic industry at 25.1x and the peer average at 35x. That kind of premium can signal confidence in the AI and medical ramp, or it can leave less room for error if growth or margins cool.
To see what the numbers say about this price gap, take a look at the See what the numbers say about this price — find out in our valuation breakdown. next.
For a visual sense of how Benchmark Electronics stacks up against sector valuations, review the latest
Next Steps
There are mixed messages in the Benchmark Electronics story so far. If you want to move quickly and build your own view from the ground up, start with the balance between 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Benchmark Electronics?
If you stop with Benchmark Electronics, you risk missing other opportunities. Use a few focused screens to spot setups that fit your own playbook.
- Target potential mispricing by scanning a curated pool of quality companies trading at appealing valuations through the 38 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by reviewing a tight list of under followed opportunities with strong fundamentals via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com