
WeRide (WRD) Gains Insurance Backing As Investors Revisit Its Valuation
WeRide (NasdaqGM:WRD) has kicked off a global insurance partnership program with Allianz Insurance Singapore and Ping An Property & Casualty, tying dedicated coverage directly to its expanding L4 autonomous fleets across Asia, the Middle East and future European markets.
The insurance partnership comes at a time when WeRide’s share price has been under pressure overall, with a year-to-date share price return of negative 52.5% and a 1-year total shareholder return of negative 44.18%. This is despite a recent 1-day share price gain of 10.4% and a 7-day share price return of 7.73% from a last close of US$4.46. These moves suggest investors are reassessing both the growth potential and risk profile as new agreements like this influence expectations around its global rollout.
Explore insurer-backed autonomy plays such as WeRide, together with other handpicked robotics and automation opportunities, through our 91 robotics and automation stocks list.
After a steep slide and a sharp bounce, WeRide now sits at a price where opinions split. Is the meaningful upside still ahead, or did most of it already play out in the first rebound before valuation even enters the frame?
Most Popular Narrative: 66% Undervalued
On the most followed view of WeRide, a fair value of $13.02 versus a last close of $4.46 points to a wide gap that current headlines alone do not explain.
The dual deployment of L4 robotaxis and L2+ WePilot 3.0 ADAS in mass production vehicles from Chery EXEED and GAC allows data and software to be reused across product lines. This can spread R&D spending over a larger revenue base and potentially support higher group level margins.
See why 9 investors see WeRide as 66% undervalued.
Result: Fair Value of $13.02 (UNDERVALUED)
Still, the bullish WeRide narrative hinges on regulatory momentum and high vehicle utilization, and setbacks in permits or rider uptake could quickly flip sentiment.
Find out about the key risks to this WeRide narrative.
Another View On WeRide’s Valuation
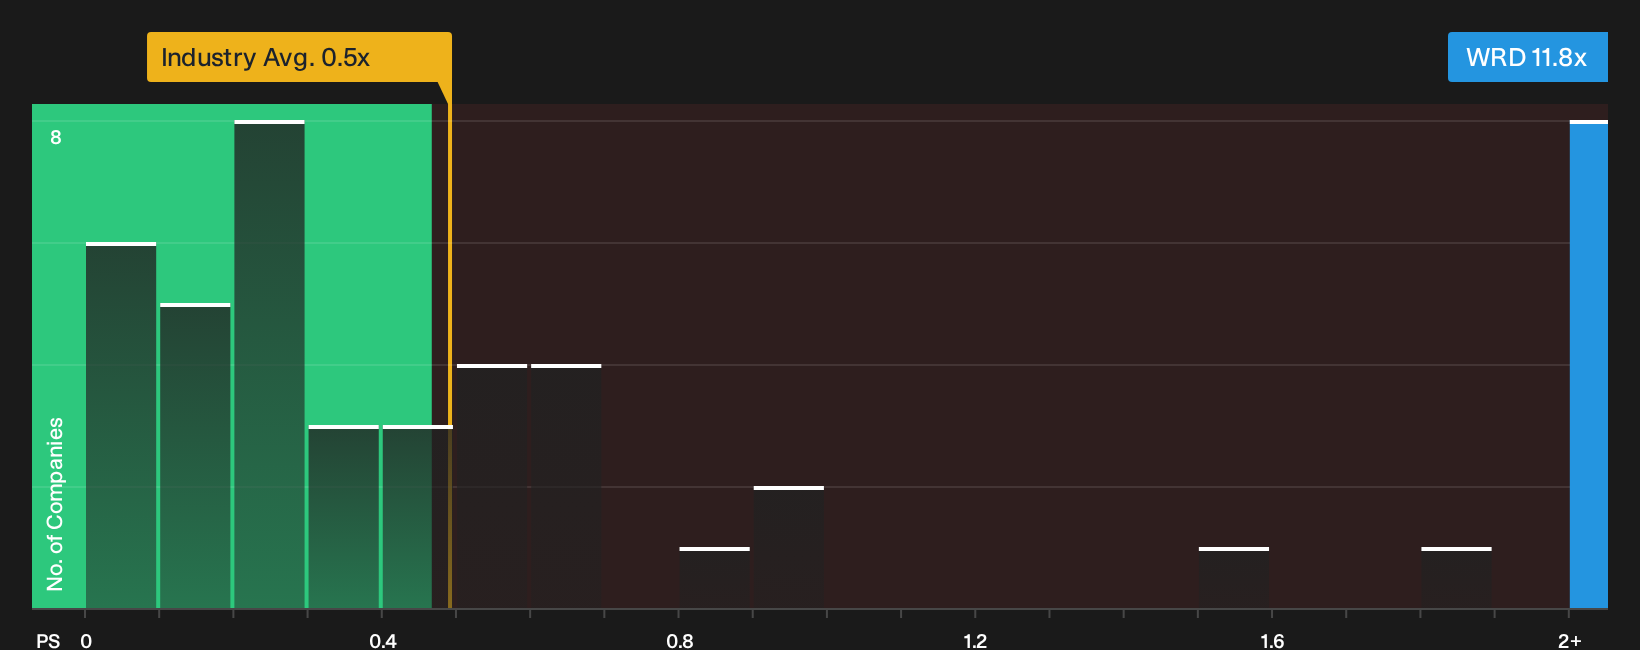
Those analyst targets lean heavily on future earnings forecasts and a high future P/E. A simpler reality check uses today’s P/S of 11.8x. That is far above the US Auto Components industry at 0.5x, the peer average at 1.8x, and the SWS fair ratio of 3x, which points to meaningful valuation risk if sentiment cools.
For a closer look at how this pricing gap could matter for your own return expectations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around WeRide feels familiar, then take a moment to inspect the underlying data and pressure test the story for yourself. To see what investors are highlighting on the upside, start with the 2 key rewards
Looking for more investment ideas beyond WeRide?
Do not stop with one stock. Broaden your watchlist using focused screeners that can surface very different types of opportunities from what you see in headlines today.
- Hunt for underappreciated quality by scanning our 38 high quality undervalued stocks that filters for companies with strong fundamentals trading below their estimated worth.
- Prioritise resilience by using the 31 resilient stocks with low risk scores to zero in on businesses with steadier financial profiles and lower overall risk scores.
- Target staying power by testing the list of solid balance sheet and fundamentals (25 results) so you can focus on firms with healthier debt levels and more durable capital structures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com