
Iridium Communications (IRDM) Could Be 8% Undervalued As Earnings Refocus Valuation
Iridium Communications earnings spark fresh investor focus
Iridium Communications (IRDM) is back on the radar after quarterly results showed 8.3% revenue growth and a 180% jump in earnings per share, prompting investors to recheck the satellite operator’s fundamentals.
The earnings surprise comes after a choppy stretch for Iridium Communications, with a 30-day share price return of down 7.23% and a 90-day move of down 10.71%, even as the stock still carries a powerful year-to-date share price return of 147.97% and a 1-year total shareholder return of 167.90%. That mix of near term pullback and strong longer run gains suggests momentum has cooled recently. At the same time, longer horizon holders have still seen substantial value creation as expectations around the satellite group's growth potential and risk profile have shifted.
Scan beyond Iridium Communications and see how other satellite and telecom plays stack up on fundamentals inside our hand picked list of solid balance sheet and fundamentals (25 results).
After a 1-year total return of 167.90% followed by a recent pullback, Iridium Communications now forces a choice. Do you pay up for the story today, or wait and hope for a cheaper entry as the valuation picture comes into focus?
Most Popular Narrative: 8% Undervalued
On the latest numbers, Iridium Communications closed at $44.04, while the most followed fair value estimate sits at $48. That gap is not huge, yet it is large enough that investors are paying close attention to how the long term story holds together.
The current Rocket Lab transaction value of about $8 billion, or $54 per Iridium share, implies the market is already pricing in continued strong cash flow through 2030 and meaningful benefit from spectrum assets and new growth projects. This leaves limited room for upside if those expectations are not met.
See why 32 investors see Iridium Communications as 8% undervalued.
Result: Fair Value of $48 (UNDERVALUED)
Still, the story around Iridium Communications can break if expected PNT and NTN Direct uptake disappoints, or if Aireon and the proposed Rocket Lab deal strain execution.
Find out about the key risks to this Iridium Communications narrative.
Another View: Iridium Communications looks pricey on earnings
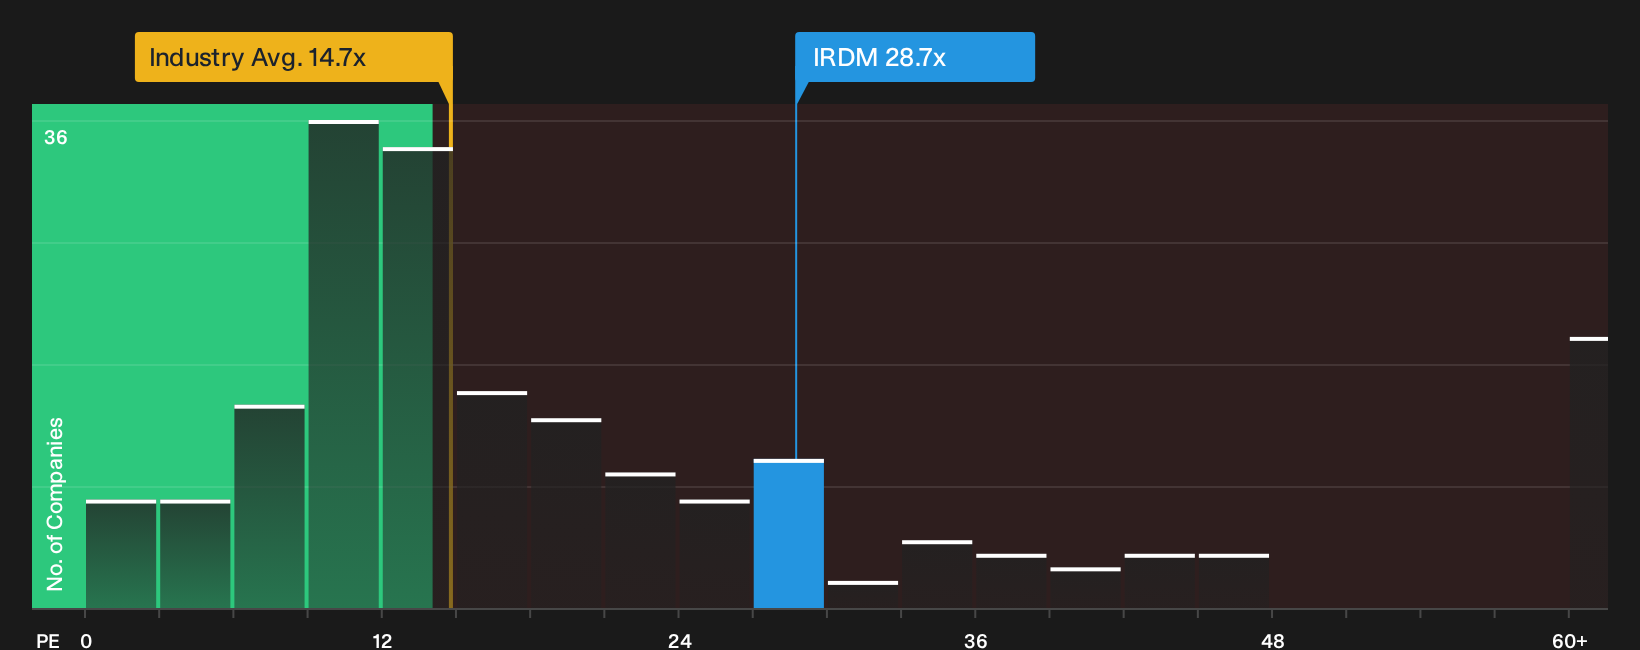
The fair value story around Iridium Communications at $48 leans on narrative and analyst targets. A simple earnings yardstick tells a tougher story. The stock trades on a P/E of 28.7x, almost double the global telecom average of 14.7x and far above its fair ratio of 11.6x. That kind of gap can shrink either through slower share price progress or much stronger profits in future, so which outcome do you want to bet on?
If you prefer to anchor on earnings multiples rather than cash flow models, it is worth seeing how this pricing stacks up against peers and that fair ratio starting point, then asking whether you are comfortable paying such a premium for Iridium Communications today. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed messages in the Iridium Communications story so far. Consider acting while sentiment is divided and pressure test the bull and bear points for yourself with 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Iridium Communications?
If Iridium Communications has sharpened your thinking, do not stop here. Use the Simply Wall St screener to widen your opportunity set and stress test your next moves.
- Target resilience first and filter for companies that pair lower risk profiles with sturdier fundamentals through the 31 resilient stocks with low risk scores.
- Hunt for value by scanning companies that combine stronger quality checks with prices that may lag their fundamentals using the 38 high quality undervalued stocks.
- Spot under followed opportunities and see which lesser known businesses still clear solid fundamental hurdles with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com