
Is Capri Holdings (CPRI) Fully Valued As Higher Fiscal 2027 Guidance Lifts Optimism?
Why Capri Holdings stock is back on investors’ radar
Capri Holdings (CPRI) just raised its fiscal 2027 guidance, flagging projected revenue of about US$3.42b, operating income of roughly US$175m and expected diluted EPS of US$2.20 despite currency headwinds.
The guidance update landed after a rapid swing in sentiment around Capri Holdings, with the share price climbing 37.39% over the past month and 33.12% over the last 90 days. However, the year-to-date share price return is still down 15.79% and the 3-year total shareholder return has declined 56.40%, suggesting near term momentum is improving while longer term holders remain deeply under water.
Spot opportunities with similar turnarounds by scanning our hand picked 19 high quality undiscovered gems, which pair improving fundamentals with underappreciated share prices.Capri Holdings now trades below both analyst targets and some intrinsic value estimates, even after the rebound. Is that a genuine mispricing, or a market warning signal that the recent optimism goes too far?
Most Popular Narrative: 14% Overvalued
Capri Holdings closed at $20.54, compared with a widely followed fair value narrative of $18.00 that uses an 11.24% discount rate and incorporates execution risk around margins and growth.
The current numbers, including guidance for higher operating income and EPS supported by cost cuts and buybacks, suggest that Capri Holdings shares already reflect successful execution on margin expansion and capital return plans.
This narrative explores a more pessimistic perspective on Capri Holdings compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
See why 1 investors see Capri Holdings as 14% overvalued.
Result: Fair Value of $18.00 (OVERVALUED)
Still, this bearish Capri Holdings thesis meets real pushback if operating income continues to rise faster than sales, or if Jimmy Choo’s accessories business materially improves the earnings mix.
Find out about the key risks to this Capri Holdings narrative.
Another view on Capri Holdings’ valuation
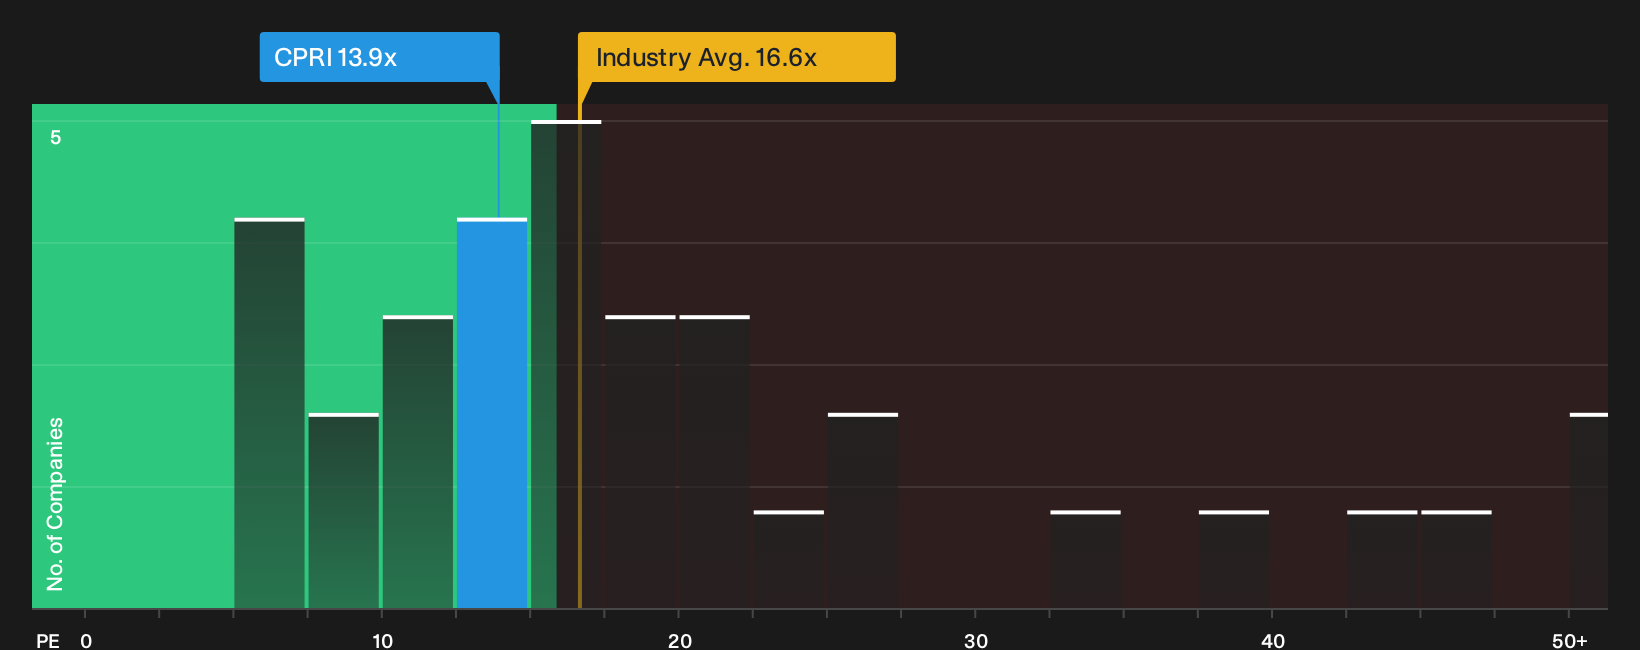
The fair value narrative pegs Capri Holdings at $18.00, yet the stock changes hands at a P/E of 13.9x. Peers in US luxury trade closer to 16.6x and the fair ratio for Capri is 22.2x, which implies the market is pricing in more risk. Is that caution justified or excessive?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Capri Holdings story seems carefully poised between concern and optimism, consider reviewing the details while they are still current and pressure test the numbers yourself with 4 key rewards and 2 important warning signs.
Looking for more Capri Holdings style ideas?
If Capri Holdings has you rethinking what a turnaround can look like, you might miss your next big idea if you stop your research here.
- Target underappreciated quality by scanning our curated set of 38 high quality undervalued stocks that combine strong fundamentals with potentially misaligned market expectations.
- Prioritize resilience over drama by focusing on a 31 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier business profiles.
- Hunt for the next potential comeback story with a 19 high quality undiscovered gems that surfaces under-the-radar companies before they hit the wider spotlight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com