
IRADIMED (IRMD) Earnings And Guidance Put Valuation Back In Focus
IRADIMED guidance, dividend and fresh earnings in focus
IRADIMED (IRMD) just combined three key developments in one day: fresh third quarter results, new guidance for the fourth quarter and full year 2026, and a reaffirmed regular cash dividend.
IRADIMED’s fresh guidance and dividend sit against a mixed share price backdrop, with a 7 day share price return of 12.56% but the year to date share price return still down 9.62%. At the same time, longer term total shareholder return over three and five years has been strong. This suggests that investors are weighing solid multi year gains against near term valuation and risk after the latest earnings update.
Scan how IRADIMED’s latest guidance and dividend policy compare with other potential opportunities by reviewing a curated group of 31 resilient stocks with low risk scores in similar or adjacent sectors.
IRADIMED now trades at a sizable discount to the average analyst target, even after the recent bounce. Is that a valuation opportunity, or is the market insisting on a margin of safety?
Most Popular Narrative: 26.9% Undervalued
IRADIMED closed at $86.31, while the analyst consensus Narrative on Simply Wall St anchors fair value at $118 based on detailed long term forecasts and a 7.52% discount rate.
The introduction and FDA approval of the new 3870 MRI compatible IV pump, with significantly enhanced usability and technology over the legacy product, is expected to catalyze a major replacement cycle among hospitals and imaging centers. This could support higher IRADIMED device and consumable revenue and lift earnings as that installed base refresh is delivered.
See why 8 investors see IRADIMED as 27% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, the IRADIMED story could be knocked off course if MRI focused demand softens or if 3870 manufacturing efficiencies take longer to materialize.
Find out about the key risks to this IRADIMED narrative.
Another View: IRADIMED and the earnings multiple question
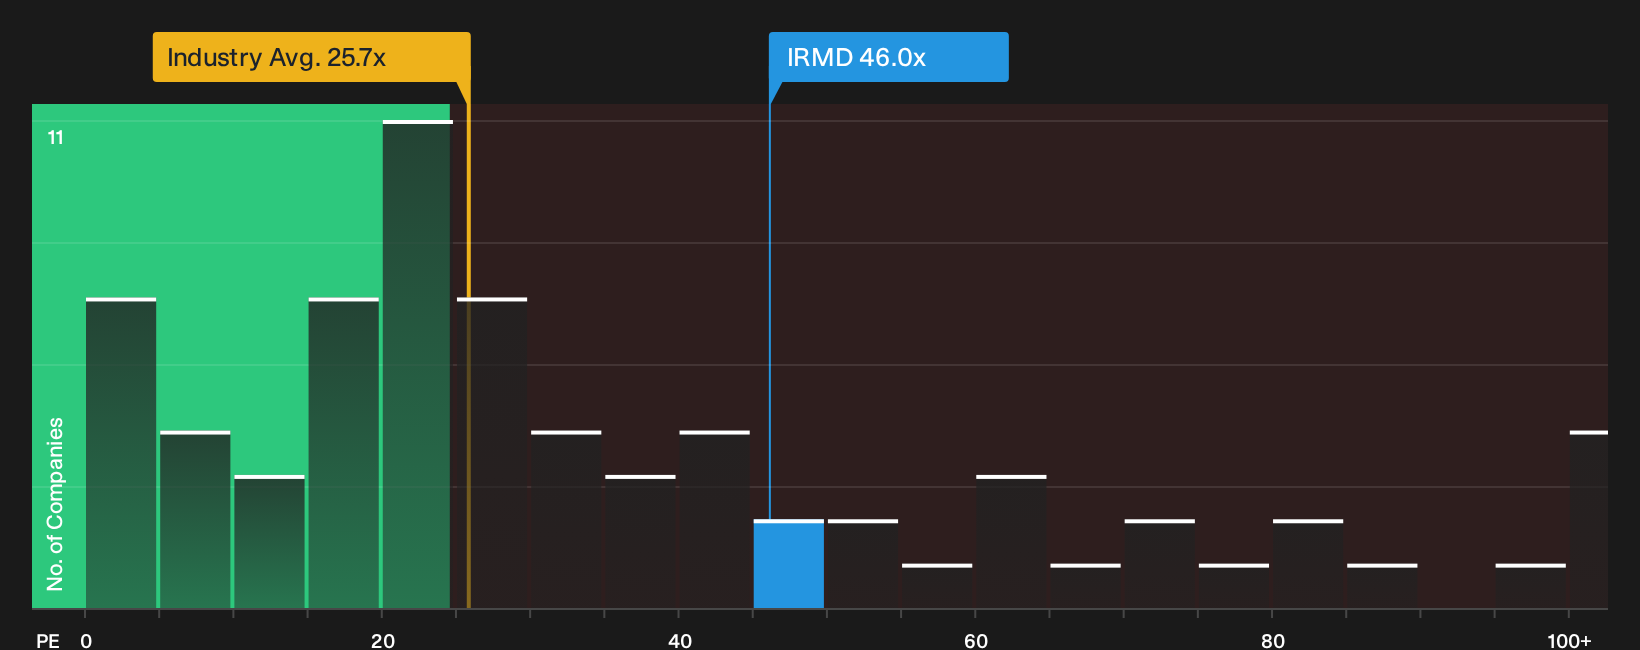
IRADIMED screens very differently when the focus shifts from the narrative fair value of $118 to the actual P/E being paid today. The stock trades on roughly 46x earnings while the fair ratio is 21.9x, the peer group sits near 40.2x and the wider US Medical Equipment space around 25.7x.
That spread implies investors are paying a premium for the current IRADIMED story, not a discount. It raises a simple question for anyone looking at the shares now: Is the business quality strong enough to keep justifying a P/E this far above both the industry and the fair ratio, or is valuation risk quietly building in the background?
Our valuation tools unpack how this P/E premium lines up with the fundamentals and cash generation behind it, and how quickly sentiment could shift if expectations are not met, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious tone around IRADIMED matches your own read of the numbers and narrative today? Move quickly and review the positives investors are focused on with the 2 key rewards.
Looking for more IRADIMED investment ideas?
If IRADIMED has your attention, do not stop here. Put that curiosity to work by widening your watchlist with a few focused stock searches.
- Target potential mispricing by scanning a curated pool of companies that combine earnings strength with appealing valuations through the 38 high quality undervalued stocks.
- Prioritise resilience by zeroing in on businesses with cleaner balance sheets and steadier fundamentals via the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities by checking a selected group of financially robust prospects using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com