
Will Raised Revenue Guidance Change Aurinia Pharmaceuticals Stock Narrative
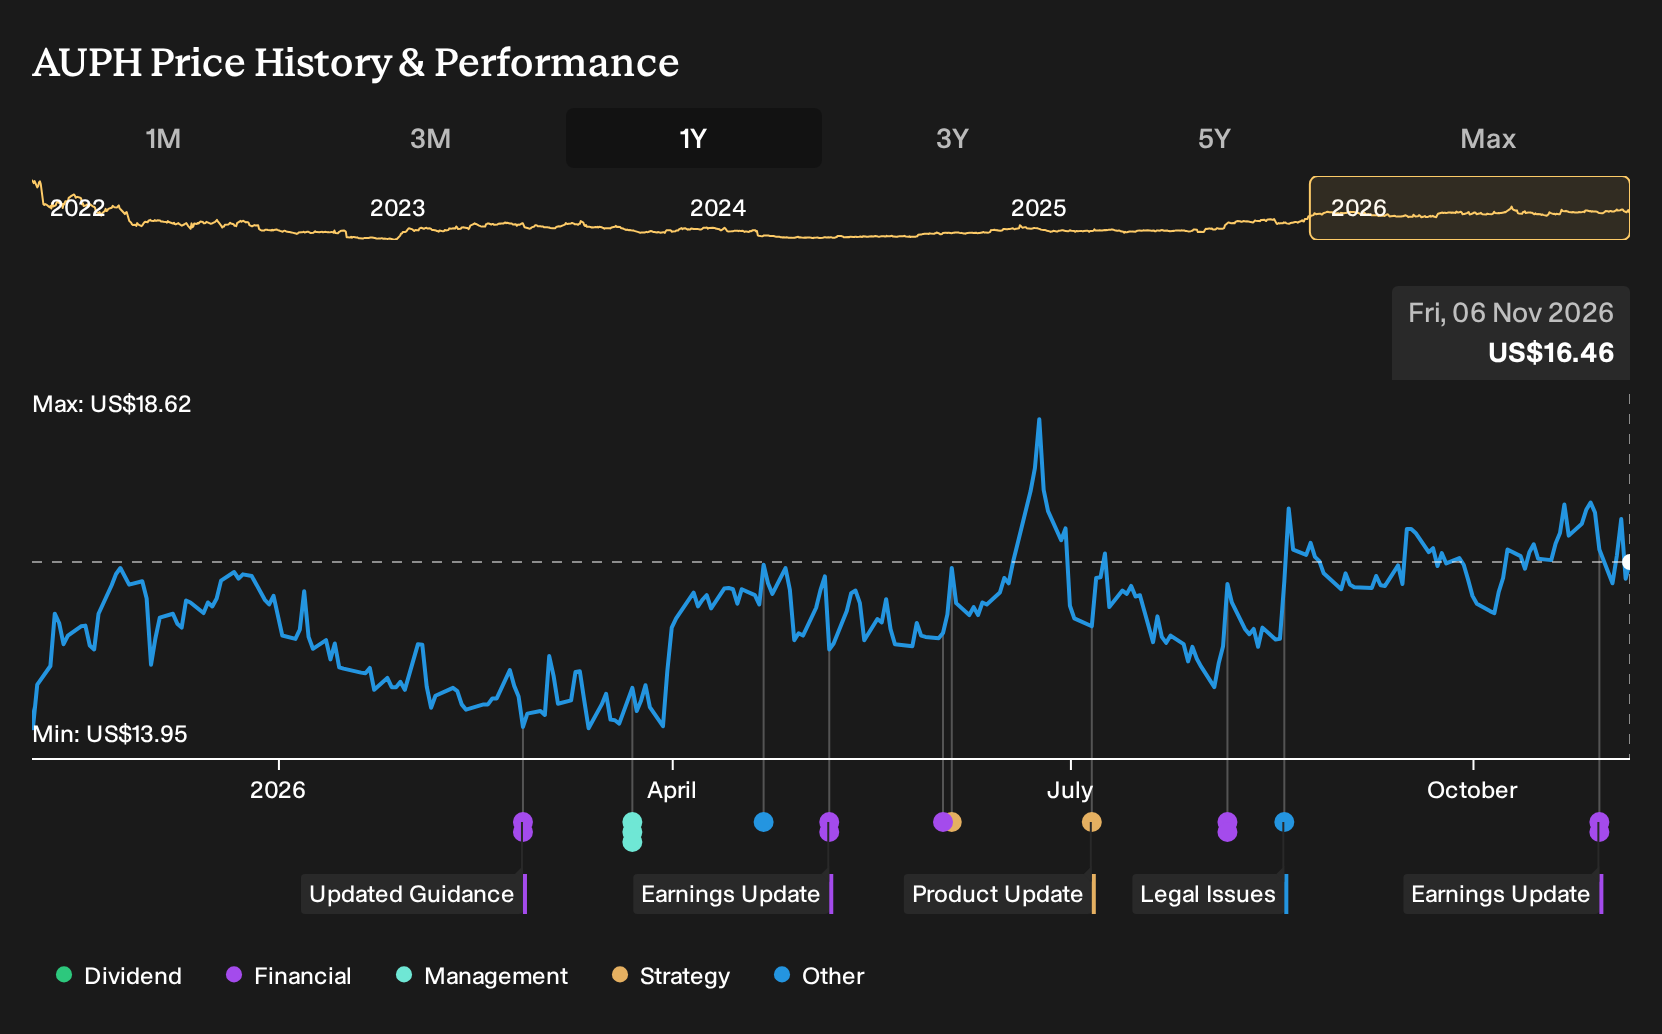
- Aurinia Pharmaceuticals reported third quarter 2026 revenue of US$83.7 million and net income of US$31.7 million, with basic earnings per share from continuing operations of US$0.24. The company also shared nine month figures showing revenue of US$244.62 million and net income of US$103.47 million.
- Management raised full year 2026 total revenue guidance to a range of US$325 million to US$330 million, reflecting current demand and cost discipline and supporting the view of Aurinia Pharmaceuticals as a cash generative business built on autoimmune therapies.
- We will now explore how Aurinia Pharmaceuticals higher full year revenue guidance could reshape its investment narrative built around LUPKYNIS.
Compare Aurinia Pharmaceuticals' latest guidance with a curated set of cash-generative healthcare stocks by using the list of solid balance sheet and fundamentals (25 results) as a starting point for deeper analysis.
Aurinia Pharmaceuticals Investment Narrative Recap
For Aurinia Pharmaceuticals, the investment case still revolves around LUPKYNIS paying the bills while the autoimmune pipeline matures. The analyst consensus Narrative on Simply Wall St assumes investors are comfortable with heavy reliance on a single commercial therapy and treats the business as already priced as a cash generative operator. The latest quarterly figures and raised revenue guidance reinforce that view rather than reset it.
The near term swing factor remains how prescription trends, reimbursement outcomes and pricing for LUPKYNIS hold up against rising competition. That same concentration is also the biggest risk. The new guidance appears supportive for the short term story, but it does not remove concerns about potential pricing pressure or policy scrutiny on drug costs.
The raised 2026 revenue guidance to US$325 million to US$330 million sits at the center of this update. It aligns with the catalyst described in the analyst consensus Narrative on Simply Wall St, where Aurinia Pharmaceuticals is framed as a mature earner whose cash profile is already built into expectations. Management is effectively reaffirming that revenue range rather than shifting the business model.
For you as a shareholder or potential investor, that makes execution around LUPKYNIS and pipeline progress even more important. Analysts already expect earnings to edge down slightly over the next three years, and view the P/E multiple as relatively low compared with peers. Any stumble in maintaining LUPKYNIS share, or any delay in turning aritinercept and zetomipzomib into meaningful contributors, would weigh more heavily when so much value is tied to a single drug.
Aurinia Pharmaceuticals' scenario has analysts pointing to forecast revenue of US$466.3 million and earnings of US$202.0 million by 2029, based on an assumed 13.2% yearly revenue growth rate and an earnings decline of US$112.3 million from current earnings of US$314.3 million.
Uncover why Aurinia Pharmaceuticals' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Aurinia Pharmaceuticals leans heavily on the pipeline as a potential upside swing factor. Bullish analysts were modeling about US$613.2 million of revenue and US$276.8 million of earnings by 2029 before this latest guidance. That is a much more optimistic story. Investors can use this earnings beat to test how strongly they agree with that pipeline driven case.
Explore 3 other Aurinia Pharmaceuticals fair value estimates, including one that suggests as much as 157% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Aurinia Pharmaceuticals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Aurinia Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aurinia Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Aurinia Pharmaceuticals?
If the Aurinia Pharmaceuticals story sparked new questions rather than tidy answers, you can use that curiosity to broaden your watchlist with other businesses that align with the type of risk and quality profile you prefer.
- If you prefer companies that already look cheap relative to their fundamentals and cash flows, and you want a shortlist to review next, you can start with the 39 high quality undervalued stocks for ideas that might deserve a closer look.
- If capital preservation is a high priority and you want steadier balance sheets to anchor your portfolio, you can filter for sturdier businesses using the 31 resilient stocks with low risk scores and see which ones fit your comfort zone.
- For readers looking for promising but less crowded opportunities that still have solid financial underpinnings, you can use the 19 high quality undiscovered gems to identify potential additions that the wider market may not be focusing on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com