
Will Half Year Earnings Change SCREEN Holdings' (TSE:7735) Narrative
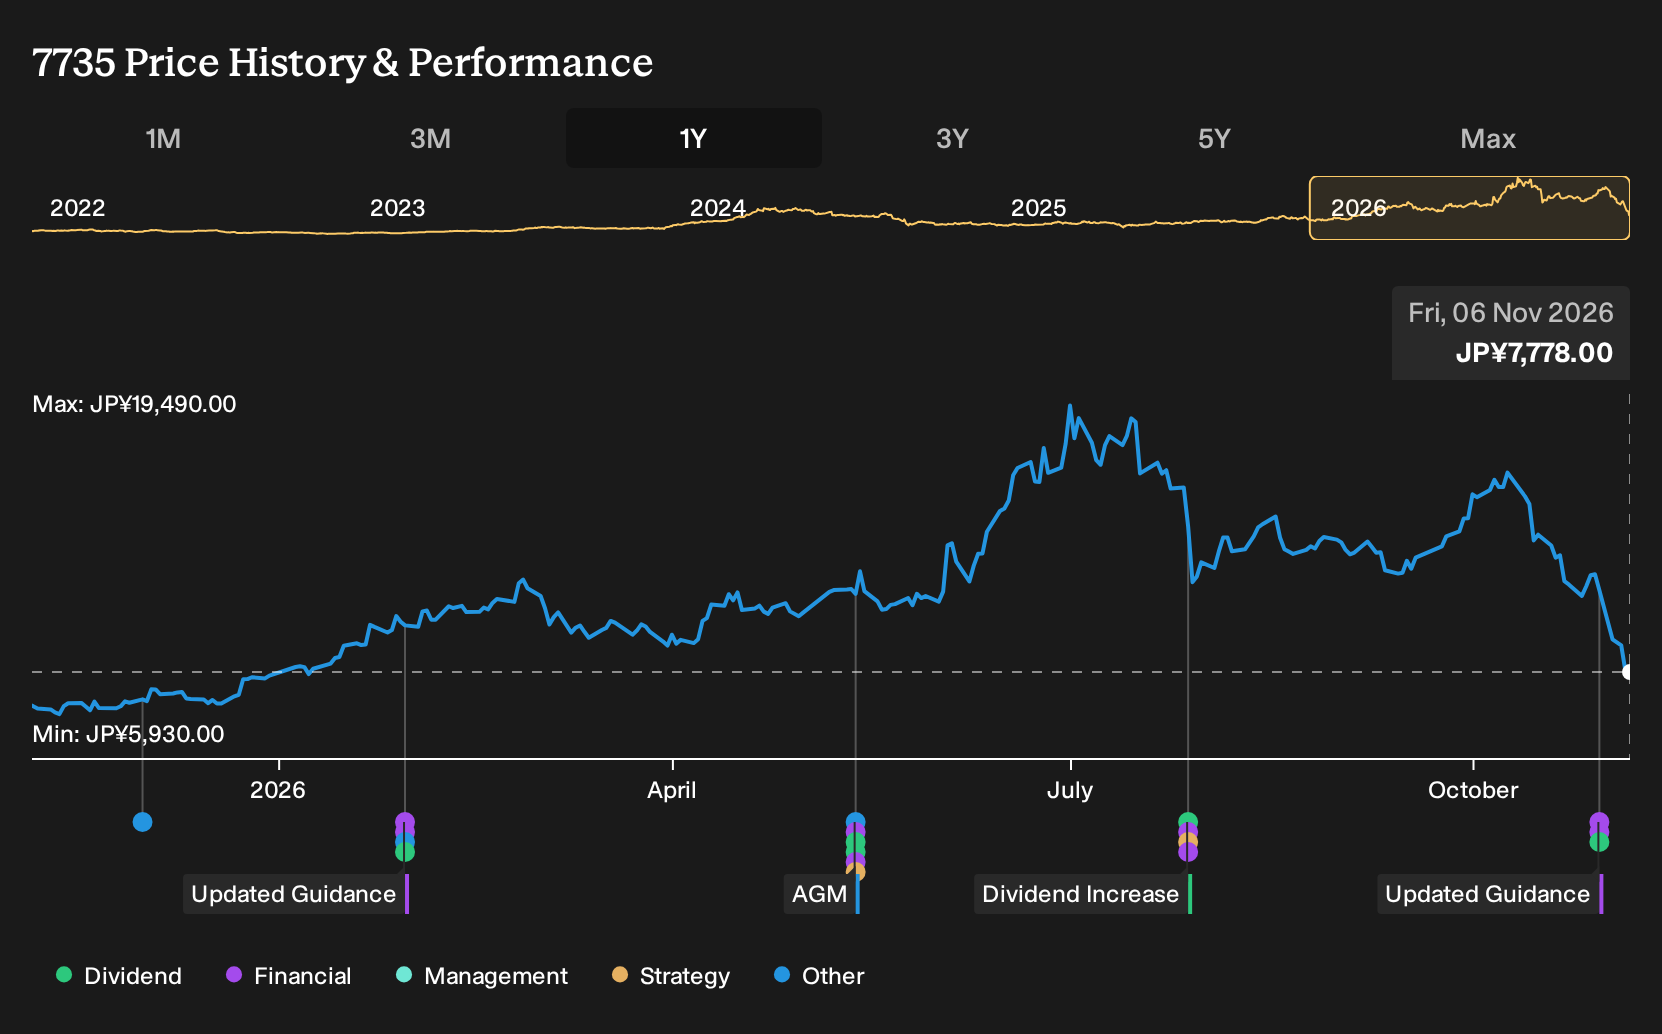
- SCREEN Holdings reported half year results to 30 September 2026 with sales of ¥308,453 million, net income of ¥37,656 million and basic earnings per share of ¥199.06. The company issued full year guidance to March 2027 and announced a second quarter dividend of ¥60.00 following an earlier 1 for 2 stock split.
- The combination of stronger half year fundamentals and a lower interim dividend per share compared with the prior year post split level highlights how SCREEN Holdings is balancing capacity investment needs, cost pressures and shareholder returns.
- We will now look at how SCREEN Holdings' upgraded earnings guidance reshapes the existing investment narrative built around AI driven equipment demand.
Scan beyond SCREEN Holdings and line up other equipment and AI infrastructure players using our curated list of 53 AI infrastructure stocks as potential comparison points.
SCREEN Holdings Investment Narrative Recap
To remain a shareholder in SCREEN Holdings, you need to believe the AI driven equipment cycle and related capex plans can support the current earnings profile, even with higher fixed costs. The latest half year figures and full year guidance point to an operating structure geared toward that opportunity, with SPE and related tools still central to the story.
The main short term catalyst remains customer follow through on AI related foundry, DRAM and advanced packaging projects highlighted in the analyst consensus Narrative on Simply Wall St. The biggest near term risk still lies in cost inflation and exposure to China and Taiwan demand, and this guidance does not materially change that risk balance.
The full year outlook to March 2027, with forecast net sales of ¥743,000 million and profit attributable to owners of parent of ¥115,000 million, is the announcement that most clearly ties into these catalysts. It indicates how SCREEN Holdings currently sizes its opportunity set against rising R&D, depreciation and personnel costs.
That profit and earnings per share guidance of ¥607.72 now sit alongside half year results where higher raw material costs and tariffs remain in the background. For you, the key question is whether this earnings path still appears achievable if China or Taiwan demand softens or if GA margins stay pressured by policy and currency swings.
SCREEN Holdings' narrative projects ¥1,030.6b revenue and ¥191.7b earnings by 2029. This assumes revenue growth of 20.3% per year and an earnings increase of about 2.2x from ¥85.8b today.
Uncover why SCREEN Holdings' fair value points to a 125% potential upside to its current price that could close more quickly than you expect.
Exploring Other Perspectives
One alternate view focuses on SCREEN Holdings’ rising fixed costs as the real swing factor. The most cautious analysts were only pencilling in about ¥1,002.9b of revenue and ¥159.2b of earnings by 2029 before this guidance, which reflects a much more restrained earnings path. That gap in expectations shows how widely opinions can differ, so it is worth exploring both sets of assumptions before considering how this new guidance might affect the overall narrative.
Explore 2 other SCREEN Holdings fair value estimates, including one that suggests it could be worth just ¥9,289.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SCREEN Holdings research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SCREEN Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SCREEN Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond SCREEN Holdings?
If you want to pressure test your view on SCREEN Holdings, it helps to stack it up against other opportunities that share similar quality, cash flow or income traits. The Simply Wall St Screener lets you do exactly that in a few clicks, so you can compare what you see here with a wider field of candidates that might suit your risk tolerance and time horizon.
- If capital preservation is high on your list, start with a set of resilient companies through the 20 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles.
- For readers hunting for value backed by fundamentals, line up potential ideas with the 26 high quality undervalued stocks and see which tickers look mispriced on quality and cash generation.
- If you want balance sheet strength to do some of the heavy lifting, filter for sturdier financial footing through the list of solid balance sheet and fundamentals (23 results) and compare those candidates to SCREEN Holdings on metrics that matter to you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com