
OSI Systems (OSIS) Earnings Beat Puts Fair Value Back In Focus
How OSI Systems framed its latest quarter and acquisition ambitions
OSI Systems (OSIS) tied a first quarter earnings update to a renewed interest in acquisitions, highlighting higher revenue, higher net income, and a preference for deals that expand market reach or add complementary businesses.
Management placed organic investment at the top of its capital priorities, with acquisitions, opportunistic buybacks, and balance sheet strength following behind. That ranking matters for anyone trying to judge how aggressively the group might pursue deals.
Comments from the leadership team stressed fit over speed. The company described potential transactions that would build on existing momentum or open up adjacent markets, rather than acquisitions pursued purely for scale.
Those remarks arrived alongside reported first quarter revenue of US$403.47 million and net income of US$24.57 million, both above the figures shared for the same period a year earlier.
Earnings per share from continuing operations also moved higher year on year on both a basic and diluted basis, which gives investors another data point when comparing OSI Systems to other listed equipment and technology providers.
- Revenue for the quarter reported at US$403.47 million compared with US$384.62 million a year ago.
- Net income for the same period reported at US$24.57 million versus US$20.56 million a year earlier.
- Basic EPS from continuing operations reported at US$1.55, previously US$1.22.
- Diluted EPS from continuing operations reported at US$1.51, previously US$1.18.
For anyone tracking the stock into November 2026, that combination of higher earnings and open but selective M&A commentary forms the backdrop to recent trading moves in OSIS.
OSI Systems shares closed at US$196.36 after the earnings call, with a 1-day share price return of 2.48% that helped offset some of the pressure from a 90-day share price decline of 15.8% and a year-to-date share price drop of 23.17%, as investors weighed the stronger quarterly results and acquisition commentary against earlier weakness.
Over a longer horizon, the picture looks different. A 3-year total shareholder return of 73.99% and a 5-year total shareholder return of 103.63% point to meaningful value creation over time, even after a 1-year total shareholder return decline of 31.23%.
Compare OSI Systems' acquisition driven story with a curated set of equipment and tech peers by scanning the 19 high quality undiscovered gems that may be flying under most radars.
OSI Systems now trades well below analyst targets even after the earnings bump, which leaves a blunt question hanging: Is this discount a genuine opportunity, or is the market correctly pricing in risk?
Most Popular Narrative: 29% Undervalued
The analyst consensus Narrative on Simply Wall St points to a fair value of about $278 per OSI Systems share compared with the last close at $196.36. This frames the current discount through the lens of future contracts, margins, and cash generation.
The main factor that has to go right is that OSI Systems continues to grow higher margin Security, RF and service revenues while sustaining the recent margin improvement in Healthcare. This would allow the whole group to support structurally higher profitability on its existing contract base.
See why 5 investors see OSI Systems as 29% undervalued.
Result: Fair Value of $278.29 (UNDERVALUED)
Still, the OSI Systems narrative leans heavily on converting that US$1.9b backlog, while Security softness and delayed Middle East deliveries could easily unsettle the story.
Find out about the key risks to this OSI Systems narrative.
Another View: OSI Systems Through a Cash Flow Lens
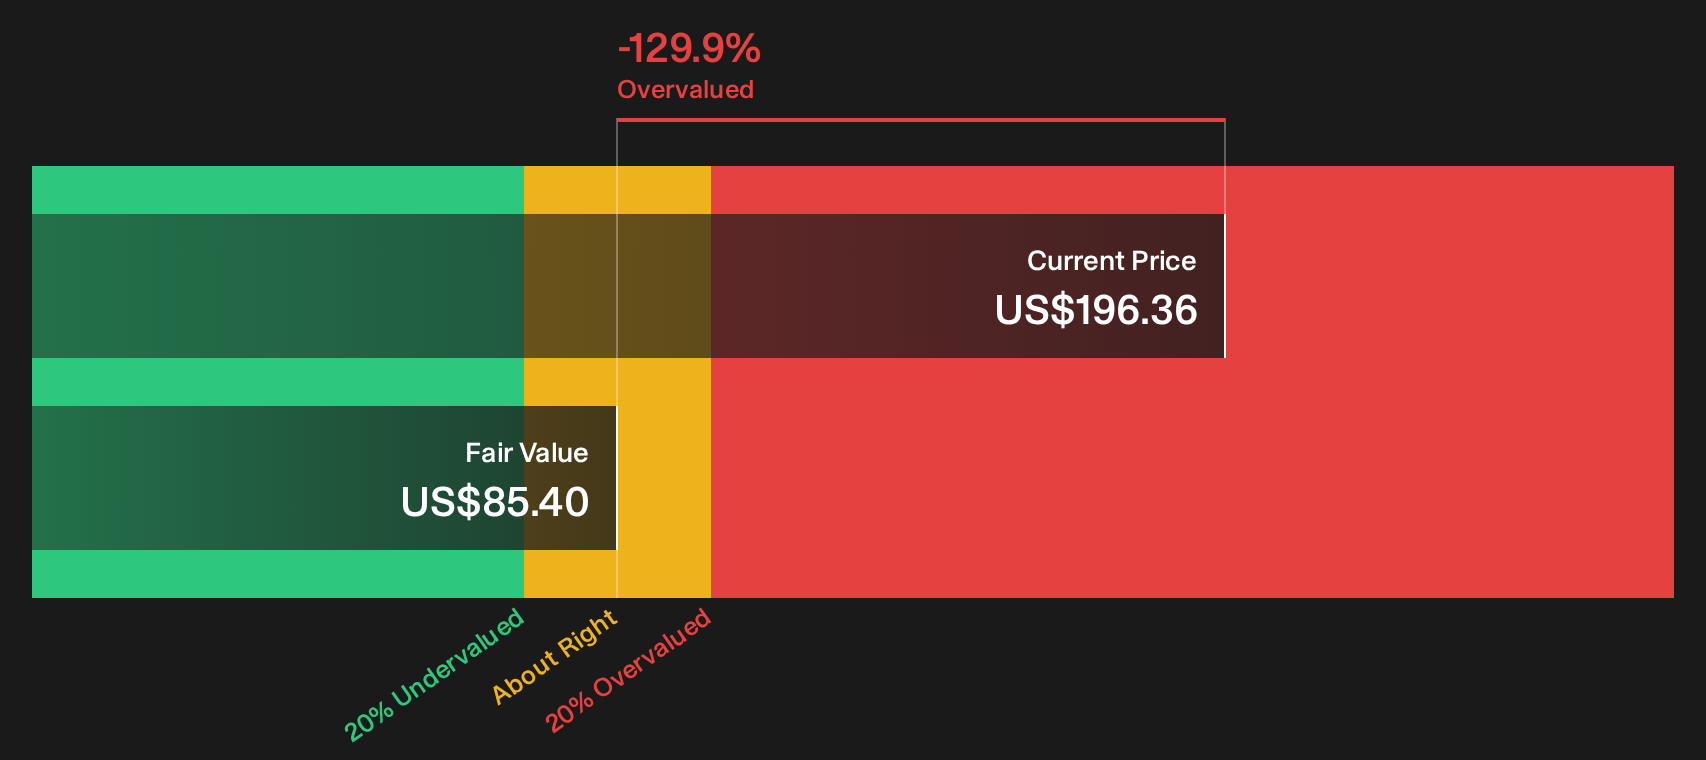
There is a very different read on OSI Systems when switching from analyst targets to the SWS DCF model. On this approach, the stock at $196.36 sits well above an estimated future cash flow value of $85.40, which screens as overvalued rather than discounted. That gap raises a simple question for investors: Which set of assumptions feels more realistic?
Our DCF framework rests on explicit cash flow forecasts and a chosen discount rate, so it reacts sharply to changes in growth, margins, and required returns. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OSI Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around OSI Systems feels finely balanced, consider acting promptly and testing the story against the underlying numbers yourself. To weigh both sides properly, start with the 5 key rewards and 1 important warning sign.
Looking for more OSI Systems style investment ideas?
If the OSI Systems debate has sharpened your thinking, do not stop here. Broaden your watchlist now and give yourself more options before the next catalyst hits.
- Target quality at a discount by scanning companies flagged as potentially mispriced using the 39 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with stronger finances and lower perceived risk through the 31 resilient stocks with low risk scores.
- Hunt for under the radar opportunities by reviewing fundamentally sound prospects that few are tracking in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com