
WSFS Financial (WSFS) Faces A Valuation Test As Its Core Banking Narrative Holds
Recent share performance and business snapshot
WSFS Financial (WSFS) has drawn fresh attention after a mixed stretch in the market, with the share price slipping on the day and over the past week while posting gains over the past month.
The regional lender is valued at about US$4.0b based on its recent close at US$78.94. It reports annual revenue of US$1.09b and net income of US$333.2m from its banking, cash services, and wealth segments.
In the short term, WSFS Financial has lost some steam, with the share price slipping over the past week and quarter. However, the 30-day share price return of 4.71% and a 1-year total shareholder return of 45.44% point to momentum built over a longer stretch.
Scan how WSFS Financial stacks up against other banks with resilient balance sheets by checking our curated list of solid balance sheet and fundamentals (25 results) for ideas beyond this one ticker.
WSFS Financial has rallied hard over the past year while still trading below both analyst targets and one intrinsic value estimate. Does that gap suggest there may be room in the valuation, or has the market already done the heavy lifting?
Most Popular Narrative: 11% Undervalued
On the analyst consensus Narrative on Simply Wall St, WSFS Financial screens as modestly undervalued, with a fair value estimate of $88.92 against the recent $78.94 close. That view leans heavily on earnings quality, fee income, and balance sheet mix rather than raw growth.
The main thing that has to go right is that WSFS Financial continues to execute on reshaping the balance sheet toward core relationship lending and deposits while holding credit metrics and deposit costs in check despite rising competition.
Continuation of high core ROA and core ROTCE, together with capital levels above the stated CET1 target, provides room for WSFS Financial to keep returning a large portion of earnings through share repurchases, which can lift earnings per share even if overall revenue growth is modest.
See why 0 investors see WSFS Financial as 11% undervalued.
Result: Fair Value of $88.92 (UNDERVALUED)
Still, the WSFS Financial story can change quickly if deposit competition forces materially higher funding costs or if weaker volumes hit the Cash Connect fee stream.
Find out about the key risks to this WSFS Financial narrative.
Another view on WSFS Financial’s valuation
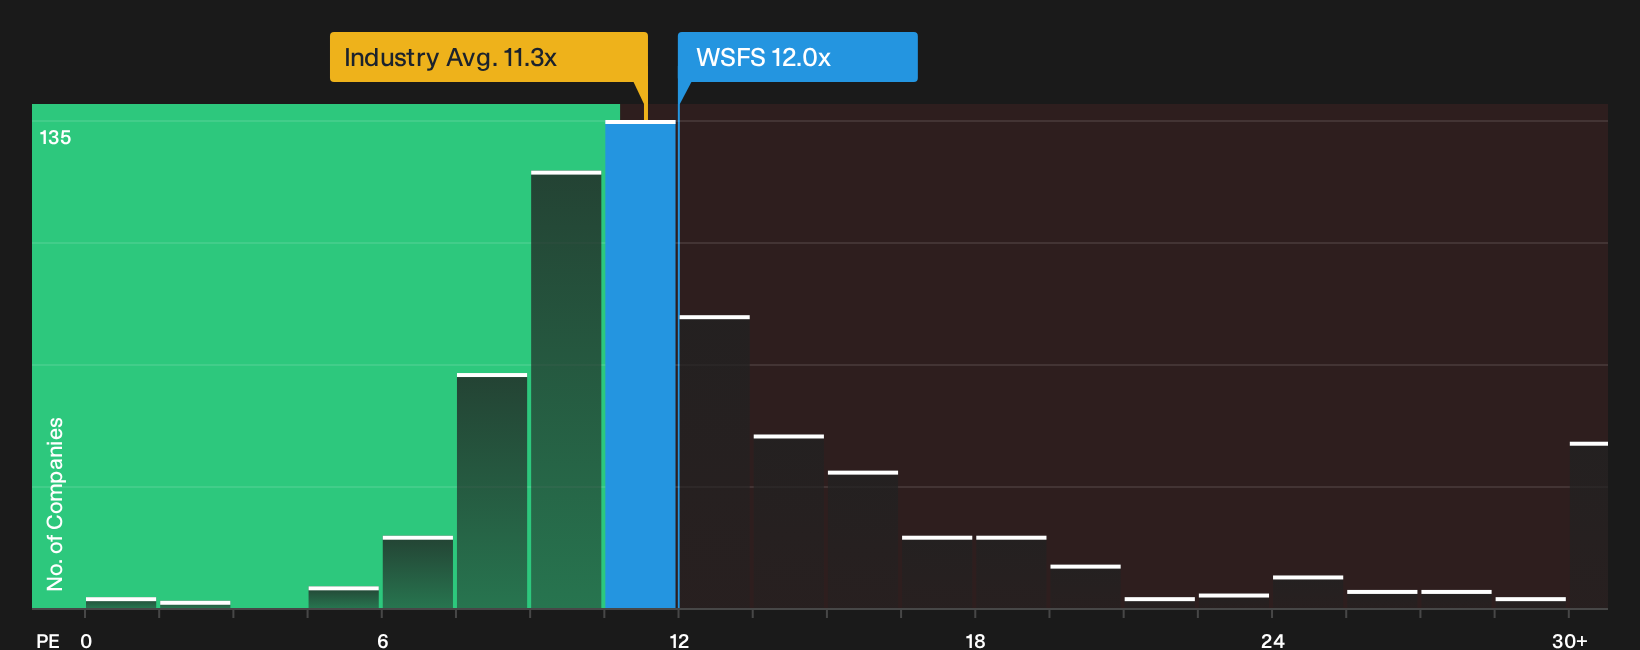
On simple earnings multiples, WSFS Financial looks less generous. The stock trades on a P/E of about 12x, slightly higher than the US Banks industry at 11.3x and above a fair ratio estimate of 11x, which points to less margin for error if growth or returns disappoint.
Putting that side by side with an undervaluation story based on long term earnings power gives you two very different lenses on the same US$4.0b bank. The question is which signal you trust more when expectations and reality eventually meet.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around WSFS Financial leave you on the fence, that is exactly the moment to check the hard numbers yourself. To see what has investors optimistic, review the 2 key rewards.
Looking for more investment ideas beyond WSFS Financial?
WSFS Financial might be on your radar, but your next strong move probably comes from widening the field and comparing it with a few carefully filtered contenders.
- Target steadier ride potential by scanning 31 resilient stocks with low risk scores that aim to keep volatility in check while still giving your capital meaningful room to work.
- Spot mispriced opportunities early and comb through 19 high quality undiscovered gems before the wider market starts paying attention and shifts the odds away from you.
- Strengthen your core holdings by reviewing the 7 dividend fortresses that can help support your returns with cash payouts alongside any share price moves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com