
How European Credit Launch Will Impact Apollo Global Management Stock
- Apollo Global Management reported third quarter 2026 revenue of US$4,739 million and a net loss of US$1,057 million, while continuing its buyback program and affirming a quarterly dividend of US$0.5625 per share.
- The launch of European Credit Company with more than €10 billion of lending capacity highlights Apollo Global Management’s push to build a scaled European performing credit platform backed by long term institutional capital.
- We will now look at how Apollo Global Management’s investment narrative is shaped by the launch of its European Credit Company platform.
Compare Apollo Global Management’s latest buybacks, dividend affirmation and European credit push with a curated set of alternatives by screening for 19 high quality undiscovered gems, which may be flying under most investors’ radar.
What Is Apollo Global Management's Investment Narrative?
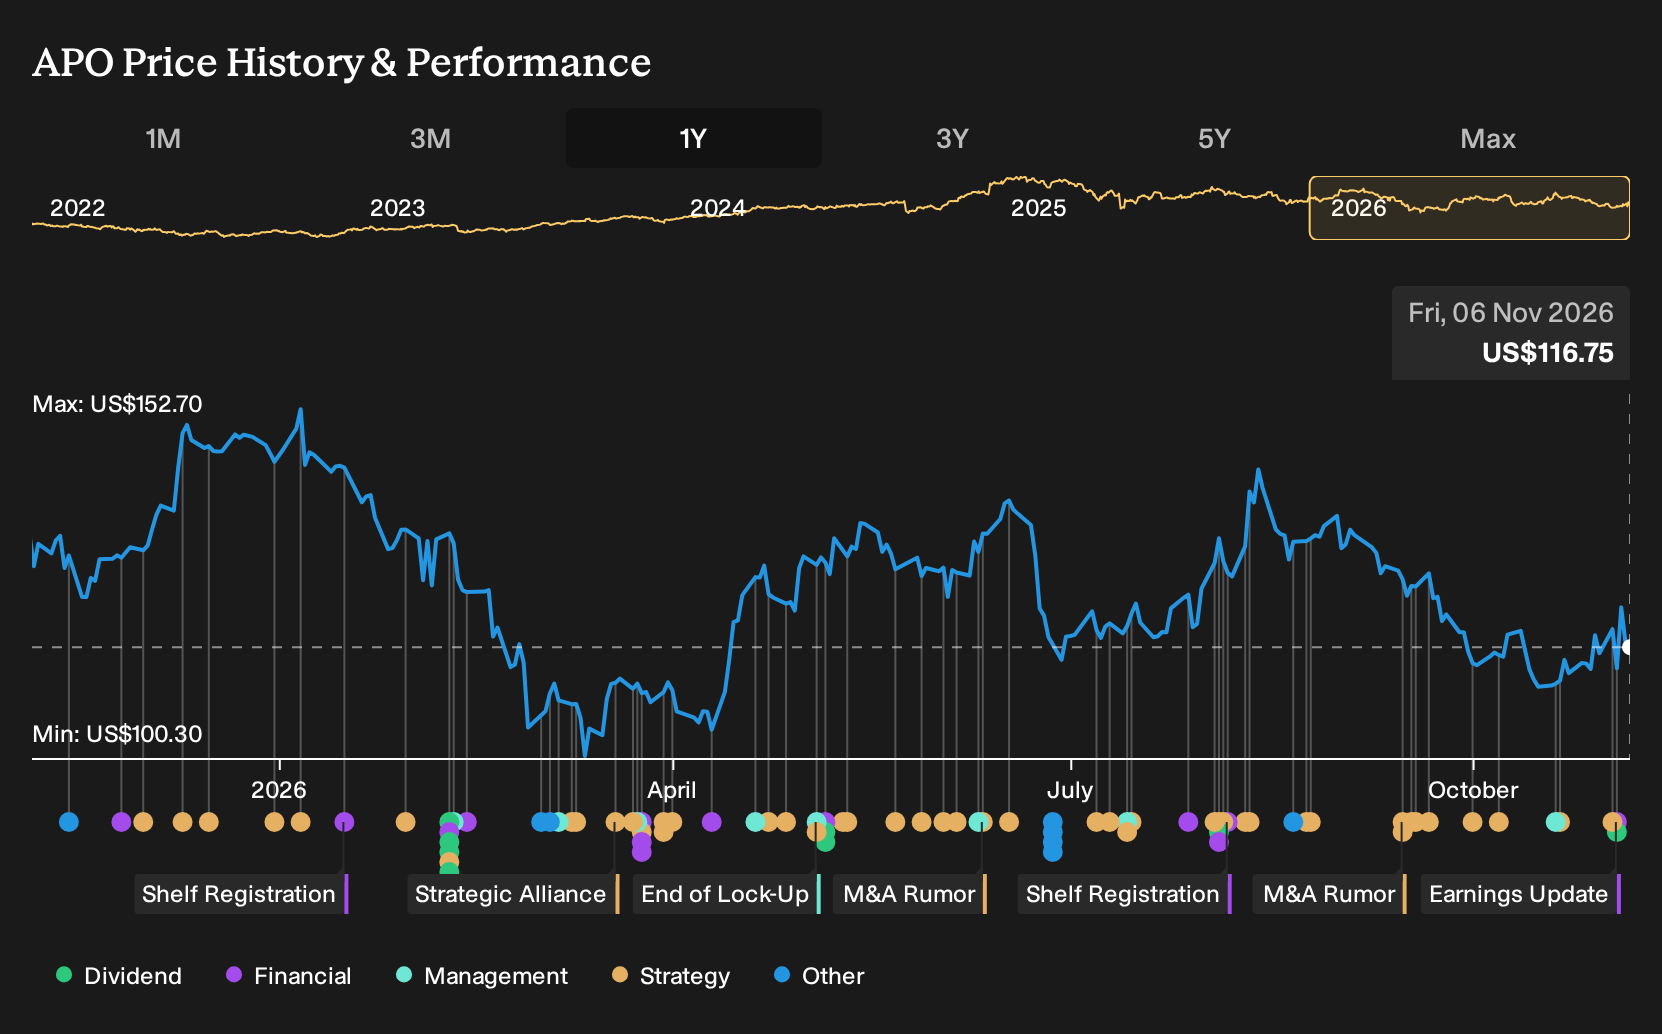
The big belief with Apollo Global Management is that you are backing an asset manager that leans heavily on fee based, credit focused investing, even when reported earnings swing around. The latest quarter showed revenue of US$4,739 million and a net loss of US$1,057 million. Management still bought back shares and affirmed a US$0.5625 dividend. That combination only really makes sense if you think the underlying origination engine and client demand for private credit remain intact despite the recent 1 year share price decline of 9.3%.
The launch of European Credit Company adds another capital intensive platform on top of already higher risk funding, since liabilities are entirely external borrowing rather than deposits. For short term catalysts, investors are likely to watch how quickly that more than €10 billion of lending capacity gets put to work and whether fee related income offsets the hit from weaker reported revenue. At the same time, a dividend that is not well covered by earnings and fresh insider selling in the past 3 months keep execution risk very real if deal flow or asset values disappoint.
Even so, there is one pressure point in Apollo Global Management’s story that becomes much harder to ignore once you look closely at ...
There's only one way to know the right time to buy, sell or hold Apollo Global Management. Head to Simply Wall St's company report for the latest analysis of Apollo Global Management's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$146.25 and about US$159.43, so even a tiny sample already shows how far views on Apollo Global Management can stretch. Recent buybacks, the launch of European Credit Company, and the affirmed dividend provide concrete events to test those opinions against. Explore other community viewpoints before deciding how this mixed picture fits your own thesis.
Explore another Apollo Global Management fair value estimate, including one that suggests as much as 37% upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Apollo Global Management research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Apollo Global Management. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Apollo Global Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Apollo Global Management?
If Apollo Global Management’s mix of private credit, buybacks and dividends has sharpened your thinking, broaden that research by lining it up against a wider watchlist built from the Simply Wall St Screener.
- For investors hunting for quality at a reasonable entry point, compare Apollo Global Management with 40 high quality undervalued stocks that currently combine solid fundamentals with compressed expectations.
- If income reliability is your priority, set Apollo alongside 7 dividend fortresses that focus on payout strength and consistency.
- For a focus on financial resilience, weigh Apollo Global Management against a list of solid balance sheet and fundamentals (25 results) that can help you stress test balance sheet strength across your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com