
Home Depot Stock: Analyst Estimates & Ratings
With a market cap of $342.7 billion, The Home Depot, Inc. (HD) is the world's largest home improvement retailer, operating a network of big-box stores across the United States, Canada, and Mexico. Headquartered in Atlanta, Georgia, the company sells a wide range of home improvement products, including building materials, hardware, tools, appliances, flooring, paint, plumbing supplies, and garden equipment.
Shares of the Atlanta, Georgia-based company have lagged behind the broader market over the past 52 weeks. HD stock has fallen 6.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 9.8%. Moreover, shares of the company have dropped marginally on a YTD basis, compared to SPX's 7.8% gain.
Zooming in further, the stock has underperformed the State Street SPDR S&P Homebuilders ETF's (XHB) 2.1% return over the past 52 weeks.
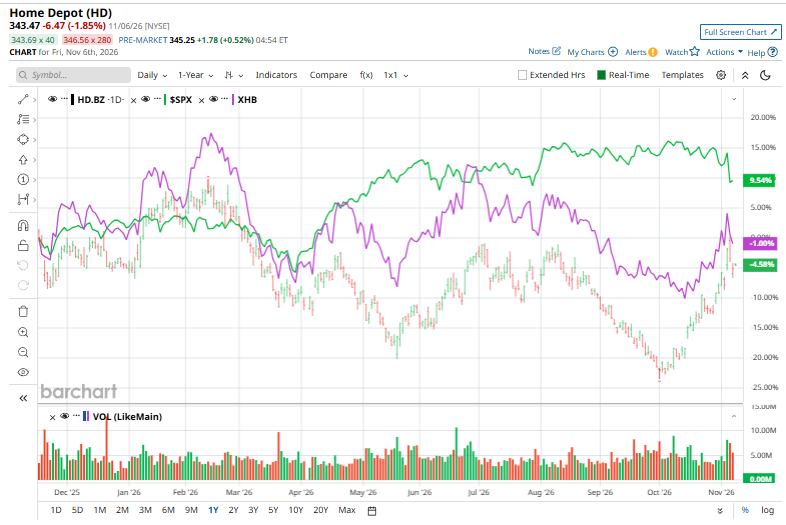
Home Depot continues to face headwinds from elevated mortgage rates, high home prices, and sluggish housing turnover, which have prompted homeowners to delay discretionary renovation projects. Inflation, rising material costs, and expensive financing have further weighed on home improvement spending, pushing HD shares to a 52-week low in early October.
For the fiscal year ending in January 2027, analysts expect The Home Depot's adjusted EPS to grow 2.2% year over year to $15.01. The company's earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing on another occasion.
Among the 35 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on 21 "Strong Buy" ratings, one "Moderate Buy," 12 "Holds,” and one "Strong Sell."
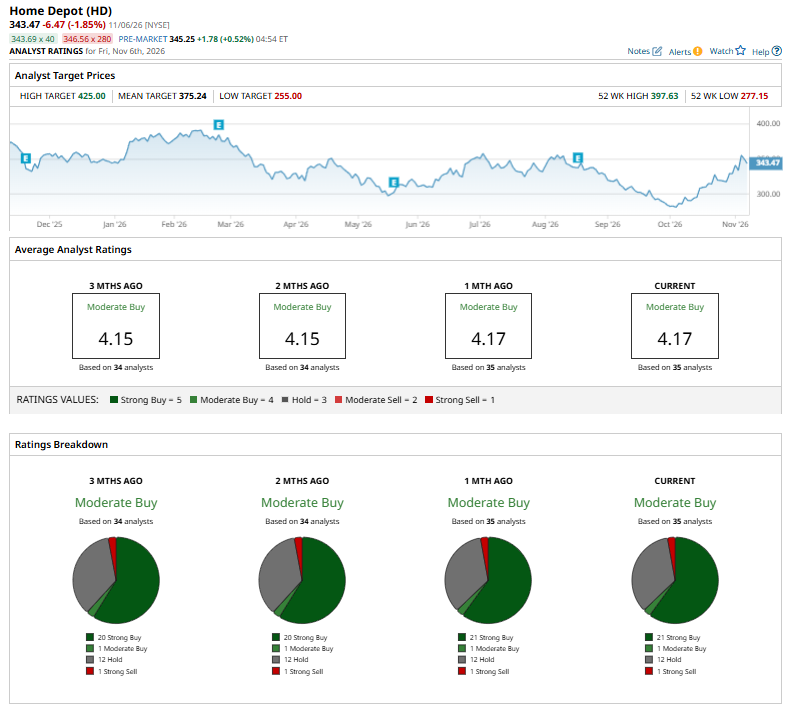
This configuration is slightly less bullish than two months ago, with 20 “Strong Buy” ratings on the stock.
On Oct. 26, Stifel analyst W. Andrew Carter maintained a “Hold” rating on Home Depot and lowered his price target to $322 from $346, a 6.9% reduction, signaling a more cautious outlook on the stock's upside potential.
The mean price target of $375.24 represents a 9.2% premium to HD’s current price levels. The Street-high price target of $425 suggests a 23.7% potential upside.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.