
Missed WuXi AppTec's Rally? Here's What Early Buyers Saw
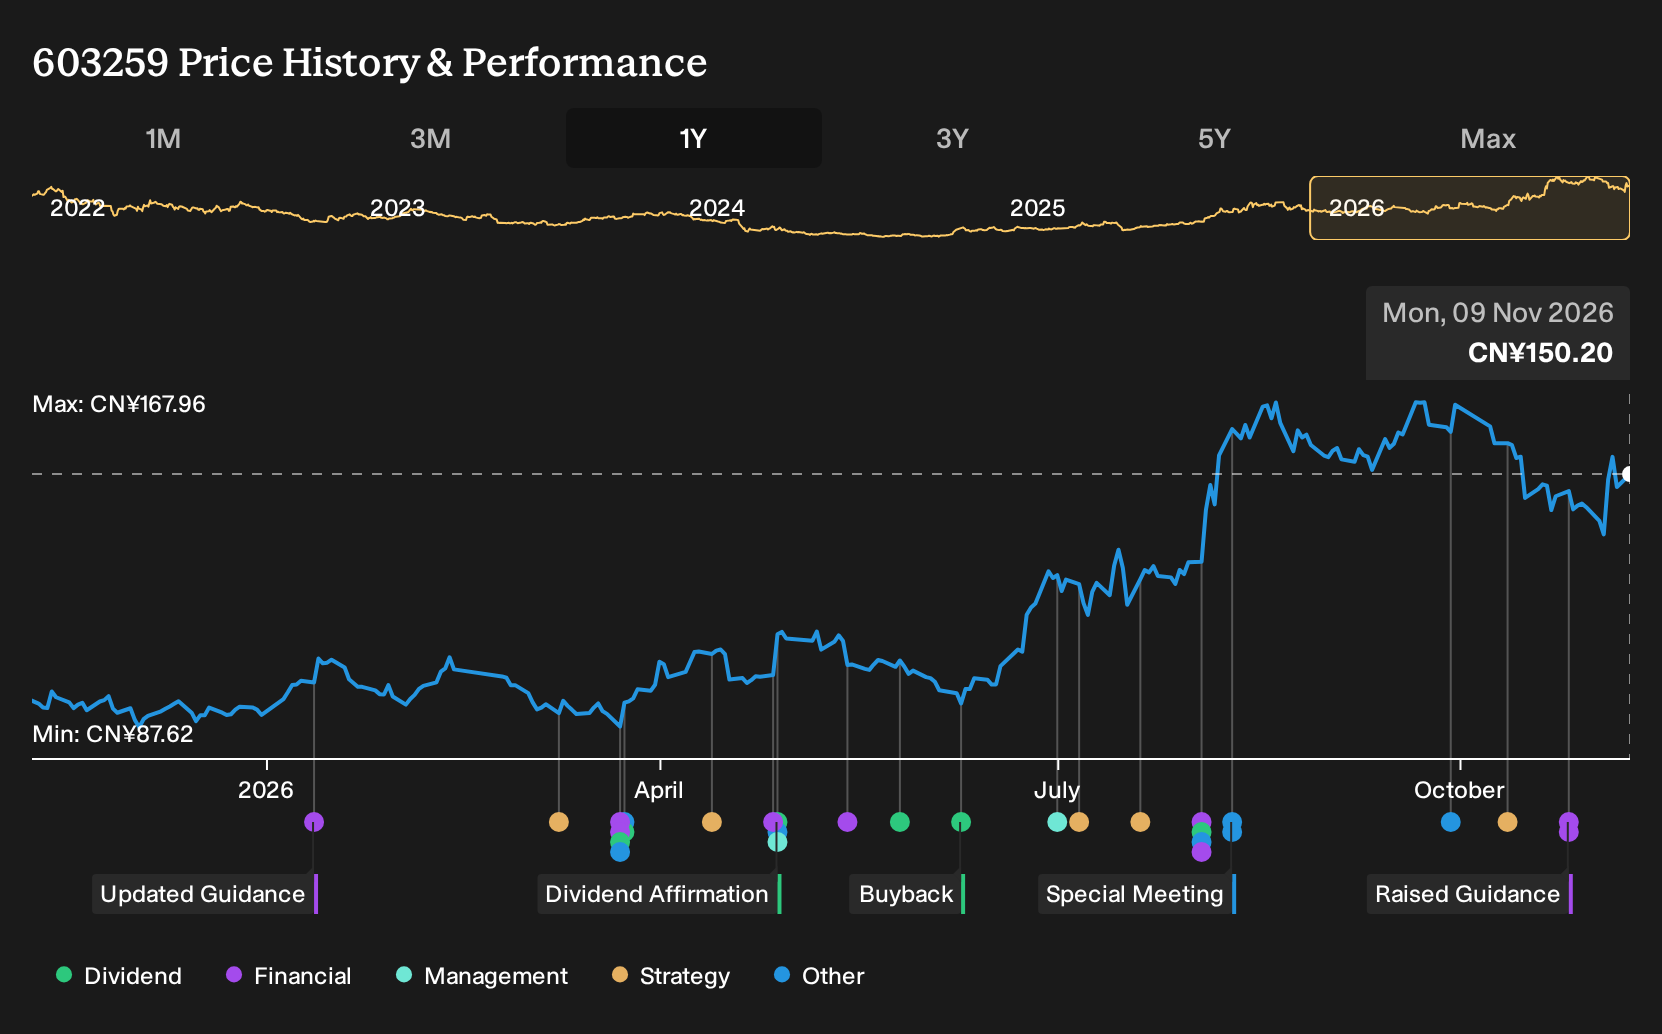
If you had committed fresh money to WuXi AppTec in November 2025, the past year would now look very different on your brokerage screen. Holding WuXi AppTec over the past year would have returned 63.8%, including dividends. That outcome naturally jumps off the page, but early buyers were not staring at clean Q3 2026 results and raised revenue guidance. If you were weighing a position then, how would you have balanced capacity expansion, global demand, and rising geopolitical risk?
If the move has made WuXi AppTec harder to judge, start where the gap is still open and scan 223 high quality undervalued stocks.
Two Stories WuXi AppTec Investors Were Choosing Between
WuXi AppTec shares cost CN¥94.84 at the start of the period, and you were effectively choosing between two very different stories about what came next.
On the optimistic side, the bullish narrative saw a Fair Value of CN¥115, a price implied by expectations that revenue could rise about 14.0% a year and profit margins might settle near 25.3% as new high value capacity and global expansion filled up.
The cautious view pointed to a Fair Value of CN¥89.7, a level tied to concerns that geopolitical and regulatory pressure, along with regionalised supply chains, could weaken international demand and compress margins despite past investment in new facilities.
What The WuXi AppTec Results Put To The Test
The biggest data point landed with Q3 2026. WuXi AppTec reported revenue of CN¥16,639.95m and net income of CN¥8,318.13m, up from CN¥12,057.43m and CN¥3,514.63m a year earlier, with net margin rising from 29.1% to 50.0%. Strong Q1 to Q3 2026 results and raised full year guidance supported more of the optimistic case, while ongoing geopolitical and regulatory pressure still backed parts of the cautious view, so the evidence cut both ways.
The clear hinge here was whether new capacity and higher value projects could show up in margins. For another company, treat any big capex story as unfinished until you can match it against later revenue, absolute profit and margin data in the results line.
What WuXi AppTec's Price Already Assumes
WuXi AppTec now trades at CN¥150, after a 63.8% gain over the past year. The Narrative’s Fair Value sits below that level, so the author sees today’s quote as baking in a richer outlook than their own work supports.
According to DDakhno, an investor in the Simply Wall St Community who wrote the Narrative, the key debate is whether WuXi AppTec can keep leveraging its CRDMO scale while managing political risk around US legislation. A buyer today has to judge whether customer reliance holds up despite the BIOSECURE Act process.
"As of today, WuXi AppTec is No. 1 in the world in chemistry for drug development. However, its position in 2026 is determined by the struggle with the American BIOSECURE Act."
One Narrative disagrees with today's price. → See where this Narrative says WuXi AppTec should trade
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 18% below our estimate - supplies specialized memory that relieves bandwidth bottlenecks in intensive AI training workloads.
- Company 2 - 42% below our estimate - applies analytical models to improve risk selection and automate complex insurance claims decisions.
- Company 3 - 20% below our estimate - expands adoption of drug-eluting bone grafts into harder-to-treat, infection-related orthopedic procedures.
Those are three of them. See every one of the 193 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com