
Can Vornado Realty Trust (VNO) Trade At A Discount After Q3?
Vornado Realty Trust has delivered a very strong 3 year share price return, which puts fresh attention on whether the current US$35.82 level lines up with the cash being generated by its properties. With investors watching both recent leasing activity and headline net losses, the key issue is how those accounting results translate into long term cash flows for equity holders.
- The stock has gained 88.5% over the past 3 years, so anyone looking at Vornado Realty Trust today is effectively asking whether that move already reflects the value of its future cash flows.
- Recent reports show higher funds from operations alongside a net loss, which can affect how reliably investors view current earnings power as a guide to future cash generation.
- Prefer to judge Vornado Realty Trust on sales? See why Vornado Realty Trust's 3.5x P/S tells a different valuation story.
The issue now is whether Vornado Realty Trust's current share price is fully supported by the intrinsic value suggested by its projected cash flows under a Discounted Cash Flow (DCF) approach.
To test whether Vornado Realty Trust's cash flow story is unique or just one example, you can compare it with 40 high quality undervalued stocks
Is Vornado Realty Trust a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here uses adjusted funds from operations to estimate what Vornado Realty Trust's future cash generation could be worth today. Latest twelve month free cash flow sits at about $485.4 million, and the projections used in the model assume that cash flow grows from this base over time rather than shrinking.
That pattern of recovering cash flow lifts the implied intrinsic value meaningfully above the current share price of $35.82, according to this DCF framework. Because the recent quarter combined a reported net loss with higher funds from operations, the market reaction to the Q3 2026 numbers may help explain why the share price has not closed that gap yet, even as the DCF points to stronger underlying cash generation. Find out what Vornado Realty Trust could be worth using our Discounted Cash Flow (DCF) estimate.
The Vornado Realty Trust Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that valuation gap leaves off for Vornado Realty Trust by spelling out which paths for rent growth, margins and earnings would need to play out for the shares to be worth materially more or materially less than today. Instead of a single model output, they describe the future that number leans on so you can follow real world developments and see whether those assumptions still stack up. Narratives for Vornado Realty Trust sit on Simply Wall St's Community page.
Bulls and bears looking at Vornado Realty Trust are mainly arguing over how much of the premium Manhattan story flows through after debt and capex.
Bull case: 10% undervalued
According to the analyst consensus Narrative on Simply Wall St, the upside case leans heavily on visible leasing progress and redevelopment returns.
"A sizeable signed but not occupied rent pipeline of roughly US$180 million to US$200 million of annual revenue, with management indicating around US$150 million of associated FFO and about US$0.40 per share of FFO uplift over several years, provides visibility on future earnings expansion as these tenants move in…"
Discover why this Narrative puts Vornado Realty Trust at 10% undervalued.
Bear case: 16% overvalued
The bearish analyst Narrative on Simply Wall St focuses on how funding and leverage can soak up more of that premium rent story.
"Although Vornado Realty Trust is benefiting from a tight high quality Manhattan office market with low vacancy and tenants willing to pay premium rents for better buildings, elevated leverage near 8x debt to EBITDA and billions of dollars of upcoming maturities could divert more rental income toward interest and refinancing costs, limiting the extent to which revenue growth converts into higher free cash flow…"
Explore why this Narrative puts Vornado Realty Trust at 16% overvalued.
One more open question for Vornado Realty Trust
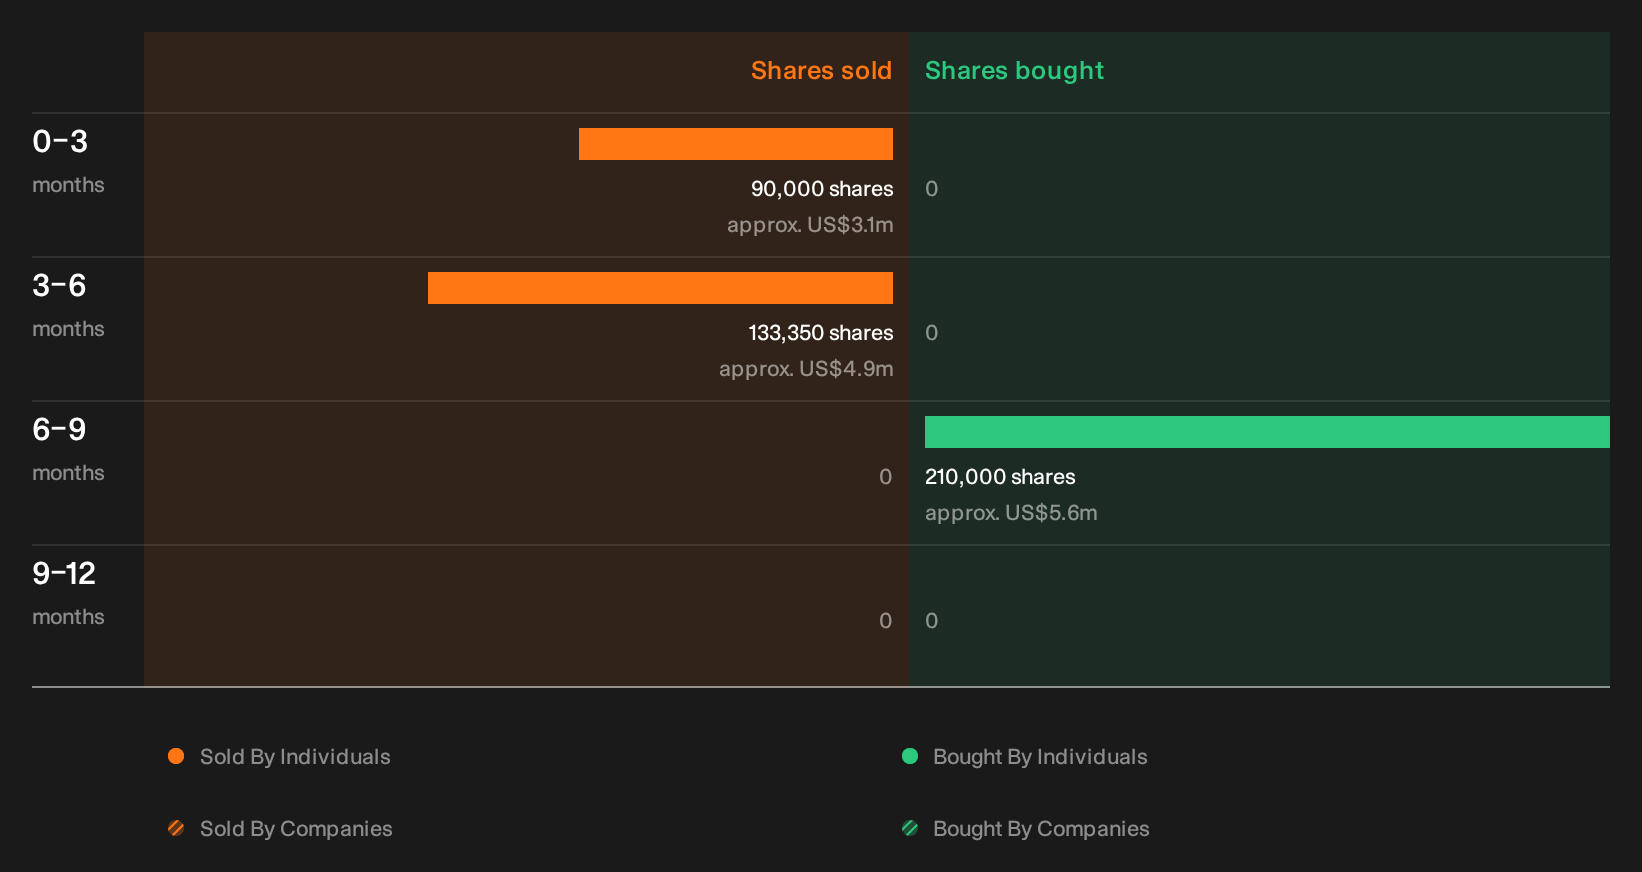
There is one more piece of the Vornado Realty Trust story that deserves a closer look, as recent insider share sales have been flagged by our checks and the specific sellers, volumes and possible signals are left for you to review. See the recent insider selling flagged for Vornado Realty Trust.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com