
What V.F Doubters Overlooked
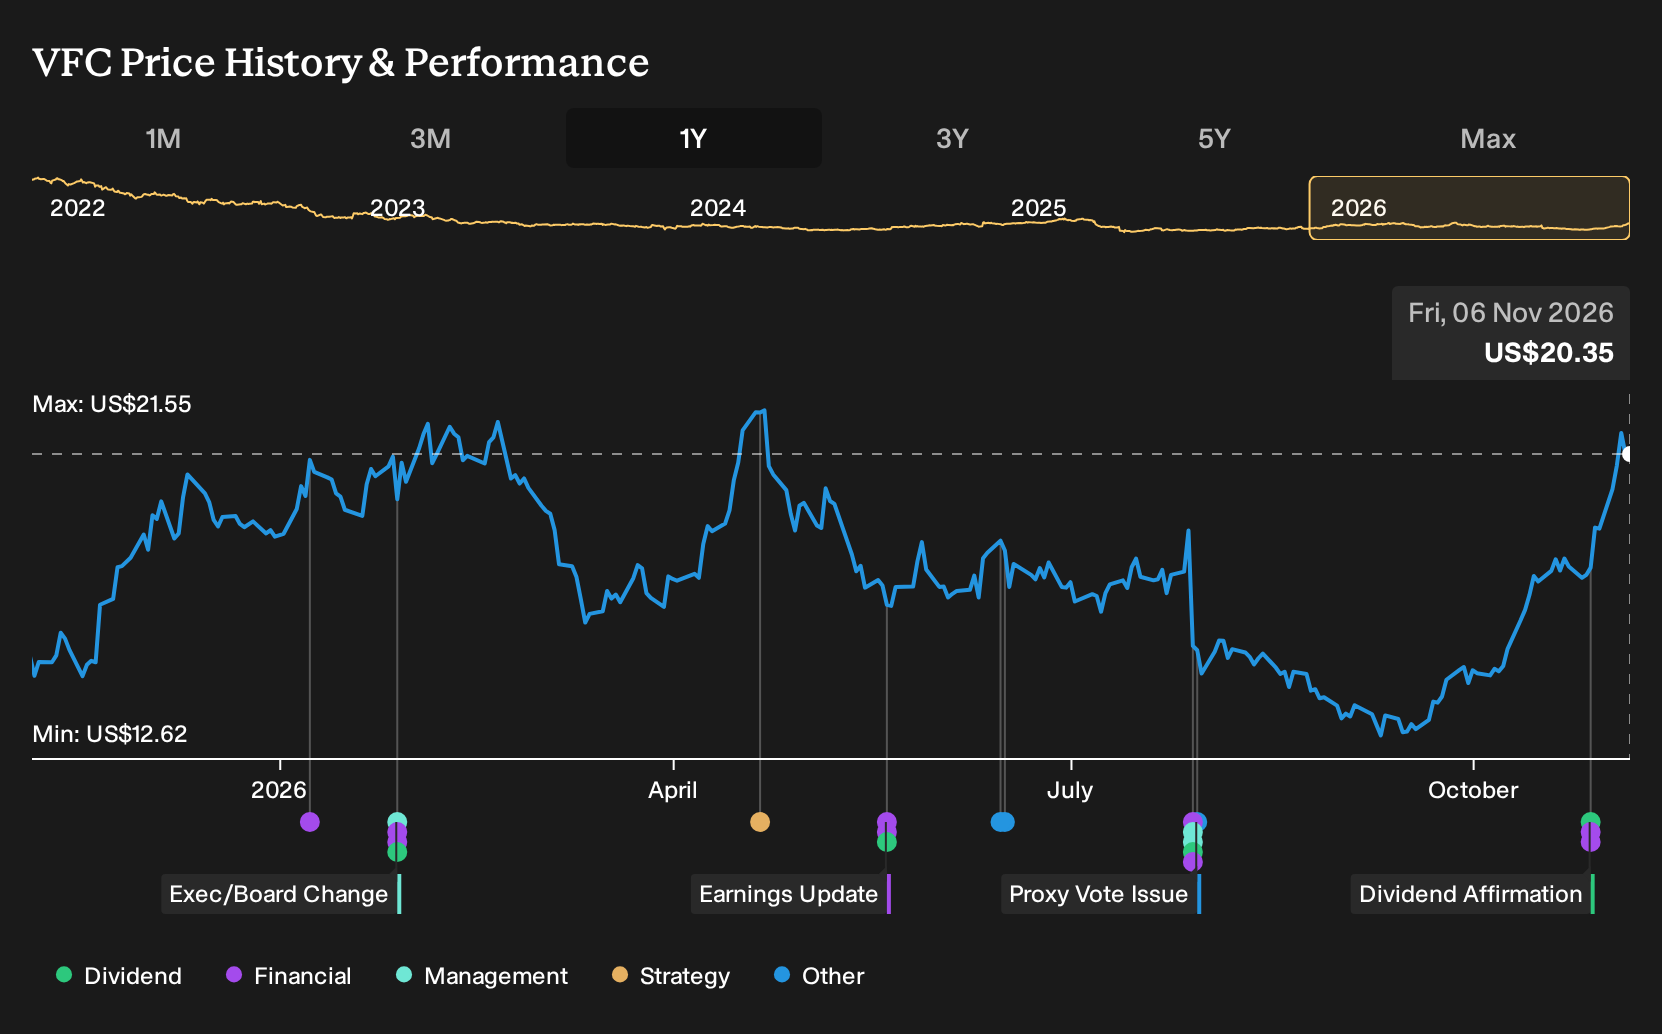
If V.F was on your watchlist instead of in your portfolio, the recent payoff may feel like a missed call. Investors who held V.F over the past year are up 42.3%, including dividends. That outcome naturally raises a question. Back on 6 November 2025, when analysts were split between modest growth and ongoing brand decline, what signals around V.F’s push into higher margin direct-to-consumer channels could have helped you judge the risk was worth taking?
If the move has made V.F harder to judge, start where the gap is still open and scan 40 high quality undervalued stocks.
The Two Stories V.F Investors Had To Weigh
The shares cost US$14.26 at the start of the period, and V.F sat between two very different but credible storylines about where the business could go next.
The bullish view saw upside to a Fair Value of US$15.49, a rough guide to what that narrative thought the stock was worth, built on revenue growth of 2.6% a year and profit margins rising toward 5.6%.
The bearish script pointed to a Fair Value of US$10, anchored in an assumption that sales would decline 1.5% annually while margin improvement to 4.8% still left Vans and other legacy brands at risk of structural demand pressure.
What The Results Changed For The V.F Story
The clearest development was V.F lifting net income in Q2 2027 while total revenue was lower than in Q2 2026. Net margin moved from 6.8% to 10.6%. That pattern supported the optimistic case that higher margin channels and cost work could lift profitability, although the drop in sales kept the cautious storyline about brand pressure alive. Overall, the evidence pointed in both directions.
The key assumption here was margin quality. For another retailer, you would want to check whether rising profitability comes with flat or falling revenue, and then test whether that mix still matches the thesis you are paying for.
What V.F’s Current Price Already Assumes
V.F now trades at US$20.35, well above where the recent 42.3% one year return began, and this bearish analyst Narrative on Simply Wall St places its Fair Value below that quote. The gap reflects a view that the recent turnaround progress is real but still leaves little margin for execution slip.
Anyone paying today’s price is effectively assuming management can convert cost savings, tariff mitigation and brand investment into steady cash generation. The question raised by this Narrative is how that belief holds up if Vans stabilizes smaller and APAC demand or tariffs do not cooperate.
"The main thing that has to go right is that management turns the reported SG&A savings, gross margin gains and balance sheet deleveraging into durable cash generation while successfully rebuilding Vans and reinvesting behind the outdoor and performance portfolio."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 18% below our estimate - enable higher capacity and speed for AI-intensive data processing and storage.
- Company 2 - 33% below our estimate - match AI infrastructure deployment to flexible subscription and usage-based customer demand.
- Company 3 - 40% below our estimate - integrate compute, networking and software into unified AI factory systems for enterprises.
That is three of the list. See every one of the 25 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com