
Credo Stock Has a Powerful Growth Story, but Is It Already Priced In?
The 24/7 Wall St. price target for Credo (NASDAQ:CRDO) is $206.69. The target implies 36.97% upside from the $150.90 close on November 3, 2026, and our model carries high conviction.
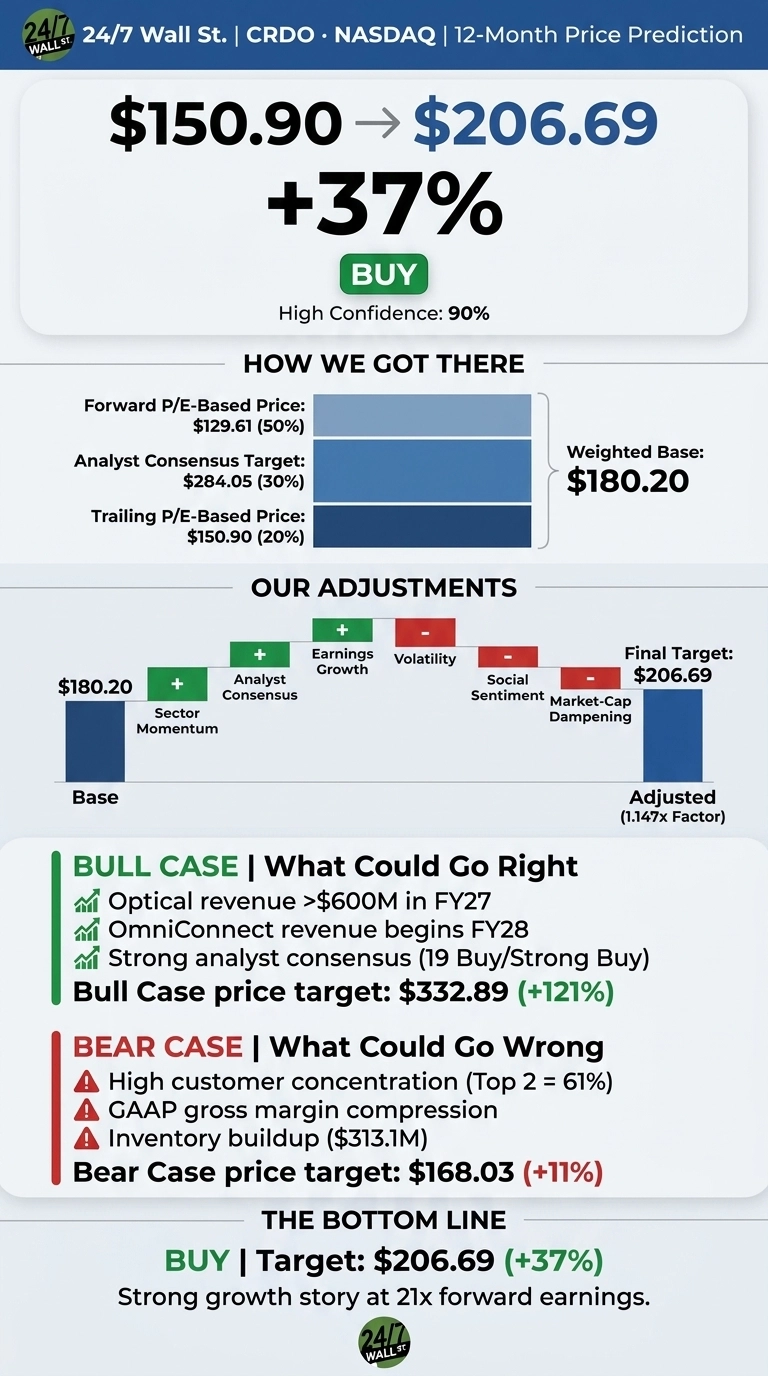 24/7 Wall St. Metric Value Current Price $150.90 Price Target from 24/7 Wall St. $206.69 Upside/Downside 36.97% Recommendation BUY Confidence Level 90%
Credo shares are down sharply even as the business continues accelerating. Management expects fiscal 2027 revenue growth above 85%. The recent selloff has already taken a lot of the excitement out of the stock price. Shares were showed at $145.80 ahead of the November 4 open.
A 33% One-Month Slide Resets ExpectationsCredo fell 12.92% over the past week and 33.32% over the past month. That leaves it up just 1.33% year to date. At $150.90, the stock trades 51% below its 52-week peak of $308.67 and 74% above its trough of $86.48. The drop came after a strong quarter.
Q1 fiscal 2027 revenue of $479.0M rose 114.7% and beat the $470.4M consensus. Non-GAAP EPS of $1.20 exceeded the $1.17 estimate, making it Credo’s 8th consecutive beat. Q2 guidance calls for revenue of $525M-$535M.
Optics Could Drive Credo Toward $332The bull case reaches $332.89, a 120.61% gain. Management expects optical revenue above $600 million in fiscal 2027. ZeroFlap optics, silicon photonics PICs and optical DSPs should each contribute more than $100 million.
OmniConnect, which begins generating revenue in fiscal 2028, could add “thousands of dollars of Credo content per GPU.” Wall Street is overwhelmingly bullish. Analysts list 5 Strong Buys, 14 Buys, one Hold and no Sells. Their consensus target of $284.05 implies 88% upside.
Customer Concentration Is the Risk to WatchCredo’s largest customer accounted for 33% of revenue last quarter, and the next largest accounted for 28%. GAAP gross margin slipped to 64.5% from 68.2%. Most of that decline reflects amortization from the Dust Photonics acquisition, which raised goodwill to $986.45M. On a non-GAAP basis, gross margin held at 68%.
Stock-based compensation reached $87.98M, and inventory rose to $313.1 million. Management says the inventory build is intentional supply preparation. Our bear case of $168.03 still sits above today’s price. However, last month’s slide shows that a stock with this much volatility can fall further than any model expects.
How Credo Compares to Broadcom, Marvell and Astera LabsThe scale benchmark for AI networking is Broadcom (NASDAQ:AVGO). Its AI semiconductor revenue reached $16.70 billion, up 221%. Credo has narrower exposure but grows faster in total (we covered seven of these AI infrastructure suppliers, from power to networking, in a free report you can grab here).
Marvell Technology (NASDAQ:MRVL) competes directly in optical DSPs. Its revenue grew 36.55% with a non-GAAP gross margin of 58.9%, below Credo’s 68%.
Astera Labs (NASDAQ:ALAB) is the closest pure-play comparison. The multiple sits at 185x earnings, while Credo trades at 21x forward earnings. Against this group, our target looks conservative.
Company Latest Quarter Revenue Growth Latest Non-GAAP EPS Credo 114.7% $1.20 Broadcom 85.5% $3.32 Marvell 36.55% $0.94 Astera Labs 153.67% $1.32 Triple-Digit Growth at 21x Forward Earnings Tips the ScaleOur 24/7 Wall St. price target remains $206.69, with a buy rating and 90% confidence. The deciding factor for me is the valuation: a business growing triple digits now trades at 21x forward earnings.
The bull case strengthens if the optical ramps meet the $600 million target. The thesis weakens if the largest customers start cutting orders. At today’s price, I think the growth story has been marked down too far.
Our model projects the following path over a longer horizon, given current growth trends and market conditions hold.
Year Price Target from 24/7 Wall St. 2026 $206.69 2027 $216.19 2028 $266.82 2029 $311.81 2030 $348.03The projections rest on Credo continuing to carry out its optical and copper strategy. A shift in hyperscaler AI spending could drive results well above or below this path.